


EN
MasterBrand Stock Price Focus Turns To CFO Change And Interim Finance Chief
- MasterBrand announced that Chief Financial Officer Andrea Simon stepped down on October 23, 2026, with Vice President and Chief Accounting Officer Mark Young taking on the Interim CFO role while also retaining his accounting responsibilities and Simon remaining as an adviser through March 2027.
- The handover concentrates both finance leadership and detailed accounting oversight in Young, which can shape how MasterBrand manages reporting discipline, internal controls, and capital decisions during the CFO search process.
- Next, the focus shifts to how MasterBrand's investment narrative aligns with this temporary finance leadership reshuffle and Young's expanded responsibilities.
What Is MasterBrand's Investment Narrative?
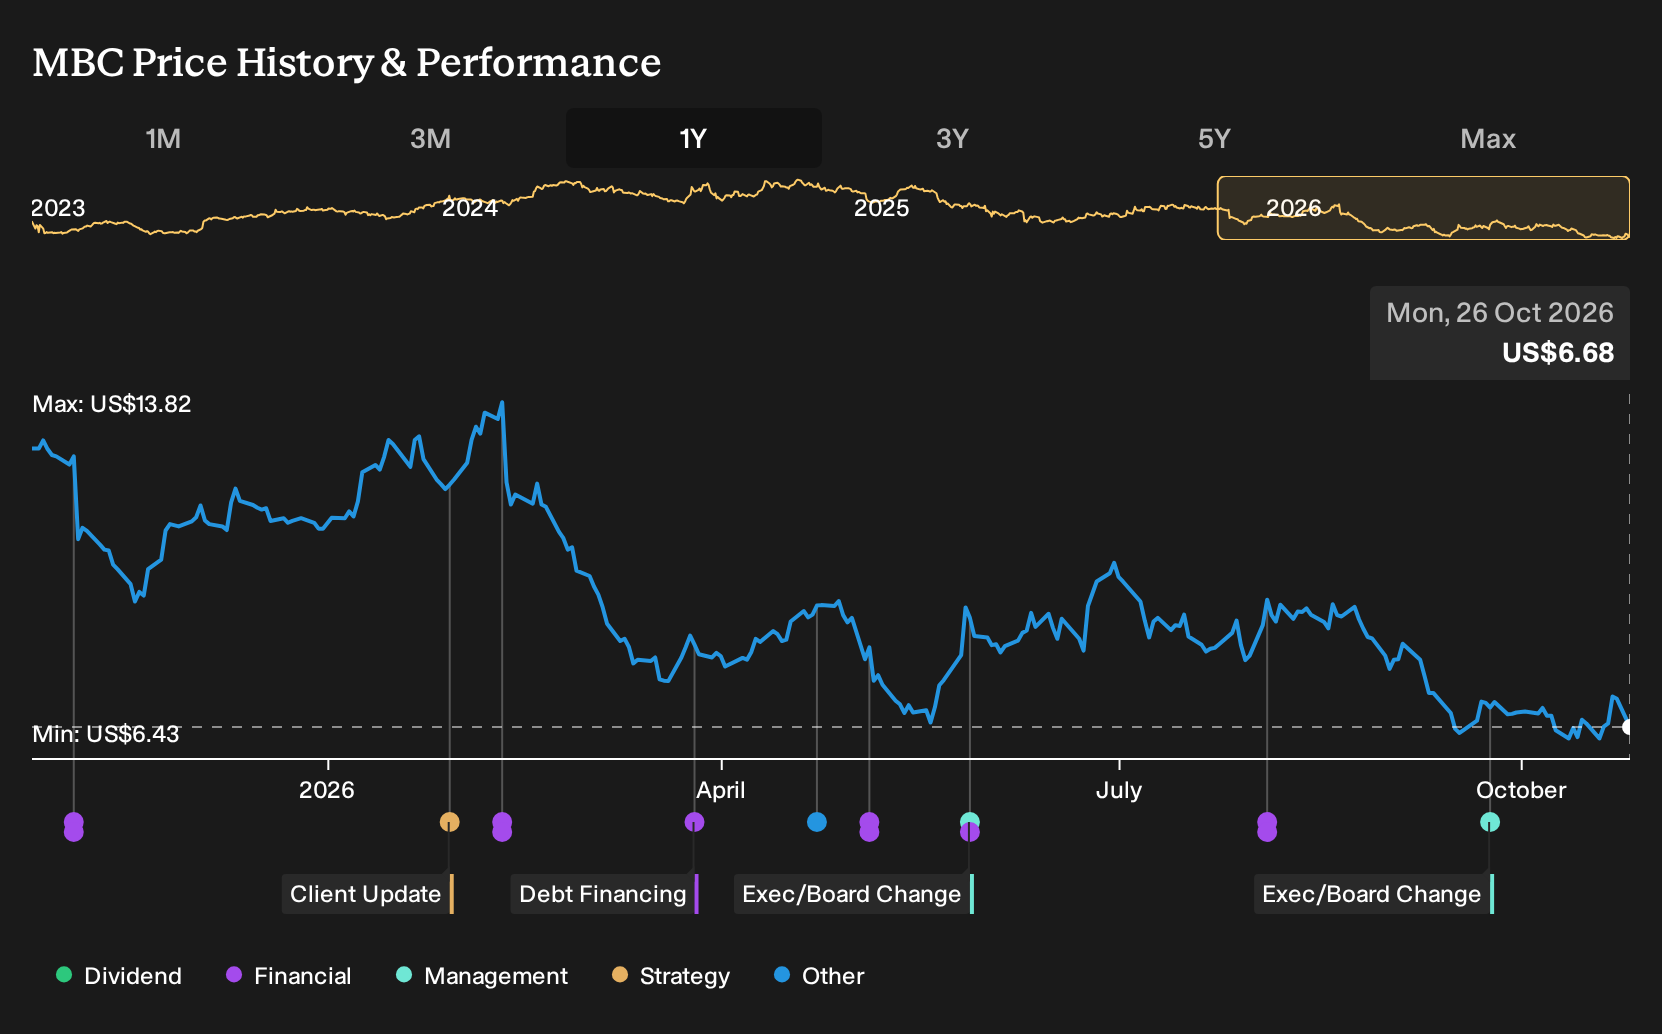
To own MasterBrand, you need to be comfortable with a cabinet maker that leans heavily on execution and demand recovery rather than a pristine profit story today. The group generated US$2.78b of sales and operates in fairly capital intensive manufacturing, so cash discipline and pricing power matter more than headlines. Revenue is forecast to grow strongly, yet the business remains loss making with interest costs not well covered and shares down sharply over 1 year. That combination puts the spotlight on cash flow, not just accounting earnings.
The CFO transition plugs directly into that reality. Mark Young already handled reporting, controls, and accounting policy, so the interim move looks more like consolidation of finance leadership rather than a reset of the MasterBrand playbook. In the short term, the bigger swing factors still look tied to demand in remodeling and new construction, the company’s ability to hold price, and how it funds itself after past shareholder dilution and recent insider selling. If those building blocks move in the right direction, the current P/S of 0.5x against higher peer and fair value metrics gives the story its appeal.
That said, one uncomfortable thread still hangs over the MasterBrand equity story and it has to do with...
There's only one way to know the right time to buy, sell or hold MasterBrand. Head to Simply Wall St's company report for the latest analysis of MasterBrand's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community has only two fair value views on MasterBrand, yet they stretch from 1.48 to 9.63, which is a wide span for such a small sample. Those opinions were set before the CFO exit on October 23, 2026, so you are weighing fresh leadership risk against pre transition valuation thinking.
Explore another MasterBrand fair value estimate, including one that suggests as much as 78% downside from the current price.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your MasterBrand research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for MasterBrand. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MasterBrand's overall financial health at a glance.
Looking For More Investment Ideas Beyond MasterBrand?
If this CFO shuffle has you rethinking concentration risk, it might help to line MasterBrand up against a broader watchlist and see how it stacks up on quality, income and resilience using the Simply Wall St Screener.
- For investors who want growth potential without ignoring quality signals, scan through a 21 high quality undiscovered gems that already screen well on fundamentals and financial strength.
- If portfolio resilience is the priority, shortlist companies from a list of solid balance sheet and fundamentals (24 results) that emphasizes strong finances and room to absorb setbacks.
- Income focused readers who care about cash returns can review a 5 dividend fortresses that combines higher yields with an emphasis on sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com