


EN
Glacier Bancorp (GBCI) Earnings Strength Puts Valuation Back In Focus
Glacier Bancorp (GBCI) just posted third quarter results that put earnings and net interest income firmly in focus, while a separate disclosure on higher net charge offs adds another layer for investors to weigh.
The recent earnings update has come alongside a sharp shift in sentiment, with Glacier Bancorp’s share price up 12.39% over the past week and 9.50% over the last month, even though the 90 day share price return slipped 1.03% as investors previously reassessed risk around higher net charge offs. That near term move sits against a 15.74% 1 year total shareholder return and a very large 79.77% total shareholder return over three years, a mix that suggests momentum has picked up again as the latest margin and capital deployment commentary lands.
Scan how Glacier Bancorp’s latest margin and earnings momentum compares to other banks showing similar traits in our handpicked list of solid balance sheet and fundamentals (24 results).
After a 12% weekly jump and a 3-year return that is very large, Glacier Bancorp is no longer an obvious bargain based on recent history. Is it still reasonable to consider buying now, or does patience make more sense?
Most Popular Narrative: 12% Undervalued
Glacier Bancorp is trading at $49, while the most followed valuation storyline points to a fair value of about $55.83. This frames the recent share price rebound in a different light for anyone focused on long term cash flows instead of just the latest quarter.
The current valuation implies that the market is discounting Glacier Bancorp’s recent net interest margin gains, efficiency ratio improvement, and earnings growth, which supports the view that the stock may be undervalued and that the narrative remains positive.
See why 4 investors see Glacier Bancorp as 12% undervalued.
Result: Fair Value of $55.83 (UNDERVALUED)
Still, the Glacier Bancorp story leans heavily on net interest margin resilience and low credit losses, so a squeeze on funding costs or a turn in asset quality could quickly challenge this upbeat narrative.
Find out about the key risks to this Glacier Bancorp narrative.
Another View: Glacier Bancorp Through The P/E Lens
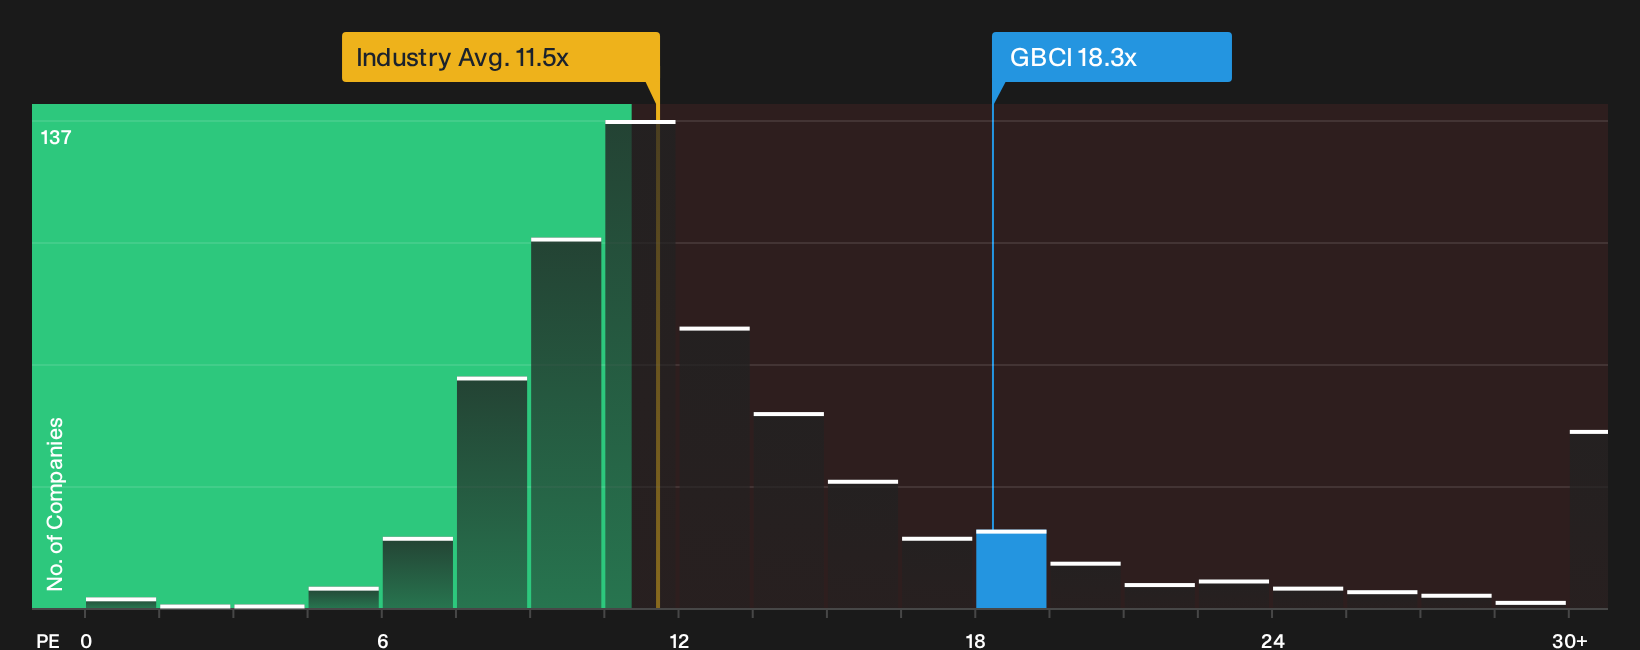
The fair value story for Glacier Bancorp looks different once the focus shifts to the P/E ratio instead of long term cash flows. The stock trades on 18.3x earnings, compared with a US Banks average of 11.5x and a fair ratio estimate of 14.3x. This points to a richer price tag and less room for disappointment if growth cools.
That gap means investors are already paying a premium multiple on GBCI versus both peers and the level the market could move toward if sentiment normalizes. The question is whether the earnings profile and balance sheet strength justify that extra P/E, or whether expectations have moved a little ahead of the fundamentals.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Glacier Bancorp feels familiar, consider reviewing the evidence yourself by looking at the 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Glacier Bancorp?
If Glacier Bancorp has sharpened your focus on quality, do not stop here. Put that curiosity to work by scanning other opportunities that could fit your goals.
- Target potential mispricing by reviewing companies that screen as high quality and possibly cheap through our 29 high quality undervalued stocks.
- Strengthen your income stream by assessing businesses that qualify as 5 dividend fortresses.
- Lean toward stability and capital protection by checking out a 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com