


EN
Iovance Biotherapeutics (IOVA) Stock Looks Pricey As Fresh Lifileucel Data Lands
Iovance Biotherapeutics has seen its share price reshape in a big way over the past year, putting a spotlight on whether the current valuation lines up with what its sales can plausibly support. After that kind of move, the key issue for you is whether the recent price level reflects justified enthusiasm around the business or runs ahead of what the revenue base suggests.
- Over the past 12 months the stock has delivered a very large gain of around 500%, which now makes the link between enterprise value and sales a crucial question.
- Fresh lifileucel data at the 2026 ESMO Congress, along with fast track designations, can shift how investors think about future sales potential, capital needs and the timing of any meaningful revenue ramp from the tumor infiltrating lymphocyte platform.
- Your read on Iovance Biotherapeutics is one view; the desks covering it have another. See what analysts think Iovance Biotherapeutics's shares could be worth.
The issue now is whether Iovance Biotherapeutics' recent share price re-rating is adequately supported by the scale and trajectory of its current sales base.
If you are weighing Iovance Biotherapeutics against other high-growth ideas tied to medical breakthroughs, it can help to compare it with a basket of 34 healthcare AI stocks.
Has Iovance Biotherapeutics Run Too Far on Sales?
P/S is the cleaner yardstick for Iovance Biotherapeutics right now because the focus is squarely on building a revenue base rather than earnings.
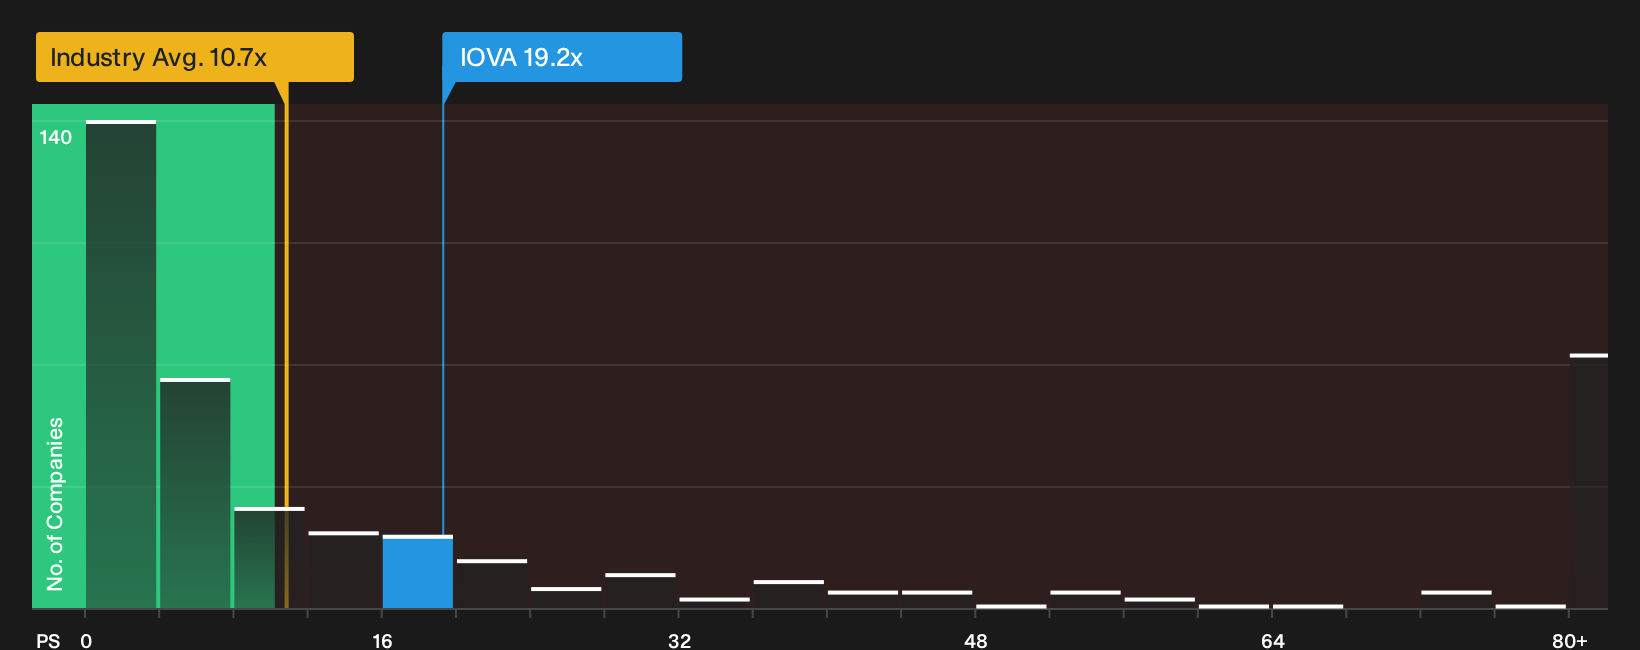
The stock trades on a P/S of 19.2x, which is above both the biotech industry average of 10.7x and the peer group average of 13.9x. Based on the tailored fair multiple that factors in Iovance Biotherapeutics' growth profile, margins, scale and risk, the current P/S screens as overvalued. Enthusiasm around the lifileucel TIL platform and the broader pipeline is being reflected in a richer sales multiple than many listed biotech peers.
Because the fresh ESMO 2026 lifileucel data and fast track designations have lifted expectations, the present 19.2x P/S requires significant confidence in how those clinical results eventually convert into commercial revenue. The key consideration is whether that premium relative to sector norms still leaves enough room for upside once the tumor infiltrating lymphocyte story is better understood. Explore the numbers behind Iovance Biotherapeutics's P/S valuation.
The Iovance Biotherapeutics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Iovance Biotherapeutics valuation puzzle leaves off. They spell out what kind of future growth, margins and earnings path would need to hold for the shares to be worth materially more or less than today’s price on the Community page. Each narrative links a fair value estimate to a specific mix of potential catalysts and risks for Iovance Biotherapeutics, so you can track over time which version of events appears to be taking shape.
Community views on Iovance Biotherapeutics are split between a turnaround story with underappreciated commercial traction and a tougher read on execution and funding risk.
Bull case: 23% undervalued
"The biggest difference is that Iovance is no longer waiting for its first product to be approved, as Amtagvi is already approved in the United States…"
Discover why this Narrative puts Iovance Biotherapeutics at 23% undervalued.
Bear case: 97% overvalued
"Bearish analysts expect Iovance Biotherapeutics to face ongoing challenges related to high costs, complex cell therapy logistics, and the risk that commercialization of Amtagvi and Proleukin does not reach a scale that covers ongoing development and operating expenses…"
Explore why this Narrative puts Iovance Biotherapeutics at 97% overvalued.
Iovance Biotherapeutics: one more key piece of the puzzle
There is still a crucial angle that has not been touched yet, which is who is steering Iovance Biotherapeutics and how their rewards line up with the outcomes you care about. See who runs Iovance Biotherapeutics and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com