


EN
Q3 Earnings Test Could Reshape The Case For Nextpower Stock (NXT)
- Nextpower is set to report Q3 results this Wednesday after market close, with consensus pointing to 17.8% year on year revenue growth, well below the 42.4% pace recorded in the same quarter a year earlier.
- The business is under pressure to reconcile slower expected top line growth with prior free cash flow projections tied to software development and acquisitions, after last quarter’s revenue, EBITDA and full year EBITDA guidance all came in below analyst expectations.
- We will look at how Nextpower's investment narrative holds up as slower expected Q3 growth coincides with rising free cash flow projections.
Nextpower Investment Narrative Recap
To own Nextpower, you need to be comfortable with a story built on converting a record backlog into cash while expanding into storage, inverters and software. The immediate test is Q3, where slower expected revenue growth meets higher free cash flow projections from software and acquisitions. If execution stays tight, the core thesis around contracted work and higher margin offerings remains intact.
The biggest near term catalyst is proof that these newer lines can support free cash flow even when tracker growth cools. The key risk is a repeat of last quarter’s execution shortfalls, especially on EBITDA, which could further shake confidence in forecasting and in how quickly backlog turns into revenue.
The most relevant reference point for this setup is the company’s own emphasis on rising free cash flow projections supported by software and recent acquisitions. That framework matters more with Q3 revenue expected to grow 17.8% year on year, slower than the 42.4% pace in the same quarter last year, because it shifts attention from pure top line to cash generation.
For you as an investor, the link between that earlier free cash flow story and Wednesday’s release is simple: solid cash conversion from TrueCapture, eBOS, storage and other higher margin offerings would reinforce the discounted cash flow view that sees Nextpower’s current share price as cautious relative to expected cash generation. Weak follow through would instead highlight the execution risk already flagged after the last guidance miss.
Nextpower's narrative projects US$6.0b revenue and US$930.6m earnings by 2029. This assumes 18.5% yearly revenue growth and about a US$336.5m earnings increase from US$594.1m today.
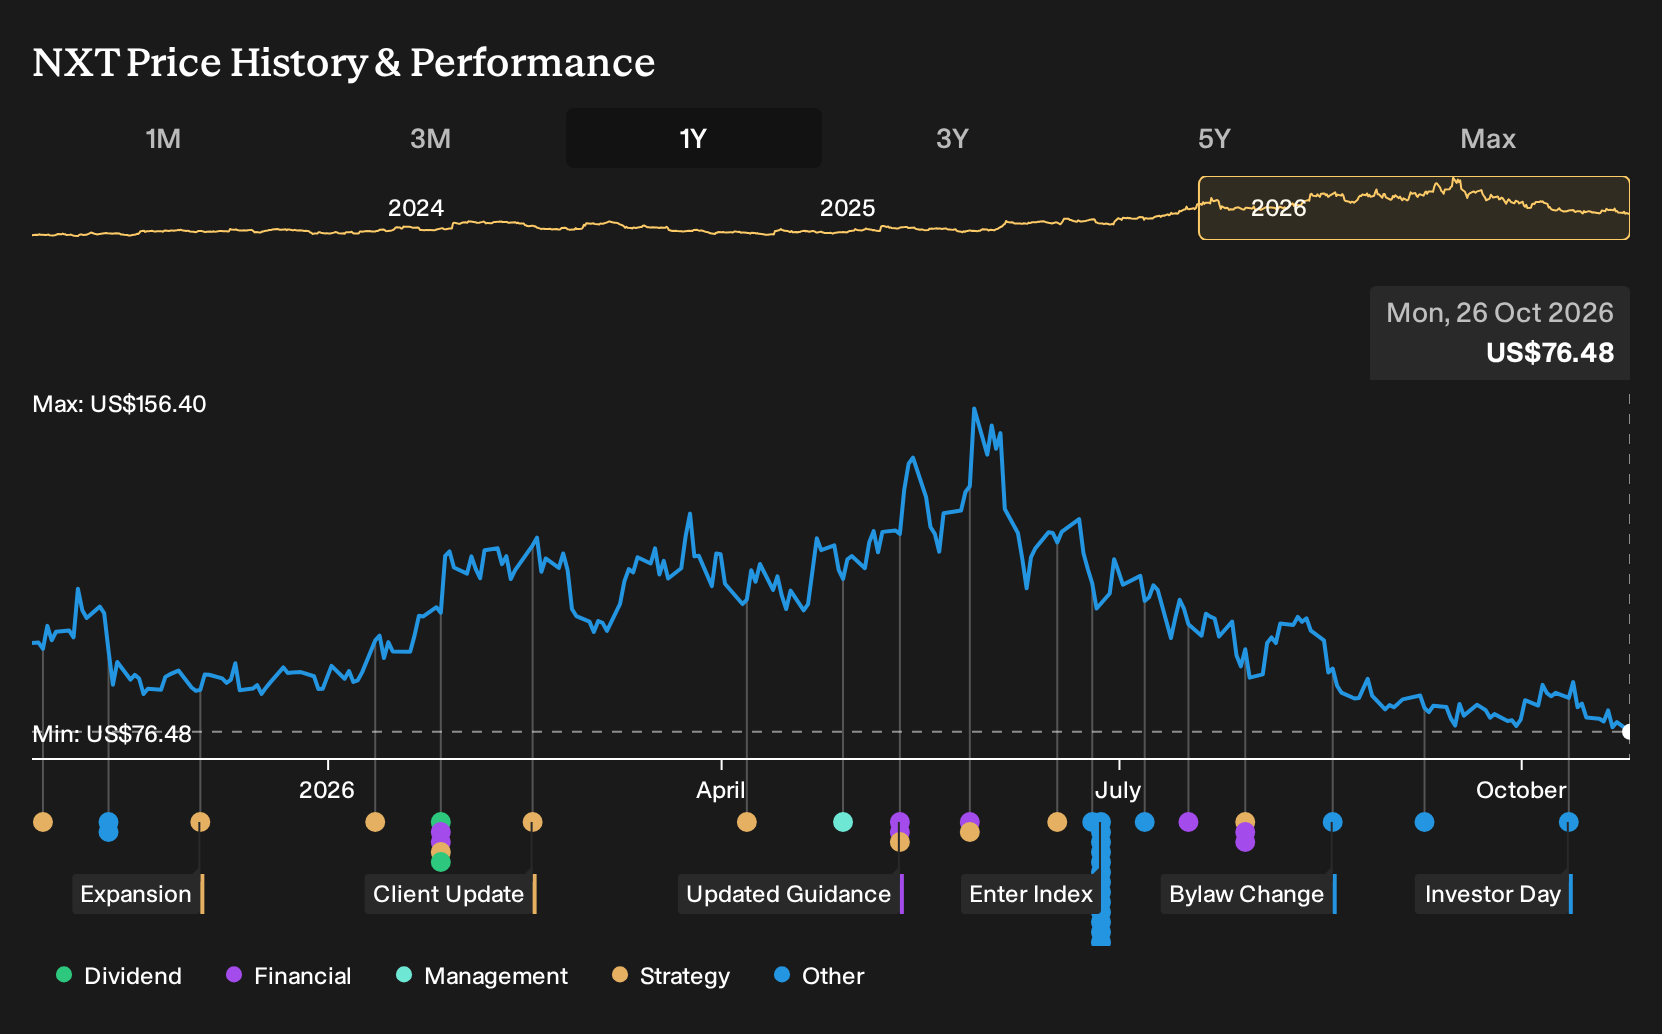
Uncover why Nextpower's fair value points to a 76% potential upside to its current price, which could narrow quickly if Q3 cash delivery impresses.
Exploring Other Perspectives
Some of the most optimistic analysts frame Q3 as a potential proof point for Nextpower’s acquisition and storage story. They were penciling in revenue climbing toward US$7.1b and earnings of about US$1.1b by 2029, versus more cautious peers nearer US$811.9m. You can treat Wednesday’s update as a checkpoint on which camp adjusts first.
Explore 4 other Nextpower fair value estimates, including one that suggests potential upside of up to 129% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so rely on your own judgment.
- A great starting point for your Nextpower research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nextpower. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nextpower's overall financial health at a glance.
Looking For More Investment Ideas Beyond Nextpower?
If you want to stress test your thesis on Nextpower, a smart move is to compare it with other companies that share similar traits, whether that is stronger balance sheets, lower risk profiles, or under followed potential. The Simply Wall St Screener gives you quick ways to line those options up side by side so you can judge which stories actually earn a place in your portfolio.
- For investors who care about resilience first, assess companies with low risk scores through the 30 resilient stocks with low risk scores and see which ones match your comfort level.
- If rock solid finances matter most to you, scan for companies with strong balance sheets and fundamentals using the list of solid balance sheet and fundamentals (24 results) to identify candidates that may handle stress better.
- When you want to hunt for opportunities the market may not be focusing on yet, tap into a curated 21 high quality undiscovered gems that highlights lesser known businesses with solid underpinnings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com