


EN
Stronger Quarterly Earnings Could Be A Game Changer For Old Second Bancorp (OSBC)
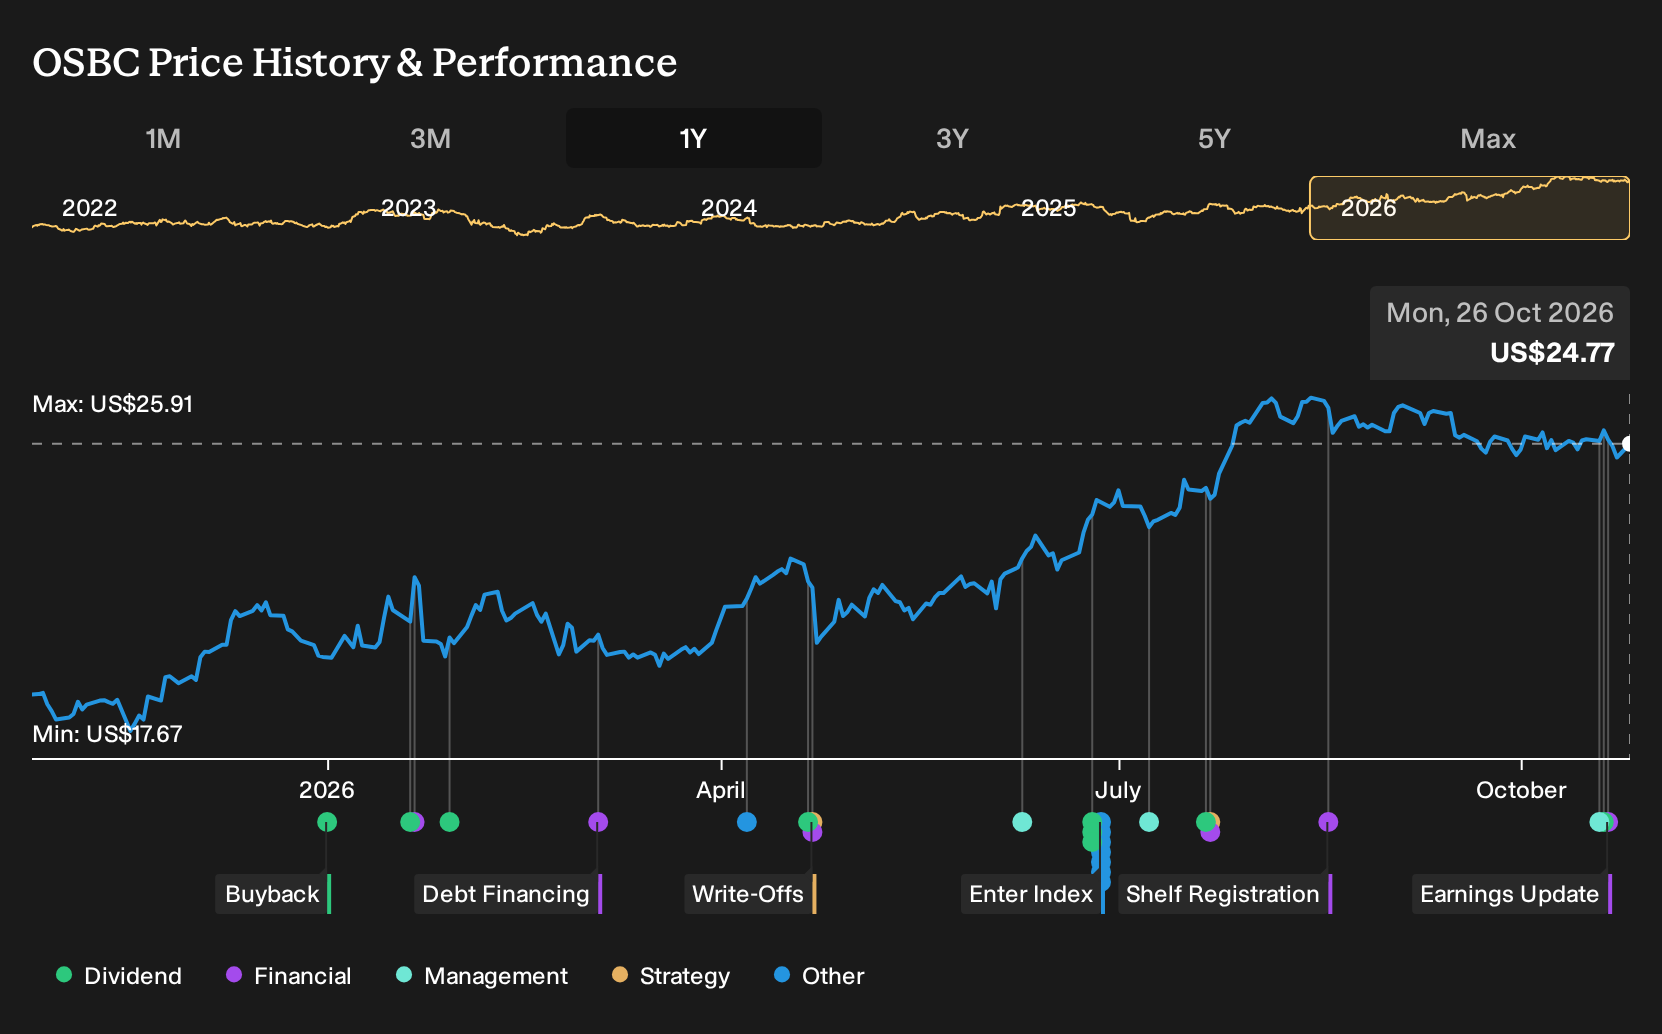
- Old Second Bancorp reported third quarter 2026 net interest income of US$84.05 million and net income of US$28.94 million, with basic earnings per share from continuing operations of US$0.57 and a completed 3.01% share buyback, alongside an US$0.08 per share dividend declared in October.
- The combination of higher quarterly earnings, active repurchases totaling US$39.5 million and a continuing cash dividend indicates management emphasis on per share value and disciplined capital return at Old Second Bancorp.
- We will now see how Old Second Bancorp's investment narrative is affected by the sharp year over year jump in quarterly earnings.
Old Second Bancorp Investment Narrative Recap
For Old Second Bancorp, the core belief is that a high net interest margin and specialty lending can keep supporting earnings, even while credit costs stay elevated. The sharp jump in quarterly profit and higher earnings per share reinforce that income generation is currently holding up. The near term catalyst remains the business proving it can sustain this profitability while managing charge offs tied to C&I, office CRE and powersports.
The biggest risk still sits in those credit costs, which could eat into net interest income if loss trends do not ease. Recent results do not remove that risk, but they provide fresher data on how the loan book behaves under pressure. The operating story now depends on whether management can keep balancing yield and discipline without letting earnings quality slip.
The most relevant update around this earnings release is the completed US$39.5 million buyback, covering 1,533,104 shares or 3.01% of the float. Combined with higher quarterly earnings, that capital return gives per share metrics an extra lift and ties directly into the existing catalyst that revolves around Old Second Bancorp converting its margin profile into stronger per share results.
This repurchase sits alongside a regular dividend and an existing authorization framework, so it matters for how you think about capital deployment versus balance sheet resilience. For a story that already leans on net interest margin and specialty lending yield, the key question is whether this level of buybacks can continue without constraining flexibility if credit losses, funding pressure or local Illinois conditions worsen from here.
Old Second Bancorp's narrative references analyst expectations for US$357.0 million in revenue and US$138.4 million in earnings by 2029. This reflects forecast annual top line growth of 1.5% and an earnings increase of about US$46.0 million from the current US$92.4 million base.
Uncover why Old Second Bancorp's fair value indicates a 13% potential upside to its current price, a discount that may not last much longer.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Old Second Bancorp research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Old Second Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Old Second Bancorp's overall financial health at a glance.
Looking for more investment ideas beyond Old Second Bancorp?
If the Old Second Bancorp story has you thinking about income, quality and risk in a fresh way, use that same lens to scan the wider market with the Simply Wall St Screener.
- For investors who want yield with resilience, start by reviewing a curated set of potential income opportunities through 5 dividend fortresses.
- If value and balance sheet strength matter most to you, filter for financially robust companies via the list of solid balance sheet and fundamentals (24 results).
- When you want to hunt for less followed opportunities with strong fundamentals, cast the net wider using our 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com