


EN
Did AI Product Push Just Shift NetApp (NTAP) Stock's Investment Narrative?
- Guggenheim recently initiated coverage on NetApp with a Neutral rating, highlighting new AI oriented products and the company’s ability to pass through higher component costs as key factors for future revenue potential.
- The focus on AI centric storage and data infrastructure points to management leaning into workloads where performance, scale and pricing power can matter most for NetApp’s underlying earnings quality.
- This analysis now explores how NetApp's investment narrative could evolve as new AI focused offerings become a larger driver of demand.
Scan how NetApp’s AI focused storage story compares with other potential breakout plays across 55 AI infrastructure stocks in the data and compute backbone of the AI buildout.
NetApp Investment Narrative Recap
To own NetApp, you need to believe its AI oriented storage, cloud services and higher value software can keep absorbing more of enterprise data workloads while margins hold up against rising component costs. The recent Guggenheim initiation reinforces that AI is central to the story but does not change the operational priority, which is turning hundreds of AI and data lake deals into recurring, high quality revenue.
In the near term, the key catalyst is continued adoption of AI and analytics projects moving from proofs of concept into production on NetApp infrastructure. The biggest risk remains pressure on product gross margin from memory and component costs, especially with inventory already higher and hardware valuations flagged by at least one broker as stretched, which could magnify any sentiment swing.
The most relevant operational thread tied to this Guggenheim call is NetApp’s push into AI ready storage, including offerings such as Novus for large AI factories and the pending PEAK:AIO acquisition. These initiatives sit in the area investors are watching, at the intersection of high performance infrastructure needs and the company’s ability to justify pricing power.
For you as a shareholder, the question is whether NetApp can execute on that AI focused roadmap quickly enough to support its margin profile while integrating acquisitions such as PEAK:AIO and earlier deals such as DataPelago and JetStream. Successful execution would mean AI and subscription style services take a larger share of the mix, while any stumble on integration, demand absorption or pricing could expose the business to both earnings pressure and sharper scrutiny of the current valuation.
NetApp's narrative points to forecast revenue of US$9.5b and earnings of US$1.9b by 2029. This implies revenue growing at 8.6% per year and an earnings increase of about US$0.5b from US$1.4b today.
Uncover how NetApp's fair value indicates a 5% potential downside to its current price, suggesting that this premium may not be sustainable.
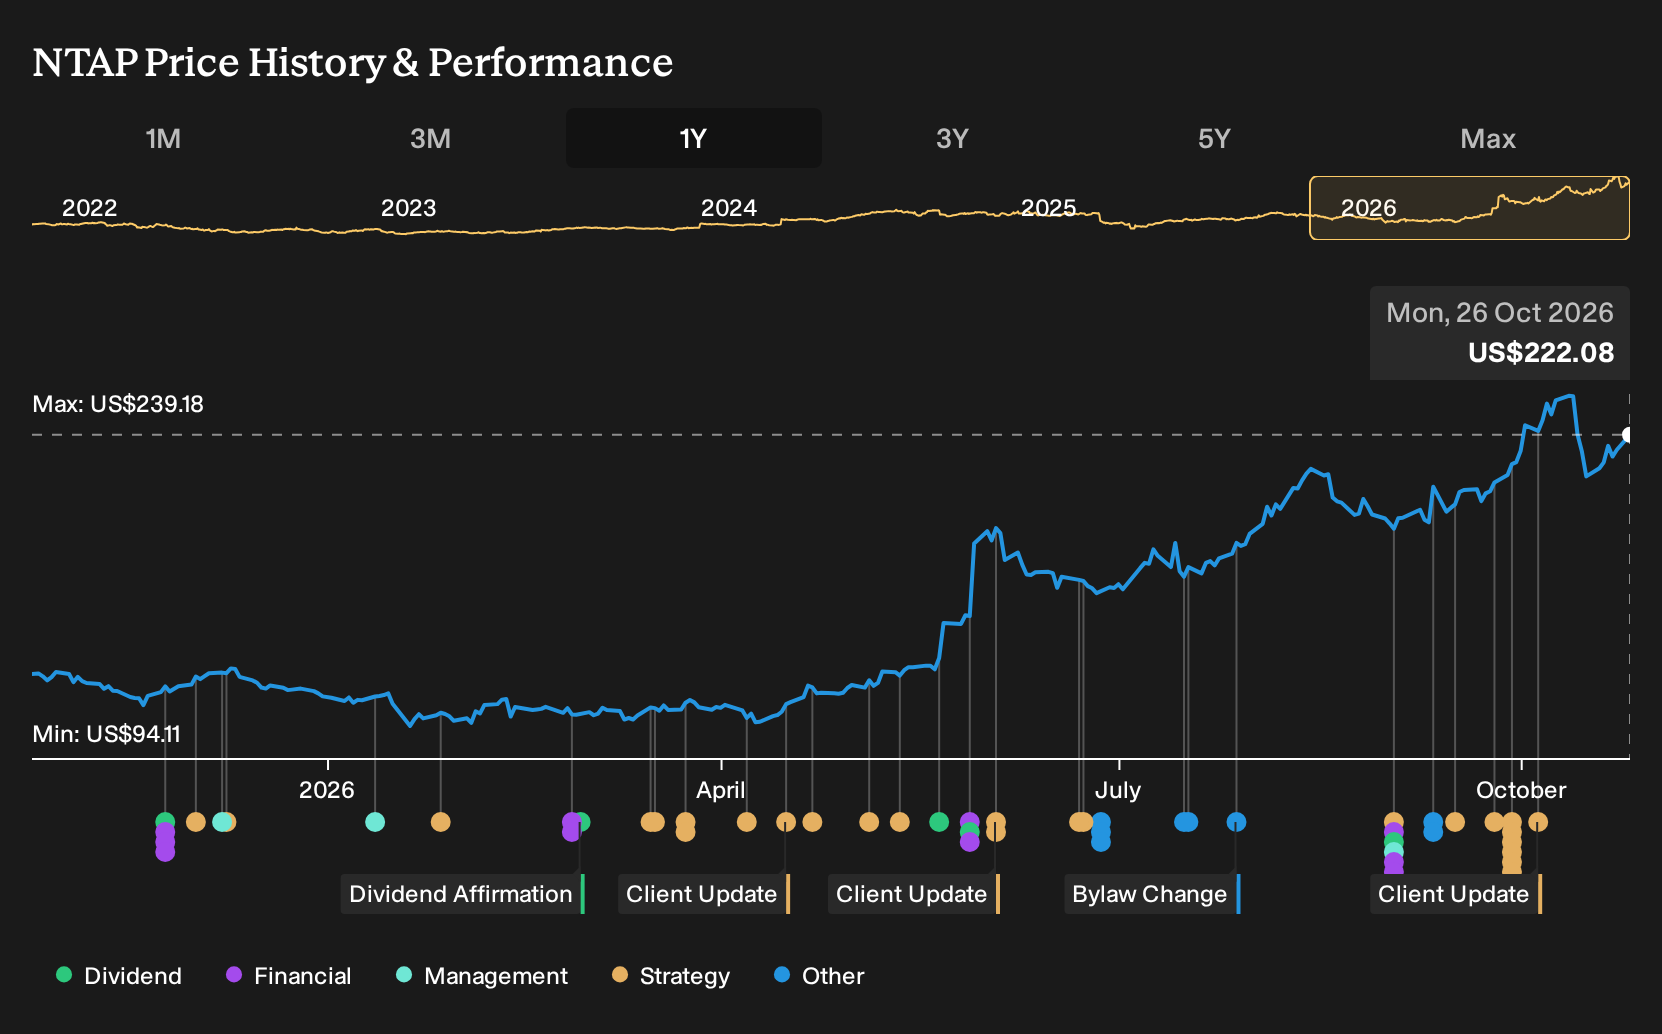
Exploring Other Perspectives
You can also consider a more optimistic angle on NetApp that focuses on AI demand as a key catalyst. The most bullish analysts, before this Guggenheim call, were working with projections of revenue reaching about US$10.4b and earnings near US$2.1b by 2029. That presents an entirely different story, and it may shift again as new information becomes available.
Explore 3 other NetApp fair value estimates, including one that suggests up to a 10% increase from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your NetApp research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NetApp. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate NetApp's overall financial health at a glance.
Looking For More Investment Ideas Beyond NetApp?
If the NetApp story has sharpened your thinking on AI infrastructure, it can help to widen the lens and compare it with other opportunities that fit different risk and income preferences.
- For investors who want potential upside without stretching quality too far, scan a curated group of smaller companies through the 7 elite penny stocks with strong financials that already show stronger financial traits than most in their bracket.
- If capital preservation matters more than chasing the fastest mover, focus on steadier performers using a 30 resilient stocks with low risk scores that filters for businesses with more resilient profiles and fewer red flags.
- When balance sheet strength is a priority, build a watchlist from the list of solid balance sheet and fundamentals (24 results) to see which companies pair financial stability with fundamental support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com