


EN
Watsco (WSO) Could Be 21% Undervalued As New $750 Million Credit Line Adds Flexibility
Watsco (WSO) has arranged a new US$750 million unsecured revolving credit facility, extending its existing line and repaying US$69.7 million of prior borrowings to reset its financing setup.
Recent trading has been choppy. Watsco’s share price is down 5.46% over the last day and 16.92% over 90 days, with a 12.09% decline year to date. The 5 year total shareholder return of 20% points to more modest longer term gains.
Pace your risk by pairing Watsco with a curated group of industrial distributors and building-related businesses screened for balance sheet strength and fundamentals using our list of solid balance sheet and fundamentals (24 results).After a sharp pullback and a fresh credit line in place, Watsco sits at an interesting crossroads. Is most of the easy upside already spent, or do the current terms still leave meaningful value on the table?
Most Popular Narrative: 17% Undervalued
Against a last close of $305.33, the most widely followed narrative puts Watsco’s fair value at $369.90. This points to a material gap that depends on how its technology and margin story develops over time.
The main thing that has to go right is that Watsco converts its heavy ongoing technology spend and growing e-commerce and OnCall Air usage into sustained gross margin progress toward its stated 30% target while managing OEM pricing and regulatory shifts.
See why 14 investors see Watsco as 17% undervalued.
Result: Fair Value of $369.90 (UNDERVALUED)
Still, the story can crack if gross margins stay under pressure from OEM pricing and A2L related costs, or if international tariffs hit that 9% overseas revenue slice.
Find out about the key risks to this Watsco narrative.
Another View: What Multiples Say About Watsco
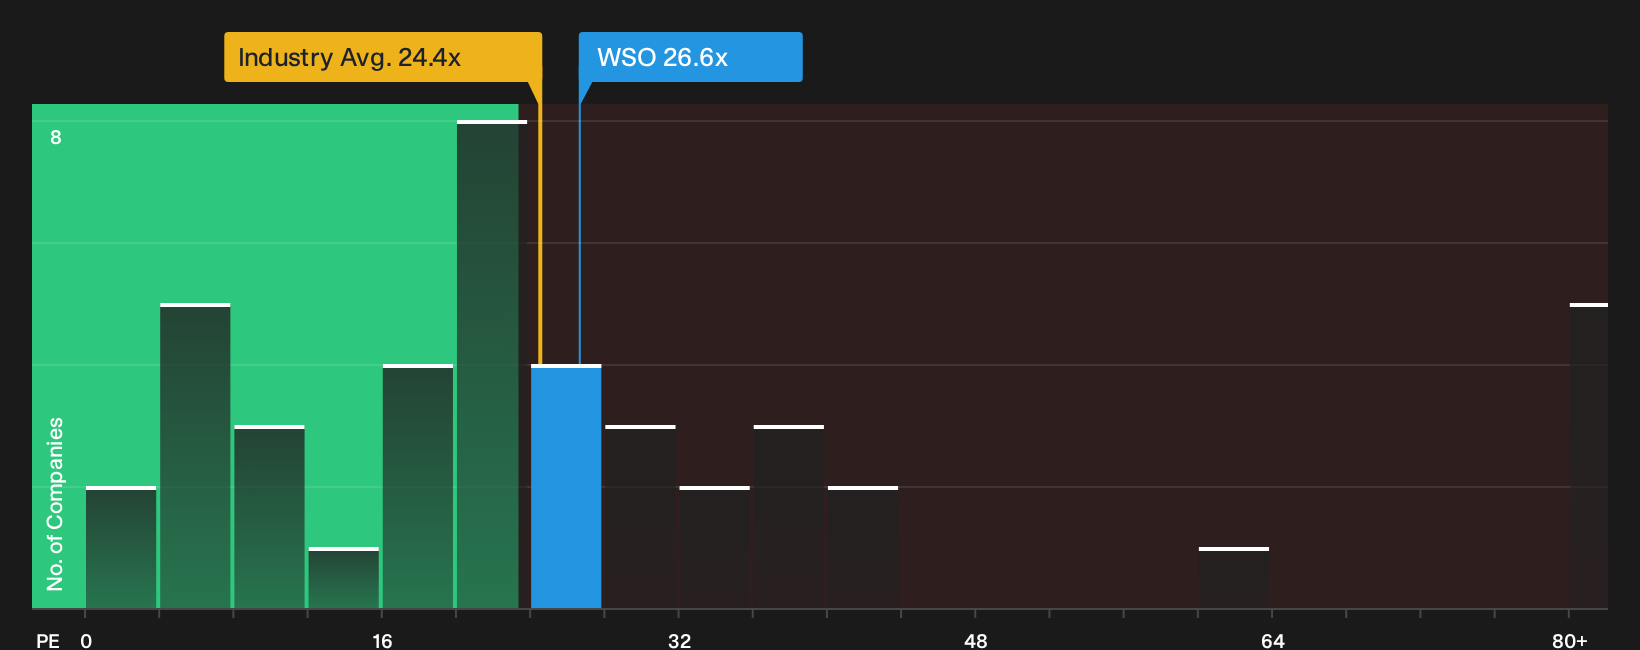
There is a catch. While the SWS model points to Watsco trading below fair value, the current P/E of 26.6x sits above the US Trade Distributors industry on 24.4x, the peer group on 24.5x, and the fair ratio at 25.2x.
That gap means investors are already paying a premium for the shares, even as the narrative leans on margin recovery and technology execution. The question is whether that extra multiple feels like a buffer or a pressure point for your own thesis. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in this piece has been mixed, and that tension is exactly where careful investors usually do their best work, so move quickly and weigh both sides with the help of 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Watsco?
If you stop with Watsco alone, you risk missing other setups where price, quality, and balance sheet strength line up in your favor.
- Target potential bargains by scanning for quality businesses trading below what their cash flows and fundamentals might justify through the 29 high quality undervalued stocks.
- Strengthen income potential by focusing on companies with robust payouts and resilient profiles using the 5 dividend fortresses.
- Dial down portfolio stress by concentrating on financially sturdy businesses screened via the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com