


EN
Sandvik (OM:SAND) Earnings Beat Raises The Question Of Whether The Stock Is Fully Valued
What Sandvik’s latest earnings release tells you
Sandvik (OM:SAND) just posted third quarter and nine month results for 2026, with higher reported sales, net income and earnings per share compared with the same periods a year earlier.
Sandvik’s latest figures arrive after a period in which the share price has slipped 6.8% over the past month but still delivered a 16.7% year-to-date return. The 3-year total shareholder return of 100.2% also points to strong longer-term momentum that recent earnings may help investors reassess.
Scan how Sandvik’s earnings shift compares across the sector by reviewing a curated set of industrial peers in the list of solid balance sheet and fundamentals (207 results).
After strong reported earnings and a recent pullback, Sandvik now trades about 11% below the average analyst target, while some intrinsic value estimates suggest a premium. Is the market’s caution misplaced or already ahead of itself?
Most Popular Narrative: 10% Undervalued
On the most followed view, Sandvik’s fair value of SEK390.90 sits above the last close at SEK352.20. This puts the latest earnings into a pricing gap that investors will want to test against the underlying business mix.
Sandvik is benefiting from strong market momentum in its Mining segment, with order intake for the business reaching over SEK 20b in Q2 2026 and mining aftermarket orders growing double digit for several quarters, which could support future revenue and earnings as high production rates and aging fleets keep driving equipment and service demand.
See why 21 investors see Sandvik as 10% undervalued.
Result: Fair Value of SEK390.90 (UNDERVALUED)
Still, the narrative can break if weakness in Cutting Tools, Infrastructure or Rock Processing persists and keeps Sandvik group margins and cash generation under pressure.
Find out about the key risks to this Sandvik narrative.
Another View on Sandvik’s valuation
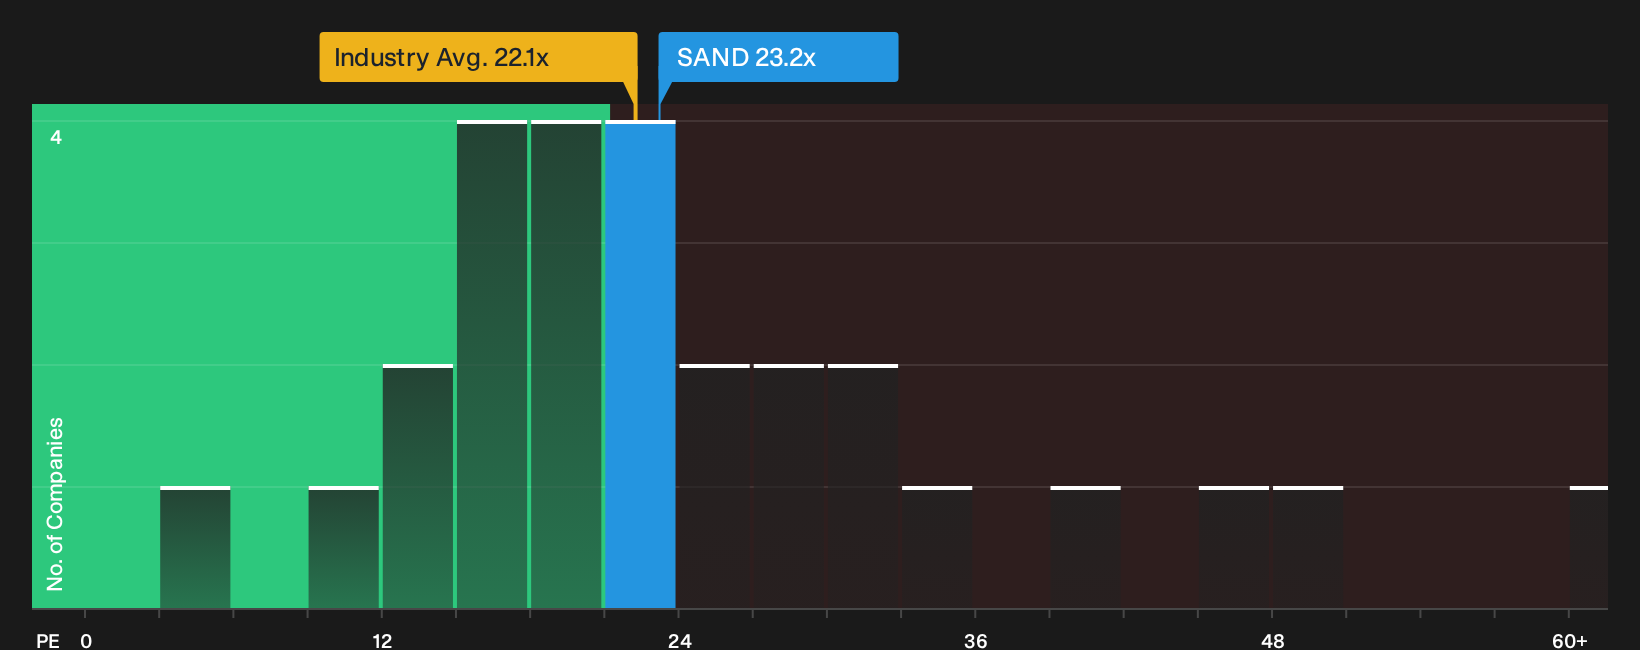
The fair value narrative points to Sandvik trading around 10% below SEK390.90, yet the P/E picture sends a different message. At 23.2x earnings, the stock is richer than the Swedish Machinery industry on 22.1x, even though peer companies average a steeper 26.9x.
The fair ratio of 31.6x suggests the market could still re-rate the shares higher over time. However, the current premium to the local sector means investors are already paying up for quality. The key question is whether Sandvik’s earnings path is strong enough for you to accept that valuation risk.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation and earnings quality often create the most interesting setups, so move fast and review the underlying data yourself before the consensus hardens. To weigh Sandvik’s potential upside against the issues investors are worried about, start with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Sandvik?
If Sandvik has sharpened your interest, now is the moment to broaden your watchlist and line up a few fresh contenders before the next move.
- Target resilient compounding potential by scanning companies with strong finances and clean balance sheets in the list of solid balance sheet and fundamentals (207 results).
- Hunt for value opportunities by reviewing the 195 high quality undervalued stocks that may currently trade below what their fundamentals suggest.
- Prioritise steady cash returns by checking out income ideas in the 224 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com