


EN
Is Coca-Cola Consolidated (COKE) Fairly Valued After Its Run To $208.73?
Coca-Cola Consolidated (COKE) drew investor attention after recent trading left the shares at $208.73, with the stock showing varied short term returns across the past week, month and past 3 months.
The recent 2.67% one day share price gain sits on top of a 9.69% 30 day share price return and a 39.30% year to date share price move. Coca-Cola Consolidated has delivered a 63.76% total shareholder return over one year and very large multi year gains, which together point to momentum that investors are still rewarding.
Scan Coca-Cola Consolidated’s momentum against a curated field of consumer and beverage peers by running your filters through 29 high quality undervalued stocks.
The share price move is already substantial, so buying Coca-Cola Consolidated at $208.73 means paying up for that strength. Does the current valuation still leave enough cushion, or is patience the better trade here?
Price-to-Earnings of 25.3x: Is it justified?
Coca-Cola Consolidated trades on a P/E of 25.3x, which investors are comparing to both its direct peers and the wider beverage universe when deciding if $208.73 is rich or reasonable.
The P/E ratio links the current share price to the most recent earnings per share. For a beverage bottler that generates $7.7b of revenue and $550m of net income, this metric helps you judge how much you are paying for each dollar of profit.
Relative to a peer average P/E of 56.8x, Coca-Cola Consolidated is priced far lower, which suggests the market assigns a much smaller earnings multiple than it does to comparable consumer and beverage stocks. That gap implies investors are either more cautious about this business or more optimistic on peers, despite COKE having high quality earnings and a long profit growth record.
Against the global beverage industry average P/E of 16.6x, the stock is materially more expensive, which shows that on a broader sector view the earnings stream carries a premium tag rather than a discount.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 25.3x (ABOUT RIGHT)
Still, Coca-Cola Consolidated relies heavily on the broader Coca-Cola system and U.S. consumer demand, so any contract changes or weaker volumes could quickly challenge this momentum story.
Find out about the key risks to this Coca-Cola Consolidated narrative.
Another view on Coca-Cola Consolidated’s value
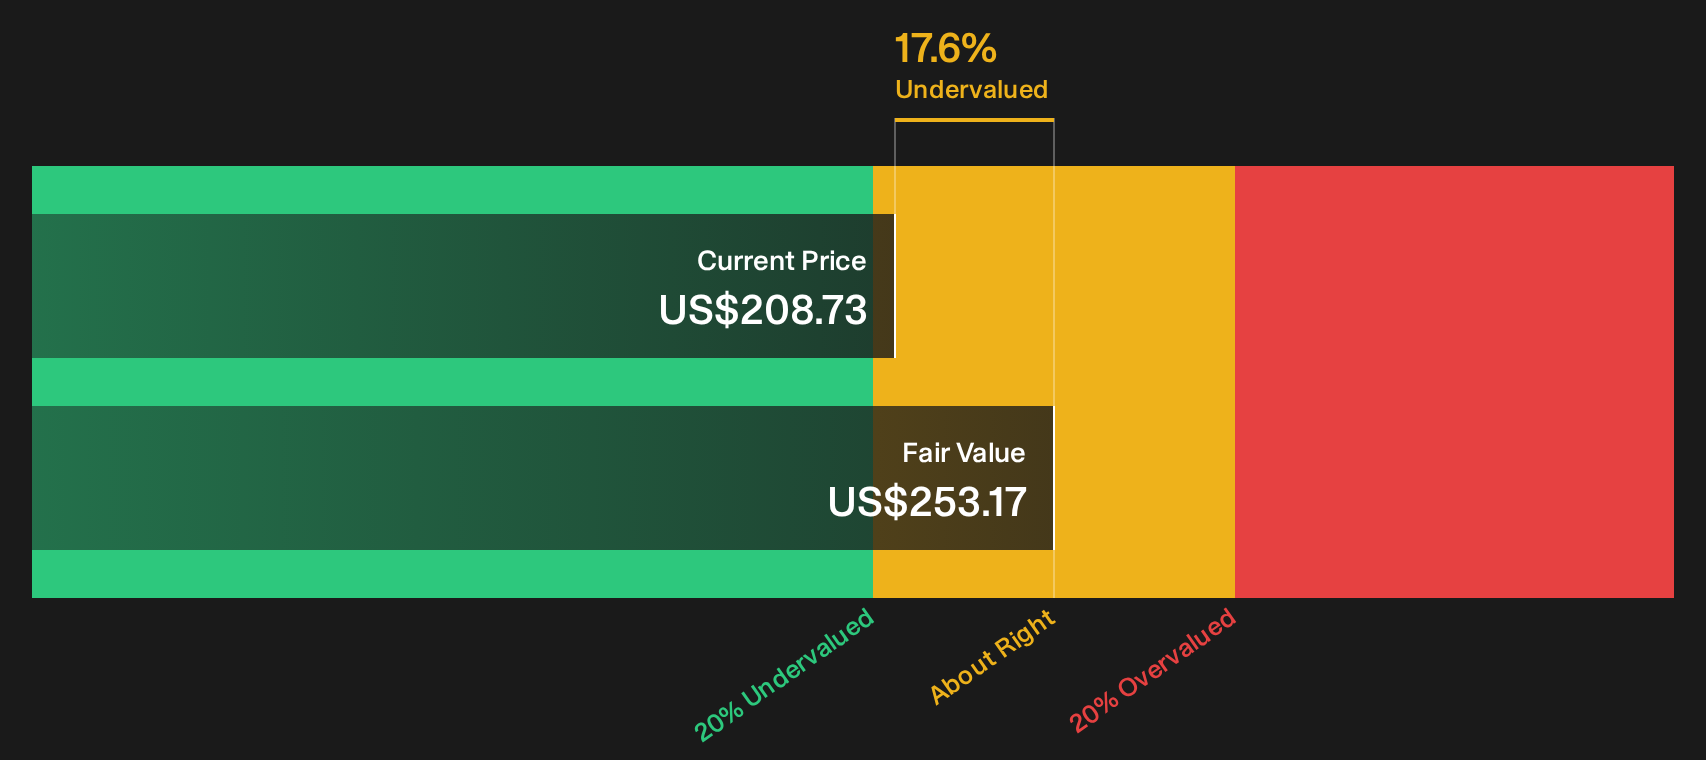
The first check used the 25.3x P/E to judge whether Coca-Cola Consolidated looks fairly priced. A different lens, our DCF model, compares the $208.73 share price to an estimated future cash flow value of $253.17, which points to the stock trading below that cash flow estimate.
This gap suggests investors are paying less than that modeled stream of future dollars right now. The same move could also reflect concern about high debt, negative equity and pressure on recent profit margins. Which story do you think the market is really pricing in: a mispriced cash flow stream or a fair discount for balance sheet risk?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Coca-Cola Consolidated for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Coca-Cola Consolidated’s valuation and risk profile are clear, so move quickly, review the underlying data, and shape your own judgment by weighing the 1 key reward and 2 important warning signs.
Looking for more Coca-Cola Consolidated investment ideas?
If Coca-Cola Consolidated has sharpened your focus on valuation and quality, do not stop there. The broader market still holds plenty of candidates worth your attention.
- Upgrade your opportunity set by scanning a 21 high quality undiscovered gems that pairs strong fundamentals with stocks the crowd has not focused on yet.
- Stack your watchlist with sturdier names by filtering for a list of solid balance sheet and fundamentals (24 results) so potential ideas start from a position of financial strength.
- Tilt toward resilience by screening for 30 resilient stocks with low risk scores where business quality and lower risk scores keep downside firmly on your radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com