


EN
Is Affirm Holdings (AFRM) Undervalued On Its Sam’s Club Deal Or Already Priced In?
Affirm Holdings (AFRM) just announced an exclusive multi-year collaboration with Sam’s Club, giving eligible shoppers a fixed payment schedule for online purchases and planned in-store access beginning in 2027.
Against that backdrop, Affirm Holdings has seen momentum cool, with the share price down 4.6% over the past week and 6.1% year to date. The 1-year total shareholder return has declined 9.1% but remains far behind a very large 3-year total shareholder return gain.
Scan beyond Affirm Holdings and see how other payment and fintech players are setting up for their next move with our hand picked 29 high quality undervalued stocks.
Affirm Holdings has pulled back even as it lines up new partners and posts a very large 3-year total return. Are you looking at a story where most of the payoff already happened, or one where meaningful upside still lies ahead on valuation?
Most Popular Narrative: 30% Undervalued
On the most followed view of Affirm Holdings, a fair value of $99.23 sits well above the last close at $69.49, which sets up a bullish valuation gap built on growth, margins, and discount rate assumptions.
Adoption by a growing base of merchants and consumers, combined with expansion into new geographies (notably the imminent U.K. entry via Shopify), positions Affirm to capture larger volumes as e-commerce and embedded finance become increasingly central to global retail, likely driving top-line revenue growth.
Affirm's differentiated technology and underwriting (evidenced by the success with 0% APR loans and high user repeat rates) should improve customer lifetime value and reduce credit losses, supporting enhanced net margins and sustained earnings as more users graduate to interest-bearing products.
See why 53 investors see Affirm Holdings as 30% undervalued.
Result: Fair Value of $99.23 (UNDERVALUED)
Still, the loss of a major merchant partner and rising competition in Buy Now, Pay Later could pressure Affirm Holdings if volumes or unit economics weaken.
Find out about the key risks to this Affirm Holdings narrative.
Another View: DCF Points The Other Way
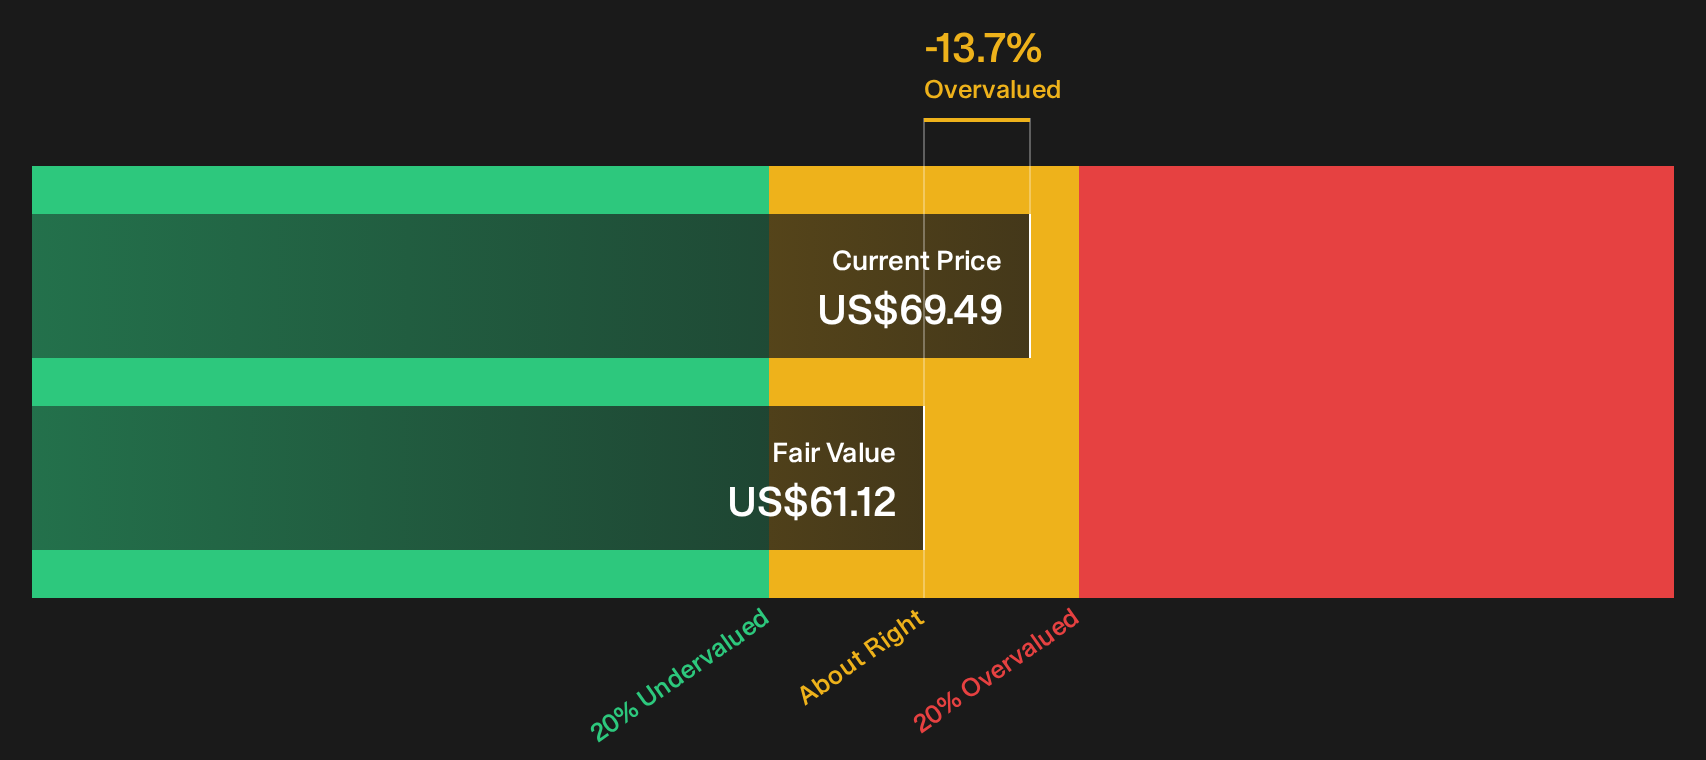
The market is treating Affirm Holdings very differently depending on the lens you use. On the one hand, analyst fair value of $99.23 implies upside. On the other, our DCF model puts future cash flow value at $61.12, which is below the current $69.49 share price and frames the stock as overvalued on this method. Which picture do you trust more for your own process?
To understand why the cash flow view diverges from the analyst target and what that means for risk, pricing and expectations, take a closer look at how the SWS DCF model is built into the fair value work.Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Affirm Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages across Affirm Holdings can make the story feel murky, so move fast, dig into the data yourself, and test both the enthusiasm and the caution by weighing the 5 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Affirm Holdings?
If Affirm Holdings has you thinking harder about risk, reward, and timing, use that momentum and scan a few focused shortlists that surface different angles on potential opportunities.
- Target resilience first and review a 30 resilient stocks with low risk scores that highlights businesses with more measured risk profiles when market narratives swing quickly.
- Hunt for quality at a discount and assess a curated 21 high quality undiscovered gems before other investors start paying attention to the same fundamentals.
- Prioritise financial staying power and sort through a list of solid balance sheet and fundamentals (24 results) where stronger balance sheets can help support operations through tougher periods.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com