


EN
What Yakult HonshaLtd Doubters Missed
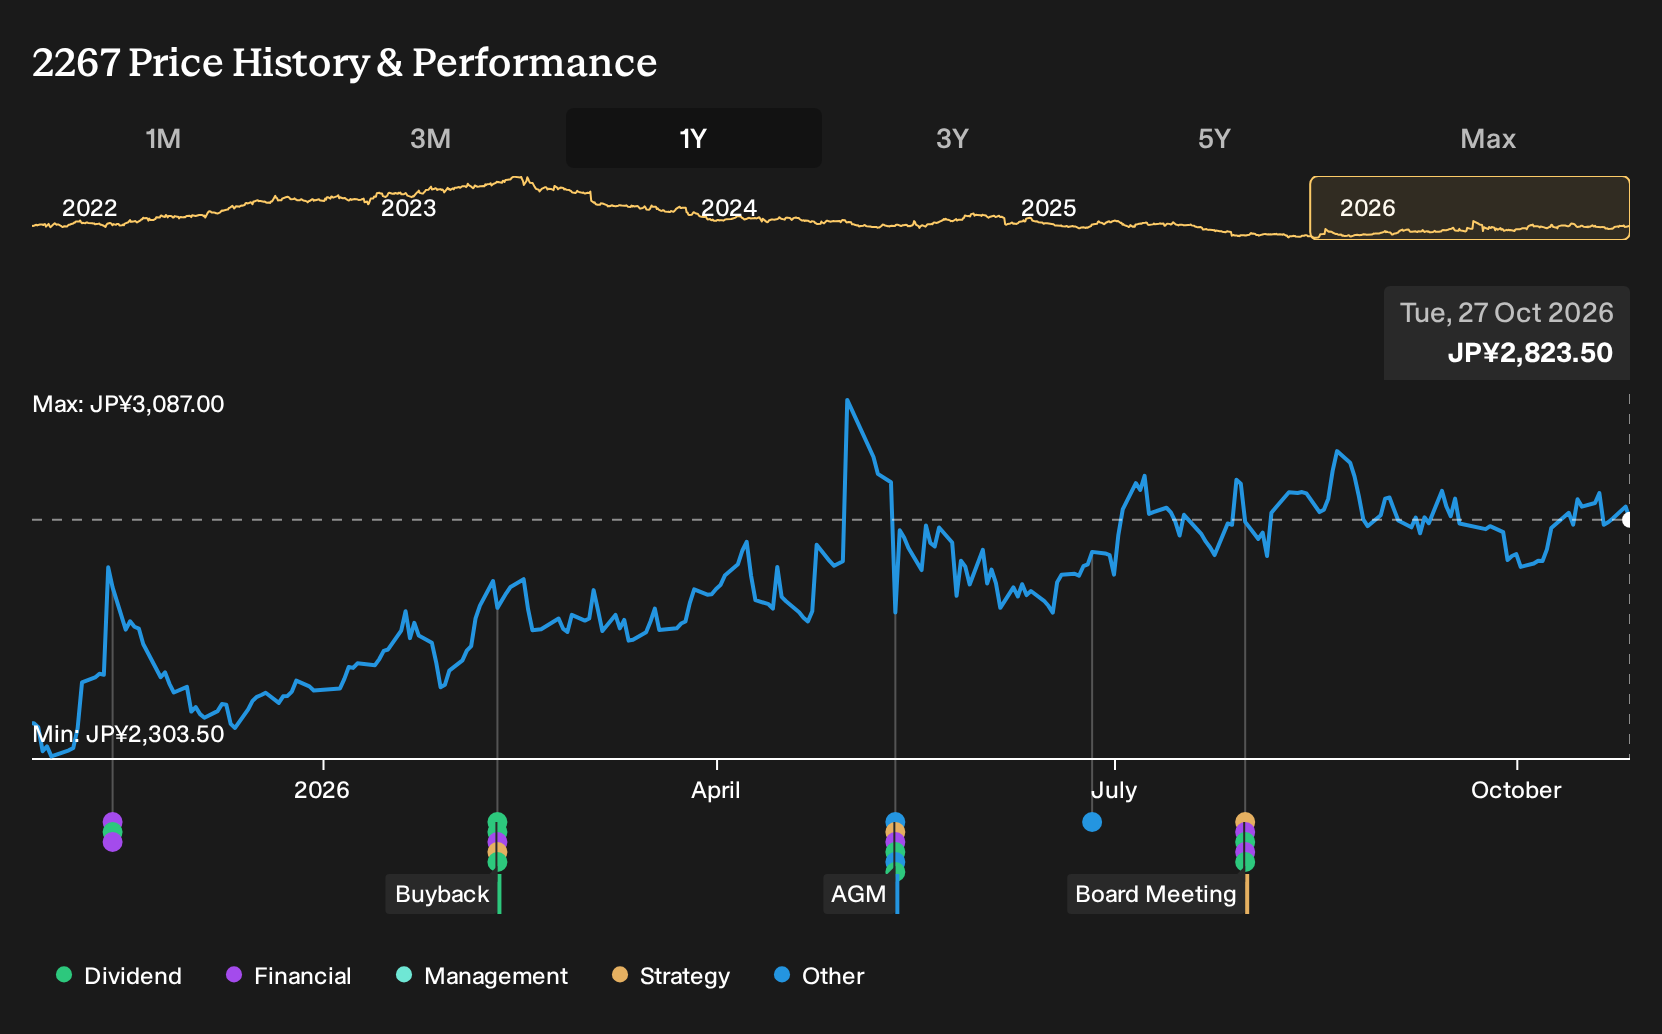
If you only glanced at Yakult HonshaLtd’s headlines this year, a softer domestic backdrop and regulatory worries might not sound like the recipe for a rewarding hold. Investors who held Yakult HonshaLtd over the past year are up 22.5%, including dividends. If you had to decide back on 27 October 2025, would that outcome have looked remotely plausible, given the split between bullish expansion hopes and bearish regulatory and environmental concerns?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Yakult HonshaLtd. Zero in on 16 high quality undervalued stocks for companies trading below our estimates.
The Argument Yakult Honsha Investors Faced Back Then
The shares cost ¥2,376 at the start of the period, and anyone looking at Yakult Honsha had to choose between two very different stories. Each side anchored on its own Fair Value and a distinct view of how the probiotic drink maker would handle the next few years.
The bullish Narrative put Fair Value at ¥2,609, 10% above the start price, and leaned on expansion in emerging Asian markets. That camp focused on Yakult Honsha tapping double digit sales volume growth in places like Vietnam alongside a revenue growth assumption of 1.5% and a profit margin of 8.9%.
The bearish view set Fair Value at ¥2,050, 14% below the start price, and worried about regulation and packaging. Stricter oversight of health claims and sugar content plus growing pressure on Yakult’s small plastic bottle were seen as serious risks that could require costly reformulation and changes to core packaging.
What The Results Changed For Yakult Honsha
The clearest new data point was Yakult Honsha’s Q1 2027 update. Total revenue increased from ¥116,586m in Q1 2026 to ¥120,463m in Q1 2027, while net income rose from ¥11,597m to ¥13,591m and net margin widened from 9.9% to 11.3%. Taken together, these figures supported the more optimistic view on profitability rather than the more cautious perspective.
The lesson is simple. When a story depends on margin pressure or relief, track net margin alongside sales and earnings, and then check whether each new report moves that percentage toward or away from the original assumption.
What Yakult Honsha's Price Now Asks You To Believe
Yakult HonshaLtd now trades at ¥2,824, leaving this Narrative's Fair Value below the current market level based on its own assumptions rather than a settled fact.
That Narrative leans on Japan weakness, rising input costs and heavier reliance on overseas earnings. A buyer today effectively bets on smooth overseas expansion, so how does that sit with the risk that domestic stagnation and cost pressure keep squeezing profit resilience?
"Although Yakult HonshaLtd is seeing volume growth in Asia and Oceania, the sharp split between weak Japan Food and Beverages revenue and higher overseas profits, together with management’s own acknowledgement of stagnation in the domestic business, raises the risk that future consolidated revenue increasingly relies on markets that can be pulled back quickly by currency moves and local disruption."
One Narrative disagrees with today's price. → See where this Narrative says Yakult HonshaLtd should trade
Before The Next Story Makes Headlines
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 36% below our estimate - builds AI hiring and local services engines that monetize higher quality matches.
- Company 2 - 50% below our estimate - shifts intensive AI and cloud spending into subscription security platforms with recurring contracts.
- Company 3 - 23% below our estimate - adds maintenance-focused sales teams to win elevator service contracts and densify existing routes.
Three companies from the same screener. Open every one of the 23 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com