


EN
Bittium Stock In Focus After Sales And Transformation Leadership Appointments
- Bittium Oyj has reshaped its leadership by appointing Markku Toiviainen as Chief Sales Officer for Defence & Security and Erik Ahnger as Chief Strategy and Transformation Officer, with both roles effective from 1 November 2026 and reporting to CEO Petri Toljamo.
- The expanded Group Leadership Team concentrates commercial execution and corporate strategy under experienced high tech operators. This is relevant for how Bittium converts its Defence & Security order book, manages organisational change and aligns sales processes with its longer term growth plans.
- This article reviews how Bittium Oyj's investment narrative is affected as Markku Toiviainen takes charge of Defence & Security sales.
Scan how Bittium Oyj's leadership reshuffle compares with peers by reviewing a curated set of defence and security suppliers in the 223 resilient stocks with low risk scores.
Bittium Oyj Investment Narrative Recap
Bittium Oyj appeals to investors who believe the enlarged Defence & Security order book can be turned into steady product deliveries, while Medical and Engineering Services add diversification over time. The short term story still revolves around execution on defence contracts, efficient use of capacity and keeping cash generation healthy as volumes shift.
The leadership changes look relevant but not transformational by themselves. A dedicated Chief Sales Officer for Defence & Security tightens focus on converting orders, which touches the key near term catalyst. The biggest operational risk remains Engineering Services, where a prolonged weak market or slow fix on profitability could weigh on group earnings.
The appointment of Erik Ahnger as Chief Strategy and Transformation Officer is the announcement that most directly ties into Bittium Oyj’s broader catalysts. He now oversees strategy, mergers and acquisitions and the redesign of the operating model, which connects to how the group supports Defence & Security growth while keeping Medical on a profitable track.
For you as a shareholder, this concentrates responsibility for execution risk and opportunity in one role. Outcomes would be reflected in smoother scaling of the €94.2 million Defence & Security order book, better integration of large agreements such as the Indra SDR deal and clearer actions to address the weak Engineering Services segment.
Bittium Oyj Forecasts and Implied Expectations
Bittium Oyj's current analyst story ties directly back to those new leadership roles. The market is being asked to accept a plan where Defence & Security execution, Engineering Services repair work and Medical discipline collectively support a multi year earnings climb.
Bittium Oyj's narrative projects €247.9 million revenue and €45.8 million earnings by 2029. This assumes 22.5% yearly revenue growth and an earnings increase of about €18.5 million from €27.3 million today.
For you as an investor, these figures give a concrete yardstick for judging whether the reshaped leadership team is doing its job. If revenue growth tracks the implied 22.5% pace while earnings move toward €45.8 million, the combination of a dedicated Defence & Security sales lead and a centralised strategy and transformation role will look well aligned with the analyst roadmap.
The same numbers set a clear bar. Should Defence & Security deliveries slow, the Engineering Services recovery stall or Medical margins soften, the gap between the current €27.3 million of earnings and the €45.8 million target could widen, and the leadership changes would be tested against that shortfall.
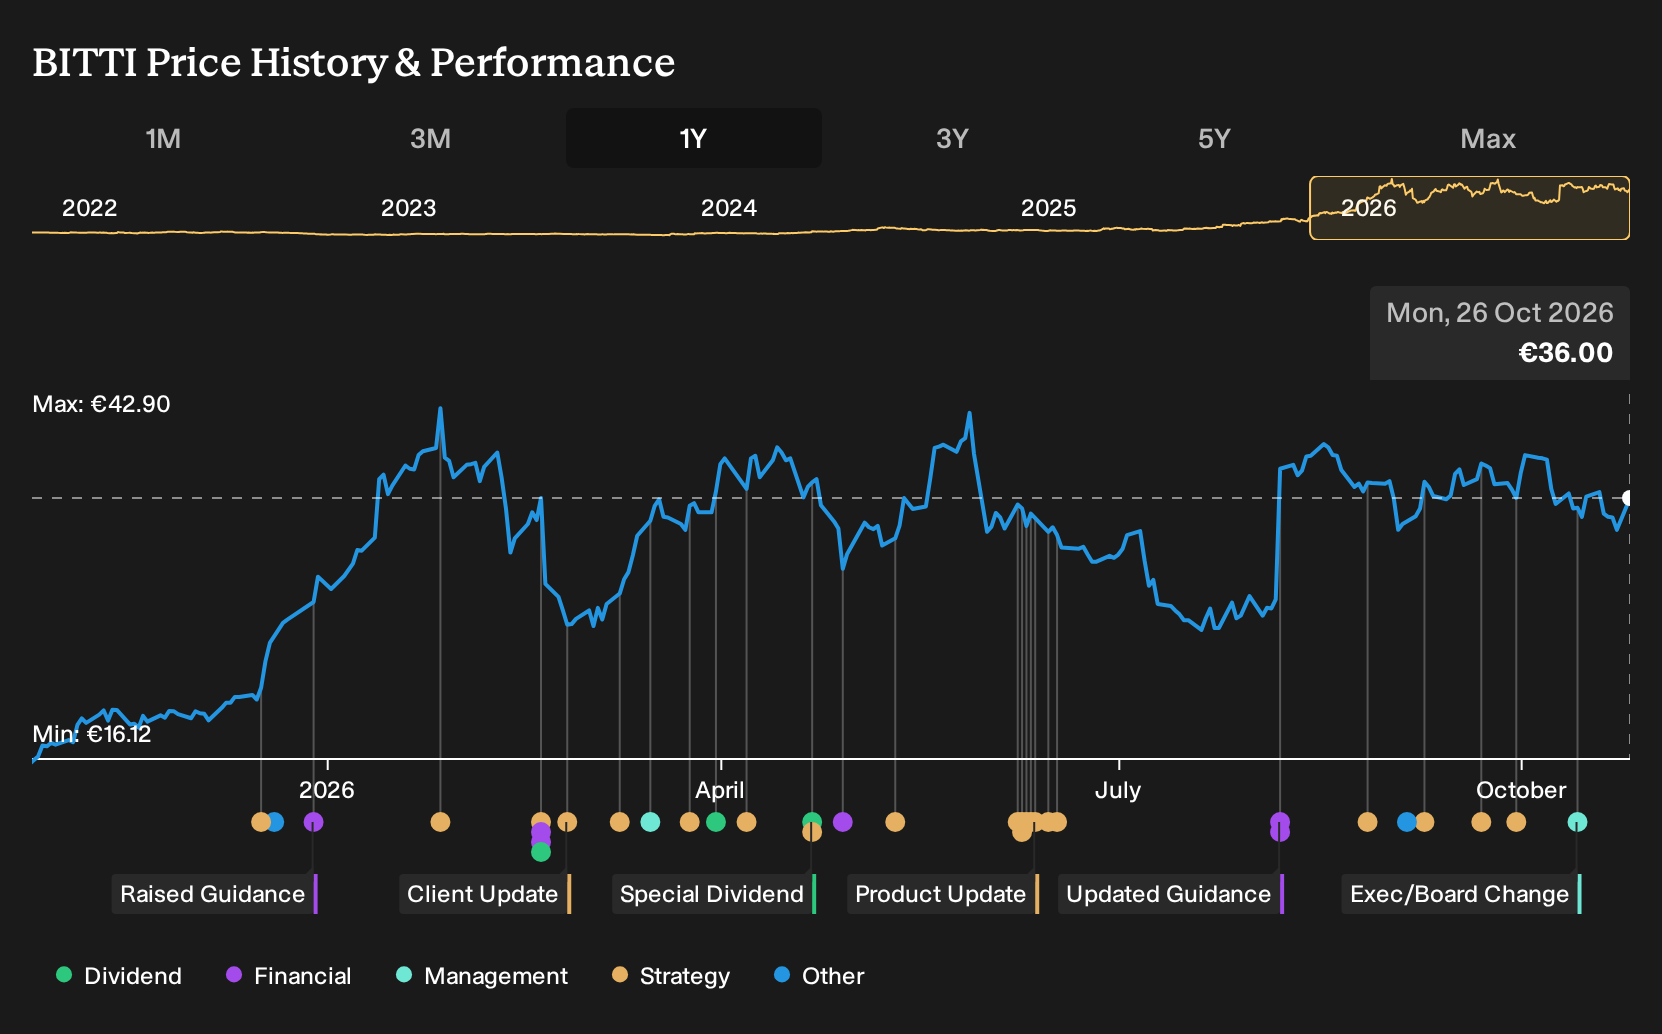
Uncover why Bittium Oyj's fair value indicates a 12% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some analysts lean on a very different focal point for Bittium Oyj. They focus on the risk that Engineering Services stays weak and Tough Mobile 3 delays keep earnings capped, even as leadership changes land. Before this news, the lowest forecasts still pencilled in around €253.4 million revenue and €45.5 million earnings by 2029. That is only slightly under consensus, yet it reflects a view that most of the good news is already priced in. Your own stance can sit anywhere between these stories, so it helps to compare several narratives and see which one fits your expectations best.
Explore 3 other Bittium Oyj fair value estimates, including one that suggests it could be worth just €37.47.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Bittium Oyj research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bittium Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bittium Oyj's overall financial health at a glance.
Looking for more Bittium Oyj style investment ideas?
If the Bittium Oyj story has sharpened your thinking and you want a broader watchlist, the Simply Wall St Screener can help you line up other opportunities that match your risk and return preferences.
- For investors who want quality on sale, consider a curated pool of companies that combine solid fundamentals with appealing valuations through the 195 high quality undervalued stocks.
- If income is a priority, you can focus on businesses that aim to offer substantial yields and sturdier payouts by scanning the 224 dividend fortresses.
- When capital preservation matters most, narrow your search to businesses with stronger balance sheets and more resilient profiles using the 223 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com