


EN
Ora Banda Mining (ASX:OBM) Kicks Off Waihi As Valuation Comes Back Into Focus
Ora Banda Mining (ASX:OBM) has kicked off the Waihi underground project and secured a larger credit facility, a combination that has pushed investors to reassess how its current valuation lines up with earnings potential.
Recent trading has been choppy for Ora Banda Mining, with the 7 day share price return down 9.96% and the 30 day share price return lower by 21.04%, even though the 90 day share price return is up 10.41% and the 1 year total shareholder return remains positive at 4.72%. This is supported by a very large 3 year total shareholder return of more than 7x and a very large 5 year total shareholder return that is more than 15x. The pullback around A$1.22 may reflect investors reassessing execution risk around new projects rather than abandoning the longer term earnings story.
Compare Ora Banda Mining's pullback and project pipeline with other gold producers by scanning our curated list of 35 elite gold producer stocks that are also balancing expansion plans with funding capacity.
After a sharp swing from multiyear gains to a recent pullback at A$1.22, the debate around Ora Banda Mining is simple: Is the meaningful upside still ahead, or has most of it already been earned?
Price-to-Earnings of 10.9x: Is it justified?
Ora Banda Mining now trades on a P/E of 10.9x at a last close of A$1.22, which places the stock slightly above both its industry and peer averages rather than at a clear discount.
The P/E ratio compares what investors are willing to pay today for each dollar of earnings. For a gold producer like Ora Banda Mining, that yardstick often reflects how durable the current profit base looks, how much growth is forecast, and how much risk investors see around project delivery and funding.
Analysts note that Ora Banda Mining is trading at a higher multiple than both the broader Australian Metals and Mining group on 10.6x and a tighter peer set on 8.4x. That premium sits alongside the SWS fair P/E estimate of 19.9x, which suggests the market rating could change if earnings forecasts and perceived risks move closer to that fair ratio level.
Explore the SWS fair ratio for Ora Banda Mining.
Result: Price-to-Earnings of 10.9x (ABOUT RIGHT)
Still, the story around Ora Banda Mining can change quickly if the timing at Waihi slips or if funding costs tighten and squeeze the current earnings base.
Find out about the key risks to this Ora Banda Mining narrative.
Another View: SWS DCF Puts Ora Banda In A Different Light
The P/E of 10.9x paints Ora Banda Mining as roughly in line with its sector, yet the SWS DCF model suggests something very different. At A$1.22, the stock sits well below an estimated future cash flow value of A$13.01, which points to a deep discount if those cash flows materialise.
That kind of gap can signal opportunity, or it can highlight how sensitive the model is to long term assumptions. The real question for investors is whether the Waihi build out and funding mix support those cash flows strongly enough for the market to close any part of that distance.
Look into how the SWS DCF model arrives at its fair value.
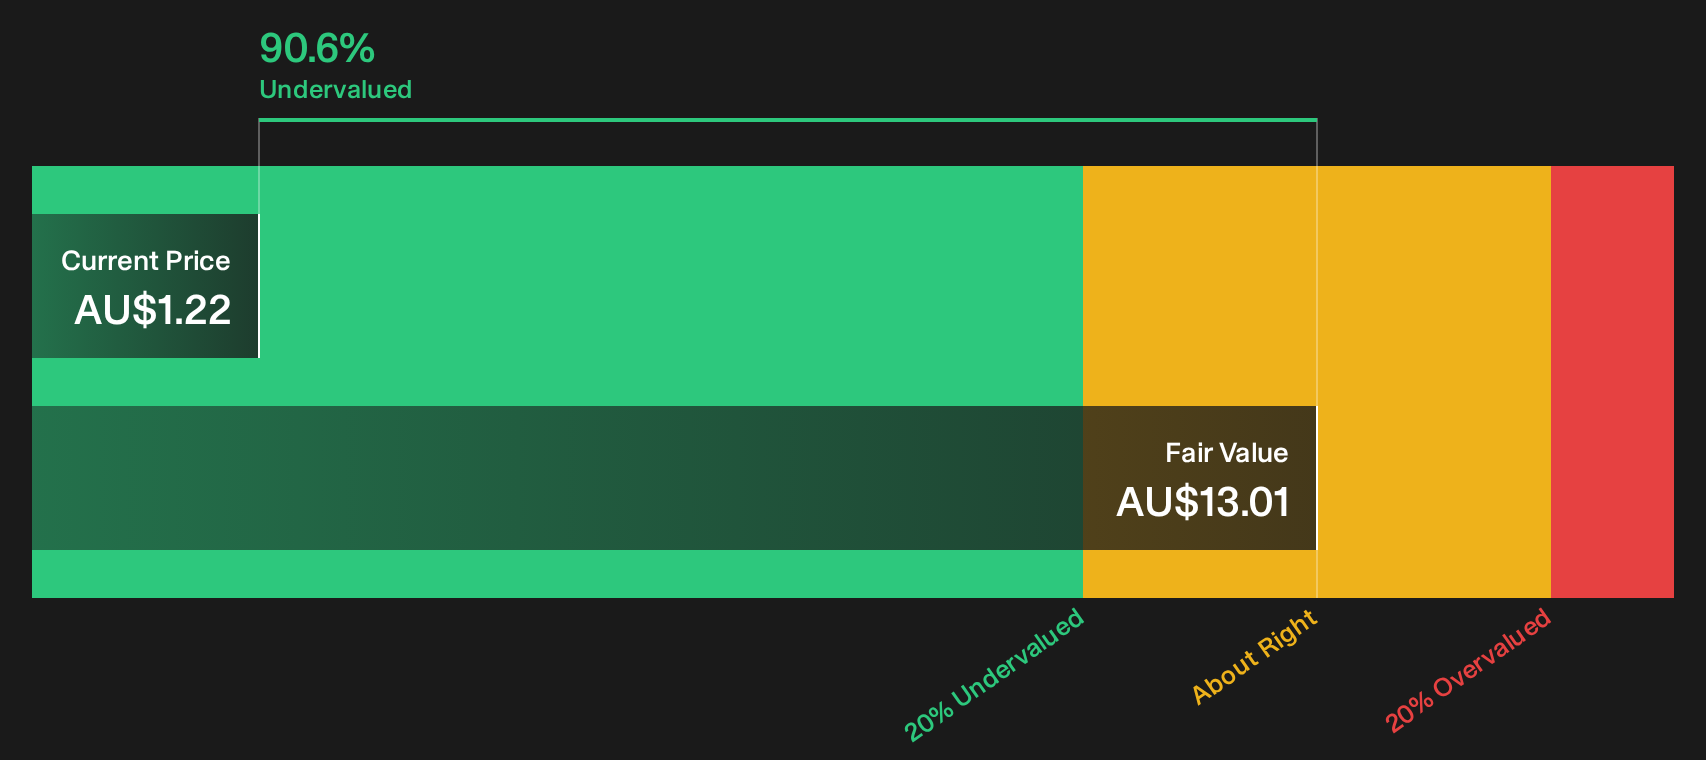
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ora Banda Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 2 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around Ora Banda Mining leave you unsure, that is the point. The next move rests on your assessment of both the upside story and the risk side of the ledger, so weigh the data quickly and then drill into the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Ora Banda Mining?
If Ora Banda Mining has sharpened your focus on valuation and risk, use the Simply Wall St Screener to uncover fresh opportunities that might not be on your radar yet.
- Target potential mispricing by scanning a focused group of 2 high quality undervalued stocks that pair earnings power with quality fundamentals.
- Strengthen portfolio resilience by reviewing a list of solid balance sheet and fundamentals (12 results) that can better handle funding cycles and operational shocks.
- Get ahead of the crowd by searching through 15 high quality undiscovered gems before attention and capital move on to the next theme.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com