


EN
Recurring Services Growth Altering The Investment Case For Currys Stock (LSE:CURY)?
- Currys has been expanding higher margin recurring services such as credit, installations, connectivity and repair, which now contribute over 30% of UK revenue and are growing faster than product sales.
- This shift means more of Currys income comes from ongoing service relationships rather than one off product purchases. This can change how investors think about the resilience and quality of its earnings.
- We will look at how Currys investment narrative is shaped by this push into higher margin recurring services across its UK operations.
Scan other service rich retailers that share some of Currys' recurring revenue DNA by running the 10 high quality undervalued stocks alongside your work on this stock.
Currys Investment Narrative Recap
For you to own Currys, you probably need to believe the shift toward higher margin recurring services, iD Mobile and B2B can keep supporting earnings quality while cost headwinds and IT spend are managed tightly. The near term swing factor is execution on these service led offers, not headline product volumes.
The biggest operational risk still sits in wage and tax pressures and the delayed UK cloud migration, which has already required sizeable exceptional cash outflows and dual running costs. The recent focus on services does not remove that risk, but it can reduce how much day to day hardware demand volatility drives results.
Among recent themes, the push to make recurring services more than 30% of UK revenue looks most relevant to the current Currys story. That mix shift connects directly to the main catalysts investors often watch, including EBIT margin resilience and cash generation, especially when wage and tax costs act as a drag.
Service expansion ties into Currys FlexPay credit, iD Mobile and after sales support, all of which add ongoing customer relationships on top of one off transactions. Execution risk remains around IT projects and the decision not to follow aggressive promotions in the Nordics, so the benefit of higher margin services still has to be earned operationally.
Currys Forecasts Behind The Service Shift
Currys' narrative projects £10.1b revenue and £155.8m earnings by 2029. This lines up with analyst assumptions of 2.8% yearly top line growth and an earnings decrease of £9.2m from £165.0m today.
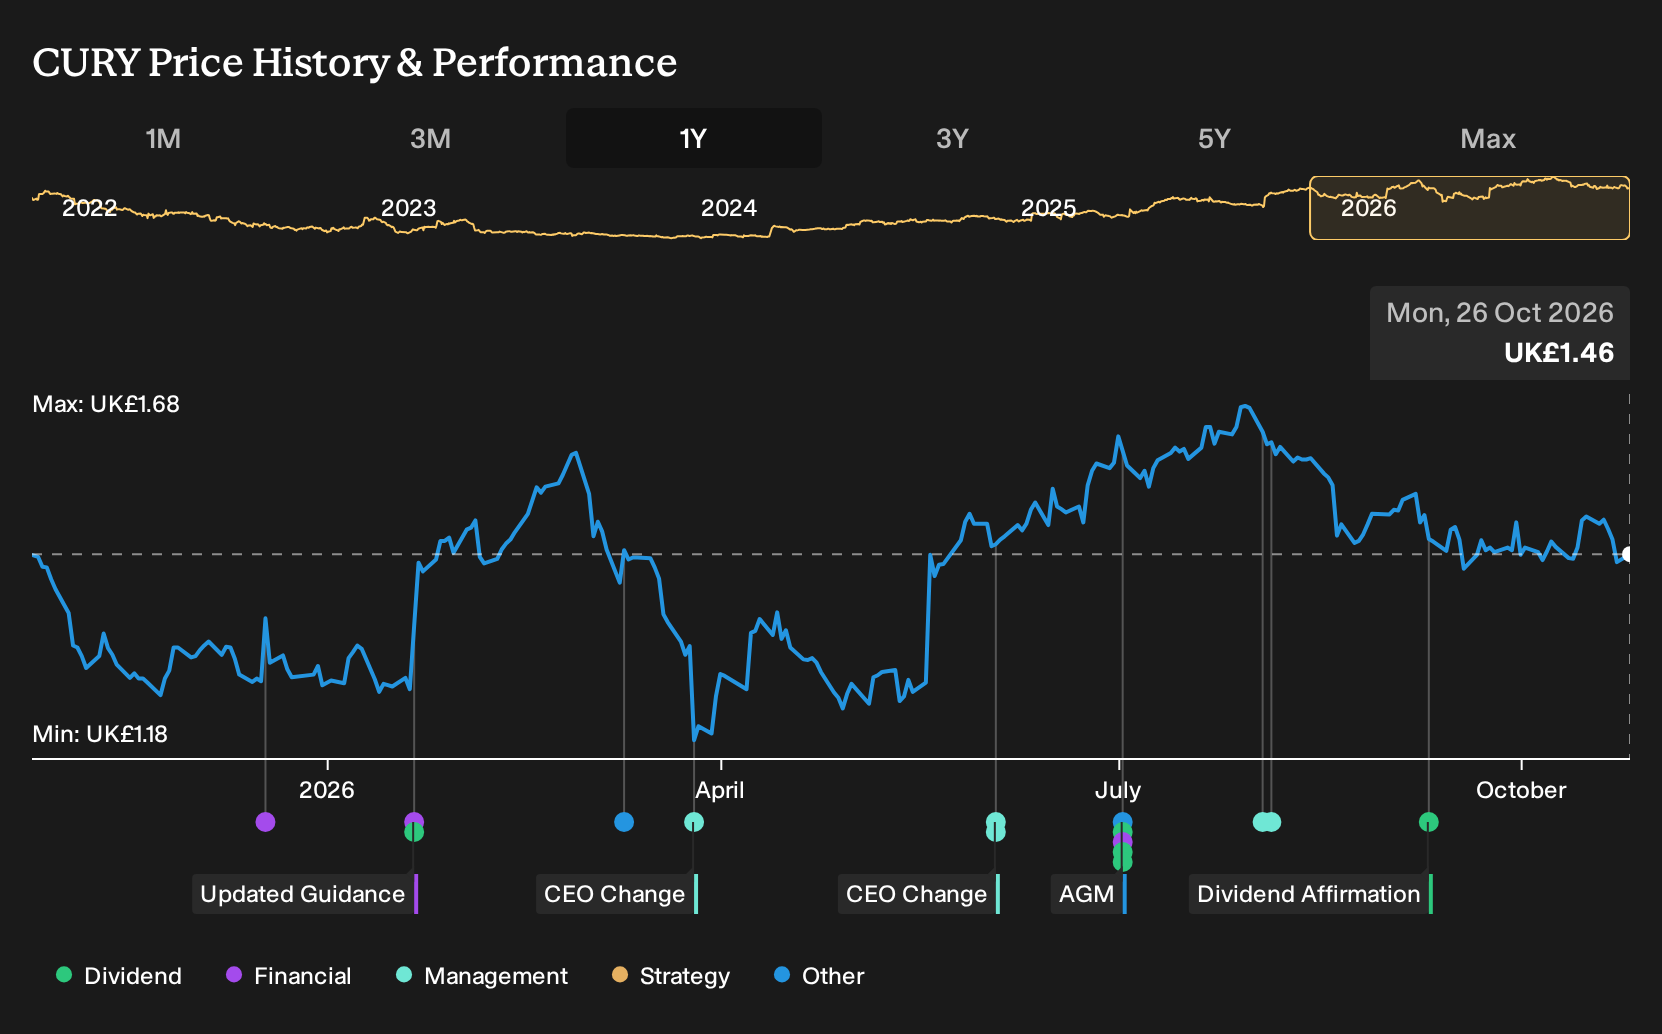
Uncover why Currys' fair value indicates a 27% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Currys focuses on the risk that online rivals continue to chip away at store traffic. The most bearish analysts were estimating revenue of about £9.9b and earnings of roughly £139.7m by 2029. That is a much darker script than consensus, and this latest services-focused news could eventually shift both stories.
Explore 3 other Currys fair value estimates, including one that suggests it could be worth just £1.52.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Currys research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Currys. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Currys' overall financial health at a glance.
Looking For More Ideas Beyond Currys?
If you want to pressure test your view on Currys, it can help to line it up against other stocks with different income profiles, risk levels and balance sheets using the Simply Wall St Screener.
- If income resilience is at the top of your list, compare Currys with companies that already screen as 5 dividend fortresses.
- If balance sheet strength matters more to you than headline growth, you can stress test your watchlist against a list of solid balance sheet and fundamentals (10 results).
- If you prefer underfollowed opportunities, you can broaden your hunting ground by scanning a 5 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com