


EN
DiDi Global (OTCPK:DIDI.Y) Could Be 84% Below Fair Value On Hong Kong Relisting Push
A fresh shareholder survey has put DiDi Global (OTCPK:DIDI.Y) back in focus, with investors strongly backing a potential Hong Kong relisting and pushing for clearer governance, including open earnings calls and a long overdue shareholder meeting.
That push for a Hong Kong relisting is landing at a tricky moment for DiDi Global. The share price is at US$3.11 after a 30 day share price return that is down 13.37% and a year to date share price return that is down 44.06%, while the 1 year total shareholder return is down 51.71%. The recent governance noise is arriving against a backdrop of fading momentum that investors will be weighing against the company’s longer multiyear total shareholder return record and the current valuation debate.
Pressure test DiDi Global against a hand picked group of other rideshare and platform operators by scanning for 21 high quality undiscovered gems that the market may not be fully pricing yet.
After a share price slide and a fresh governance push, DiDi Global now trades at a level that some investors see as penalty and others as opportunity. Does the current valuation still skew the risk reward toward buyers?
Preferred Multiple of 121.8x P/E: Is it justified?
On simple earnings math, DiDi Global looks expensive. The last close of $3.11 equates to a P/E of 121.8x, while the estimated fair P/E based on the SWS model sits at 49.1x and the broader US Transportation group is around 31.8x. That gap is large enough that any investor leaning on earnings as a yardstick needs a clear view of why the market is willing to pay up this far.
P/E compares the share price to annual earnings per share. A higher ratio often signals that holders are paying today for profits they expect to materialise in future years, which can be common for platforms that are still refining profitability or reinvesting heavily back into operations.
In DiDi Global's case, the stock trades on a P/E that is described as expensive versus peers at 10.5x, and also against the US Transportation industry at 31.8x. That premium is even starker against the SWS fair P/E estimate of 49.1x, a level the market could theoretically move toward if expectations cool or earnings do not ramp in line with optimistic scenarios.
Explore the SWS fair ratio for DiDi Global.
Result: Price-to-Earnings of 121.8x (OVERVALUED)
Still, the DiDi Global story carries clear risk if governance reforms stall or if profit growth, implied by a 121.8x P/E, does not materialise.
Find out about the key risks to this DiDi Global narrative.
Another View On DiDi Global's Value
While the 121.8x P/E points to a steep price tag, the SWS DCF model presents a very different picture. On that framework, DiDi Global at $3.11 is trading about 84% below an estimated fair value of $19.49, which frames the current quote as heavily undervalued. Which signal should investors consider more, the earnings multiple or the cash flow model?
Look into how the SWS DCF model arrives at its fair value.
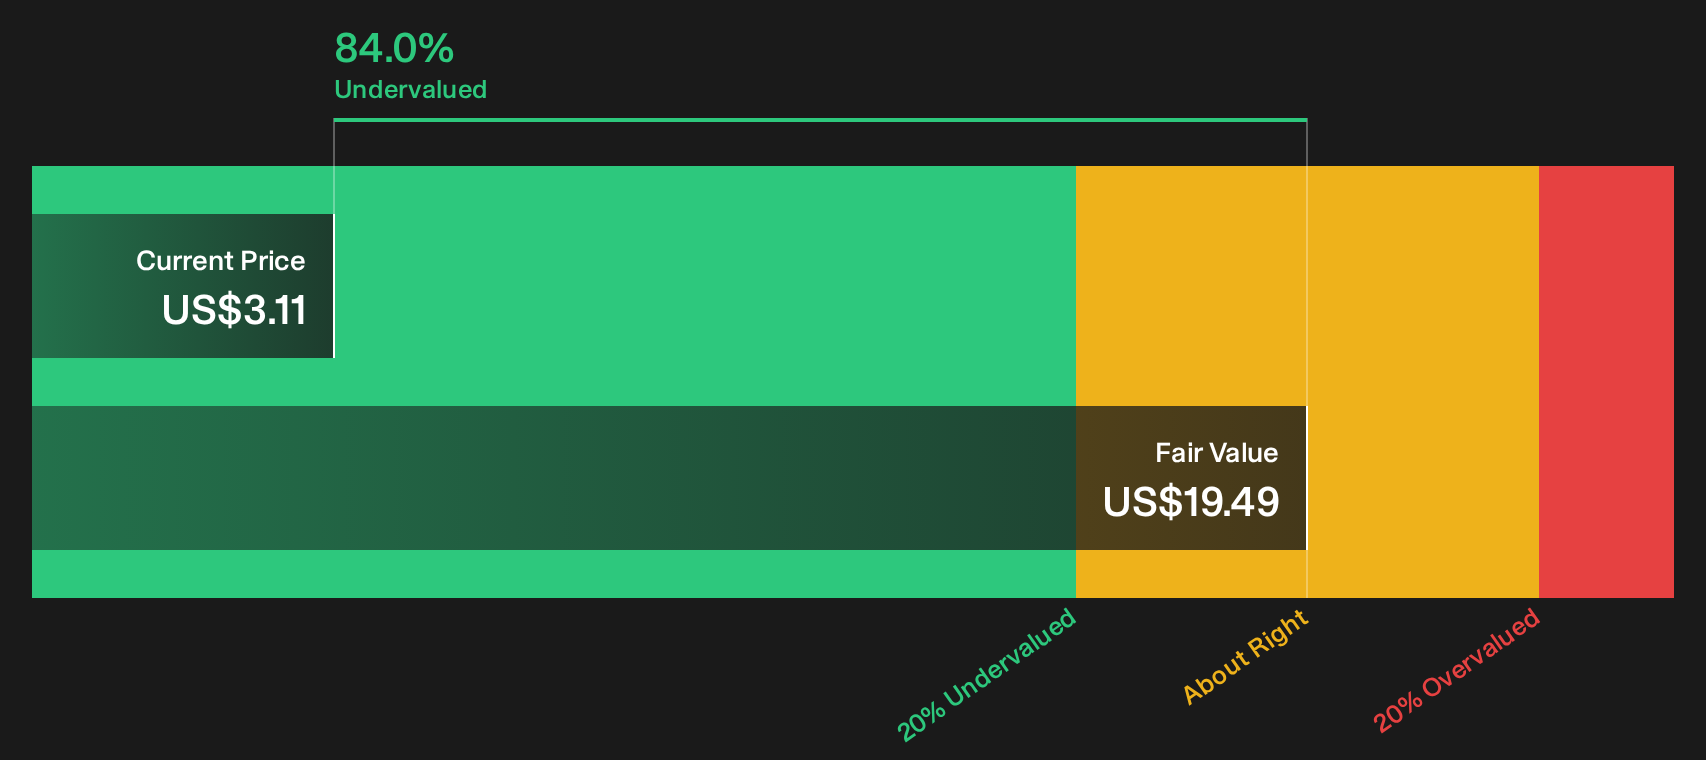
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DiDi Global for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals like DiDi Global's high P/E and discounted DCF estimate tend to split opinion. It helps to move quickly and anchor your own assessment by weighing both the upside potential and the governance and execution questions flagged in the 3 key rewards and 1 important warning sign.
Looking for more DiDi Global sized opportunities?
If DiDi Global has you thinking harder about price, risk and upside, do not stop with just one ticker. Cast a wider net and pressure test your ideas against other businesses using the Simply Wall Street Screener, so you are not relying on a single story when building your portfolio.
- Target potential mispricings by scanning a curated 29 high quality undervalued stocks that combine strong fundamentals with prices that may not fully reflect their underlying numbers.
- Strengthen portfolio resilience by focusing on a list of solid balance sheet and fundamentals (24 results) so short term shocks are less likely to force permanent capital losses.
- Prioritise stability and income by lining up a shortlist of 5 dividend fortresses that could help balance out more volatile positions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com