


EN
Brown & Brown (BRO) Shares Just Moved, So What Is Going On?
Brown & Brown (BRO) just delivered fresh third quarter results, reporting revenue of US$1.725b and net income of US$240m, and also rolled out its COMPASS data and AI insurance platform.
Brown & Brown’s latest move into data and AI with COMPASS lands after a mixed run for holders, with the share price falling 8.43% year to date and the 1 year total shareholder return down 18.22%. However, the 30 day share price return of 16.87% hints at momentum rebuilding around the US$71.08 level.
Spot fresh insurance and AI momentum by comparing Brown & Brown’s COMPASS rollout with other hand picked insurers in the 30 resilient stocks with low risk scores.Brown & Brown now trades at a discount to both analyst targets and an estimate of fair value, while the market still prices in caution after a weak 1 year return. Is that skepticism still warranted after COMPASS and these results?
Most Popular Narrative: 5% Undervalued
Against Brown & Brown's last close of $71.08, the most followed narrative points to a fair value of $74.75, suggesting modest upside that market pricing has not fully reflected even after the recent rebound.
The current valuation implies the share price already reflects some pressure from modest Retail organic growth and producer departures, while assigning less credit to the cash generation, AI efficiency gains and expected Accession synergies that underpin the view that Brown & Brown may be undervalued.
See why 31 investors see Brown & Brown as 5% undervalued.
Result: Fair Value of $74.75 (UNDERVALUED)
Still, the narrative around Brown & Brown can change quickly if producer departures drag on client retention or if weaker CAT property pricing continues to squeeze program related income.
Find out about the key risks to this Brown & Brown narrative.
Another View: Brown & Brown On Earnings Multiples
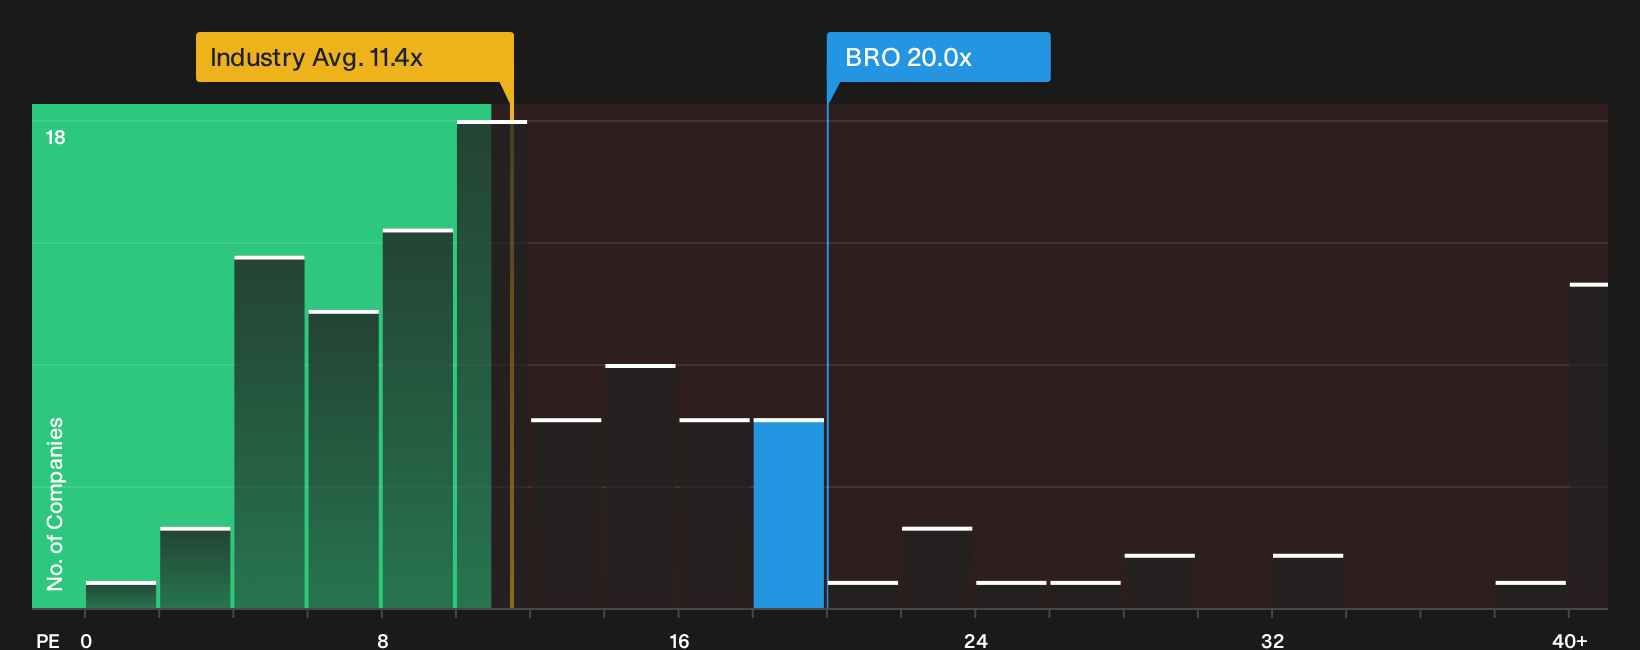
The DCF based fair value of $96.33 paints Brown & Brown as undervalued, yet the P/E picture is less generous. The shares trade on roughly 20x earnings compared with a fair ratio of 12x and an industry average of 11.4x. Does that gap flag upside, or valuation risk if sentiment cools?
To see how that earnings multiple could compress or hold up, investors can review the full valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
It is uncertain whether Brown & Brown is currently priced for caution or quiet opportunity. Consider reviewing the numbers yourself promptly and weighing both the upside and downside highlighted in the 2 key rewards and 2 important warning signs.
Looking for more Brown & Brown style opportunities?
If you stop at Brown & Brown, you risk missing other ideas that match your goals, risk profile, and income needs across the wider market.
- Target resilient balance sheets by scanning companies in the list of solid balance sheet and fundamentals (24 results) that pair financial strength with room for future surprises.
- Hunt for mispriced potential using the 21 high quality undiscovered gems and spot lesser known businesses with fundamentals that may not yet be fully appreciated.
- Build a cash flow anchor around the 5 dividend fortresses and find income focused opportunities offering yields that could complement Brown & Brown in a portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com