


EN
Should Biomethane And Battery Storage Expansion Require Action From Engie (ENXTPA:ENGI) Investors?
- Engie announced a partnership with CMA CGM to develop a large biomethane plant in Le Havre and disclosed a broad European buildout of battery storage assets across Poland, Romania, Spain, Belgium, Portugal, the UK and the Netherlands.
- The Le Havre biomethane project and new storage portfolio indicate Engie is shifting more capital toward contracted low carbon fuels and grid flexibility, which can influence earnings mix, project execution risk and long-term infrastructure commitments.
- We will examine how Engie’s investment narrative is affected by this biomethane and storage push across European power markets.
Engie Investment Narrative Recap
To own Engie, you need to believe the business can steadily shift its earnings mix toward regulated networks and contracted low carbon assets while managing economic net debt of about €60b and 4.2x EBITDA leverage. The most important near term driver is execution on this build out without eroding returns or stretching the balance sheet further.
The biggest risk remains that weaker Renewables and Flex Power EBIT, already down 5% organically in H1 2026, persists and is not offset by inflation linked network cash flows. The new biomethane and storage projects support the long term strategy but do not materially change the short term balance between risk and potential reward at this stage.
The Le Havre biomethane facility with CMA CGM is a clear operational fit with Engie’s energy transition focus. It adds a contracted, low carbon fuel platform that can complement the 7 GW of power purchase agreements with data centers and the wider push into renewable gases, helping link infrastructure to end demand.
What matters for investors is how effectively Engie brings this complex project to first gas around 2029 or 2030, alongside its 2.4 GW of recent new capacity and more than 10 GW of storage. Any delays, cost overruns or permitting issues would feed into existing concerns about leverage, cash flow coverage and dividend sustainability.
Engie's current analyst script points to revenues of €90.2 billion and earnings of €5.6 billion by 2029. That profile is built on 8.5% yearly revenue growth and an earnings uplift of about €1.5 billion from today’s €4.1 billion profit base.
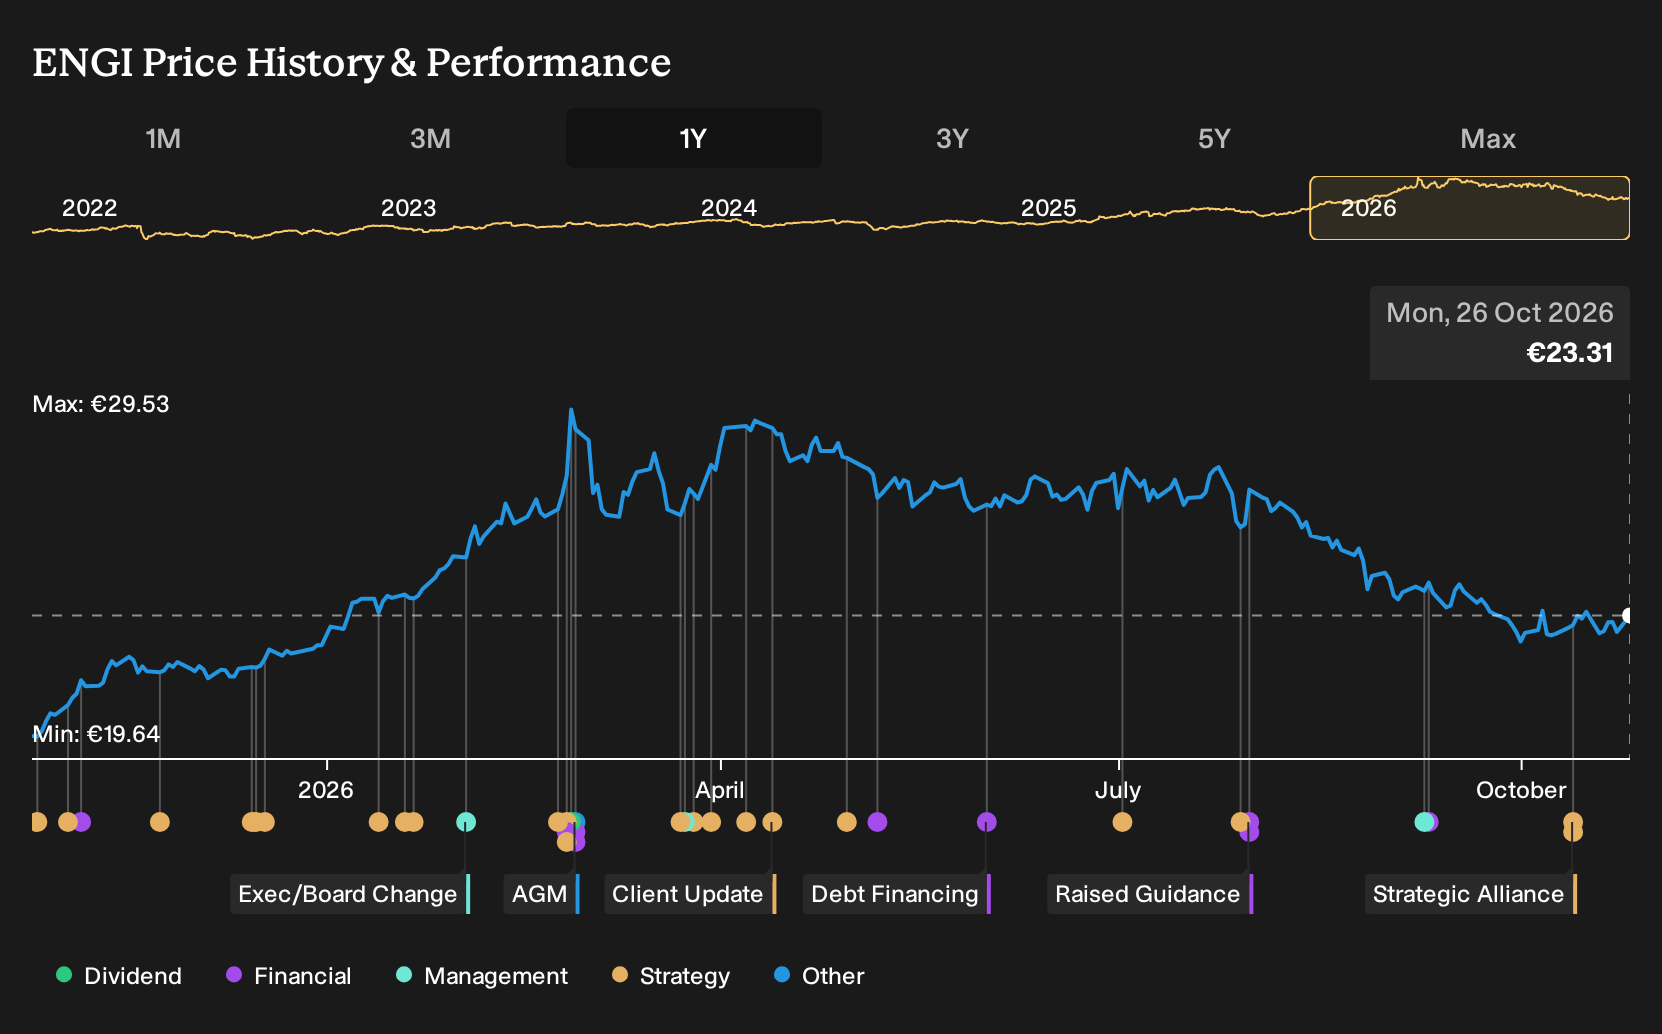
Uncover why Engie's fair value indicates a 31% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic Engie analysts were already framing UK Power Networks and grid expansion as the real swing factor, not projects like Le Havre. They were pencilling in revenue of about €100.2b and earnings of €5.8b by 2029. You can treat this new biomethane and storage push as fresh information that could shift those views, and you can compare several possible narratives before deciding what makes sense to you.
Explore 3 other Engie fair value estimates, including one that suggests as much as 31% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Engie research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Engie. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, which makes it easier to evaluate Engie's overall financial health at a glance.
Looking For More Ideas Beyond Engie?
If Engie is only one piece of your watchlist, it can help to scan for other stocks that match the kind of risk, quality or income profile you prefer. The Simply Wall St Screener gives you a structured way to do that, without relying on headlines or hype.
- For investors who want income that looks more durable, start with a shortlist of potential 224 dividend fortresses that may suit a yield focused approach.
- If capital preservation is front of mind, filter for a 223 resilient stocks with low risk scores and narrow in on candidates that better match your comfort with volatility.
- When you want quality businesses that the market may be overlooking, scan through a 610 high quality undiscovered gems and see which stories deserve a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com