


EN
Avnet (AVT) After Its Credit Deal Reset Looks Undervalued On One Popular View
Avnet (AVT) just reshaped its lending playbook. The company amended its credit agreement, lifting total committed borrowing capacity to US$2.75 billion and removing the SOFR credit spread adjustment on interest costs.
That refinancing lands at a moment when Avnet’s share price has pulled back 13.02% over the past 30 days after a strong run, even as the year-to-date share price return of 81.70% and 1-year total shareholder return of 78.95% point to momentum that has built over several years, with 3-year and 5-year total shareholder returns of 109.92% and 159.05% respectively.
Scan Avnet’s refinancing move alongside peers by reviewing our hand-picked list of solid balance sheet and fundamentals (24 results) in similar capital-intensive sectors.
After that refinancing and a huge multiyear run, the recent pullback leaves Avnet at a crossroads. Is most of the easy gain already in the rearview mirror, or does the valuation still point to room on the upside?
Most Popular Narrative: 16% Undervalued
On the most followed view, Avnet’s fair value of $106.25 sits above the recent $89.65 close. This puts the refinancing decision in the context of a stock that the narrative treats as undervalued on long term earnings power under a 9.59% discount rate.
Ongoing geographic breadth combined with direct AI and data center exposure that management now estimates at roughly 10 to 15% of revenue, mostly in Asia and Taiwan, shows how Avnet is tied into cloud and AI infrastructure while also serving industrial, transportation and networking customers. This combination can influence future sales levels and earnings mix.
See why 11 investors see Avnet as 16% undervalued.
Result: Fair Value of $106.25 (UNDERVALUED)
Still, the Avnet narrative can crack if margin pressure from Asia and memory exposure becomes entrenched, and if prior share price gains reset faster than fundamentals.
Find out about the key risks to this Avnet narrative.
Another View: DCF Flags Avnet As Overvalued
The first story paints Avnet as about 16% undervalued relative to a US$106.25 fair value. A second lens using the SWS DCF model comes out very differently. On that cash flow work, Avnet at US$89.65 trades well above an estimated future cash flow value of US$24.48, which frames the stock as expensive rather than cheap. For anyone weighing these two signals, which toolkit do you trust more when earnings and cash generation pull in different directions?
To unpack how that cash flow result is built and what might need to change for the gap to close, walk through the full SWS DCF model step by step via Look into how the SWS DCF model arrives at its fair value.
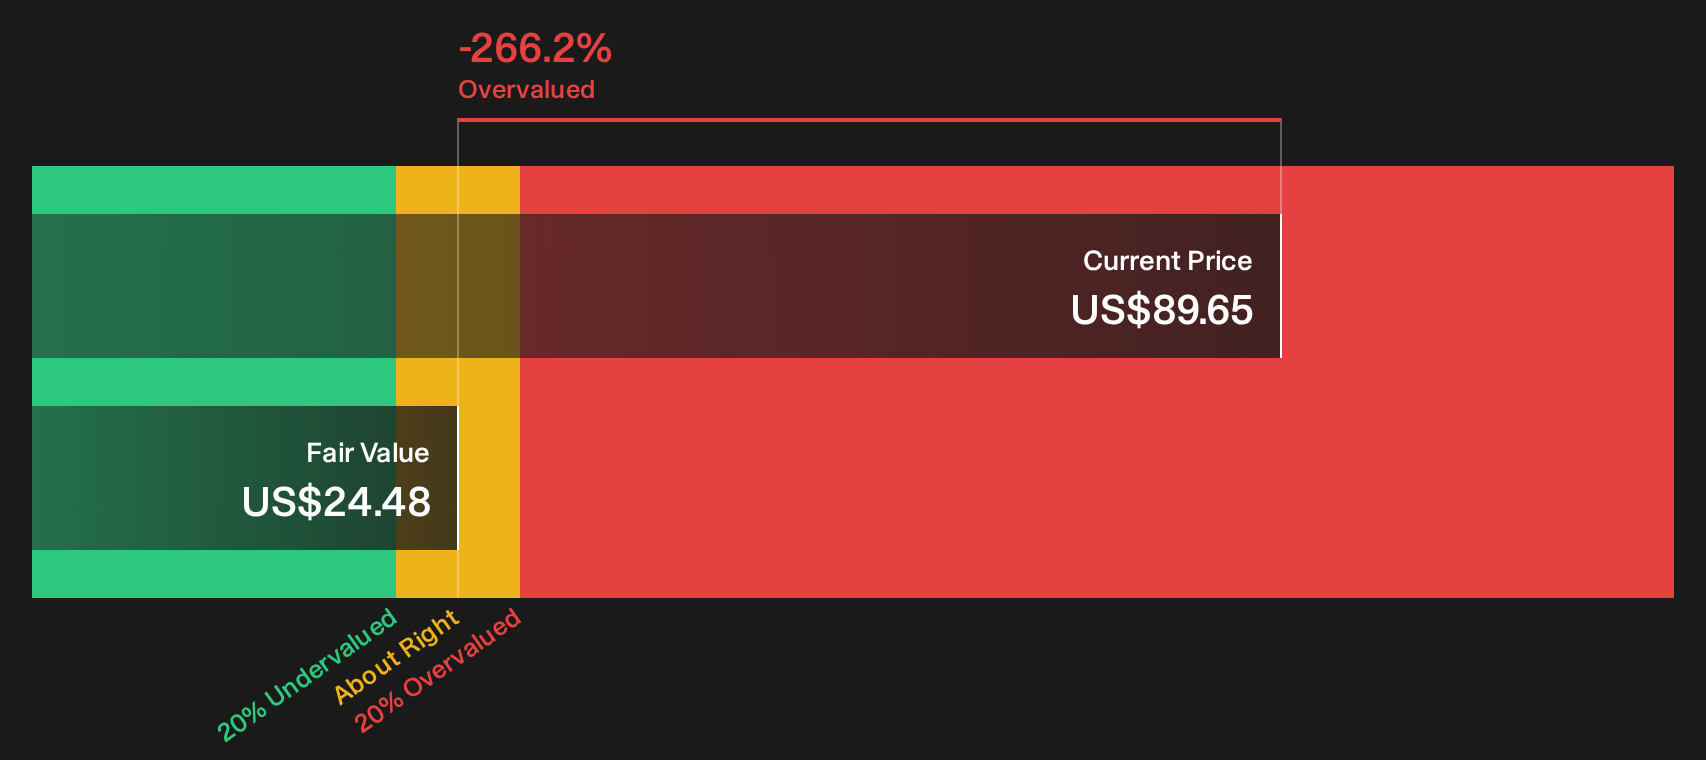
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Avnet for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Avnet can be useful if you let them push you to interrogate the numbers yourself and move before sentiment hardens. To weigh both the concerns and the upside potential in one place, start with 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Avnet?
Do not stop your research with Avnet. Broader context around quality, risk, and income can sharpen every decision you make from here.
- Target resilient balance sheets and steady fundamentals by scanning our carefully curated list of solid balance sheet and fundamentals (24 results) that highlight financially robust businesses.
- Hunt for potential upside by reviewing the 21 high quality undiscovered gems that combine strong underlying metrics with relatively low market attention.
- Prioritize income and stability by focusing on 5 dividend fortresses that pair higher yields with durable business profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com