


EN
Did Earnings Estimate Upgrade Just Shift Aramark (ARMK) Stock Narrative?
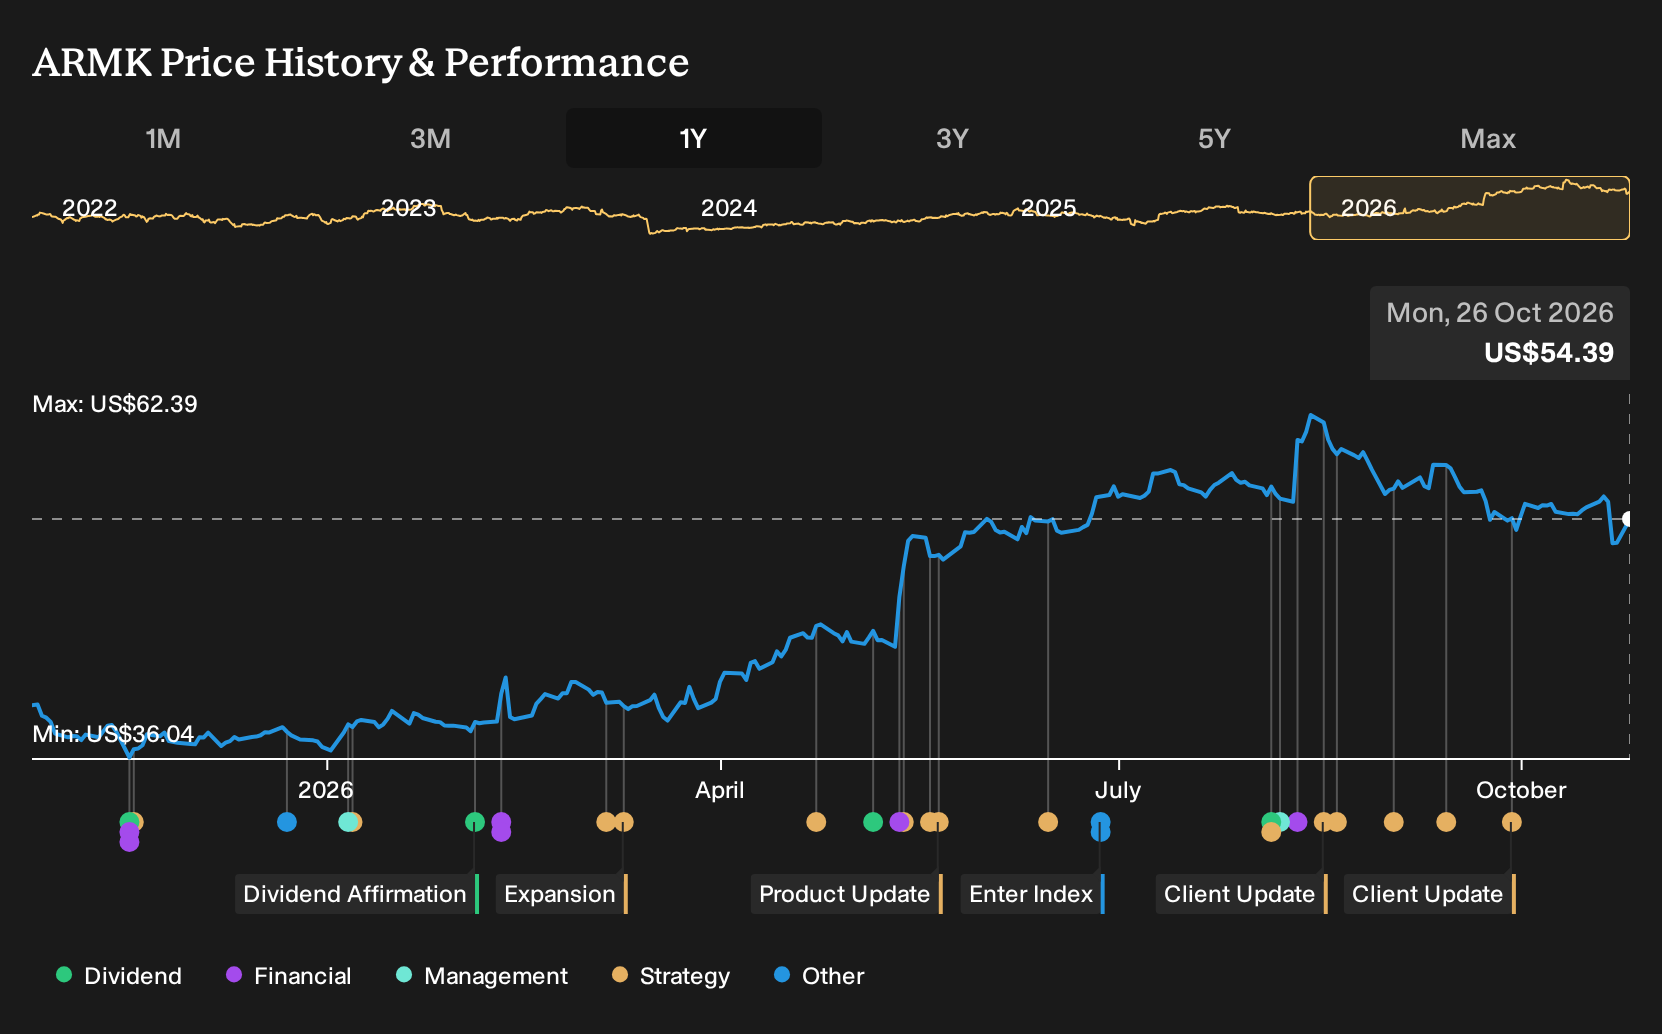
- Aramark has outperformed the broader Retail - Wholesale sector so far in 2026, with a 42.6% return compared with the sector’s 1% average, supported by a higher full year earnings estimate and a Zacks Rank of #2.
- This performance comes despite weakness across the Retail and Restaurants industry, which highlights how Aramark’s current earnings profile and contract base differ from many peers facing sector wide pressure.
- We will now look at how Aramark’s sector beating performance and upgraded earnings outlook interact with the existing investment narrative.
Scan how Aramark’s sector beating move compares with other potential outperformers by reviewing our hand picked list of 29 high quality undervalued stocks.
Aramark Investment Narrative Recap
To own Aramark, you need to be comfortable with a business that lives and dies by long term service contracts, execution quality, and the ability to keep turning high client retention into profitable work. The recent sector beating move mainly reinforces that the operating story around contract wins, international growth, and education demand is intact rather than changing the thesis.
The more immediate swing factor is whether Aramark can convert that revenue profile into stronger free cash flow while funding technology projects like Culinary CoPilot and Nexus. The biggest risk remains pressure on margins and cash generation if reputational issues or higher compliance costs hit at the same time as already tight interest coverage.
One of the more important developments tied to this story is the build out of Nexus, Aramark’s AI data center hospitality offering. Management expects three Nexus sites to contribute roughly US$400m to US$500m of annualized revenue in fiscal 2027 and 2028, with margins above the group average and relatively low capital needs.
For you as an investor, that potential income stream matters because it leans into the same contract heavy model but with a different customer mix and margin profile. If Nexus ramps effectively alongside ongoing wins in education and international markets, it can support the current growth focused narrative, while any execution slip would make Aramark more reliant on existing segments to carry earnings and cash flow.
What The Current Aramark Forecasts Assume
Analysts are effectively asking you to weigh up whether Aramark can turn contract momentum into a meaningfully bigger business without relying on heroic assumptions. The current consensus pins earnings today at about US$382.9 million and works off revenue that is expected to climb by 8.0% per year over the next three years. On top of that, margin forecasts move from 1.9% now to 3.5% by the end of that period, which would reshape how much profit each dollar of sales produces if it plays out as modeled.
Those same estimates push Aramark’s earnings to US$867.8 million by 2029, roughly 2.3x the level analysts cite today. That type of uplift rests on a mix of higher profitability, steady contract renewals, and controlled share count growth, with the share base projected to rise only 0.26% annually over the next three years. For an investor, the key question is less whether any single line item is aggressive and more whether this whole package of assumptions fits with your own read of Aramark’s contract quality, capital needs, and risk profile.
Aramark's narrative projects US$25.0b revenue and US$867.8 million earnings by 2029. This implies 8.0% yearly revenue growth and an earnings increase of about 2.3x from the current US$382.9 million.
Valuation work built around these figures also leans on a specific view of what multiple the stock might command. The Simply Wall St framework uses a discount rate of 9.49% and assumes the shares could trade on a P/E of 27.5x in 2029, compared with 37.6x today and an industry level of 19.0x for US Hospitality. That setup implies a scenario in which Aramark grows into a larger, more profitable operation yet still carries a richer earnings multiple than the sector benchmark.
Price targets flow directly from that structure. The current analyst consensus of US$68.5 per share sits 20.3% above the quoted US$54.59 price, with individual targets ranging from US$47.0 to US$75.0. For your own process, the practical takeaway is simple. These numbers offer a worked example of one path for Aramark, not a map, so any decision should come from testing these revenue, margin, and P/E assumptions against your personal expectations for the business rather than treating the target as a conclusion in itself.
Uncover why Aramark's fair value indicates a 26% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You can read the Aramark story very differently if you fixate on Nexus risk instead of contract momentum. The most cautious analysts were working off roughly US$24.7b in 2029 revenue and US$878.8 million in earnings before this latest move. That lower bar assumes slower payoff from AI data centers. Use it as a prompt to compare several viewpoints, not as a verdict.
Explore 2 other Aramark fair value estimates, including one that suggests as much as 35% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Aramark research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Aramark. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aramark's overall financial health at a glance.
Looking for more Aramark investment ideas?
If Aramark has sharpened your interest in contract driven businesses, use that curiosity to broaden your watchlist with companies that fit the kind of balance sheet strength, yield profile, or potential mispricing you want exposure to.
The Simply Wall St Screener is a quick way to line up those filters and see which other stocks match your criteria:
- If capital preservation is high on your list, start with companies that show more resilient financial profiles and review our 30 resilient stocks with low risk scores that may better fit a lower volatility approach.
- If cash returns matter to you, focus on dependable income ideas and scan our 5 dividend fortresses that might offer more consistent yield potential.
- If you are hunting for overlooked opportunities with solid fundamentals, look across our 21 high quality undiscovered gems that could complement a higher conviction basket.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com