


EN
Semtech (SMTC) Expands 5G And AI Capacity, Is The Valuation Still Compelling?
Semtech stock: why new 5G public safety gear and AI data center capacity matter now
Semtech (SMTC) just rolled out new AirLink 5G networking features for public safety fleets and extended a multi year silicon germanium supply deal with Tower Semiconductor, putting critical communications and AI data center demand in clearer focus.
Across the past month the share price return on Semtech has fallen 25.0%, even after a 3.6% gain in the last session. Yet the year-to-date share price return of 81.7% and a one-year total shareholder return of 93.5% still point to strong momentum that recent 5G and AI data center announcements are now being measured against.
Ride this theme further by scanning a hand picked set of AI infrastructure peers through the 55 AI infrastructure stocks benefiting from similar data center and high speed connectivity demand.Semtech appears to have real products tied to critical 5G and AI infrastructure, yet the share price has recently swung sharply in both directions. Do the current numbers still justify this level of optimism reflected in the valuation?
Most Popular Narrative: 38% Undervalued
At a last close of $136.73 against a narrative fair value of $220.00, Semtech is framed as meaningfully discounted, with that gap resting on how well data center and IoT growth themes actually play out.
Accelerating demand from hyperscale data centers and AI infrastructure is driving robust, multi year growth across Semtech's high margin data center business, supported by design wins in advanced optical (FiberEdge), low power (LPO), and active copper interconnects (CopperEdge/ACC). As data rates move from 400G to 800G and 1.6T, Semtech stands to capture significant revenue and margin expansion from new content per deployment.
What is behind 40 investors see Semtech as 38% undervalued.
Result: Fair Value of $220.00 (UNDERVALUED)
Still, Semtech’s story can be knocked off course if integration issues persist around past deals, or if Chinese demand and data center spending turn choppy again.
Find out about the key risks to this Semtech narrative.
Another View: What Semtech’s P/E Is Saying
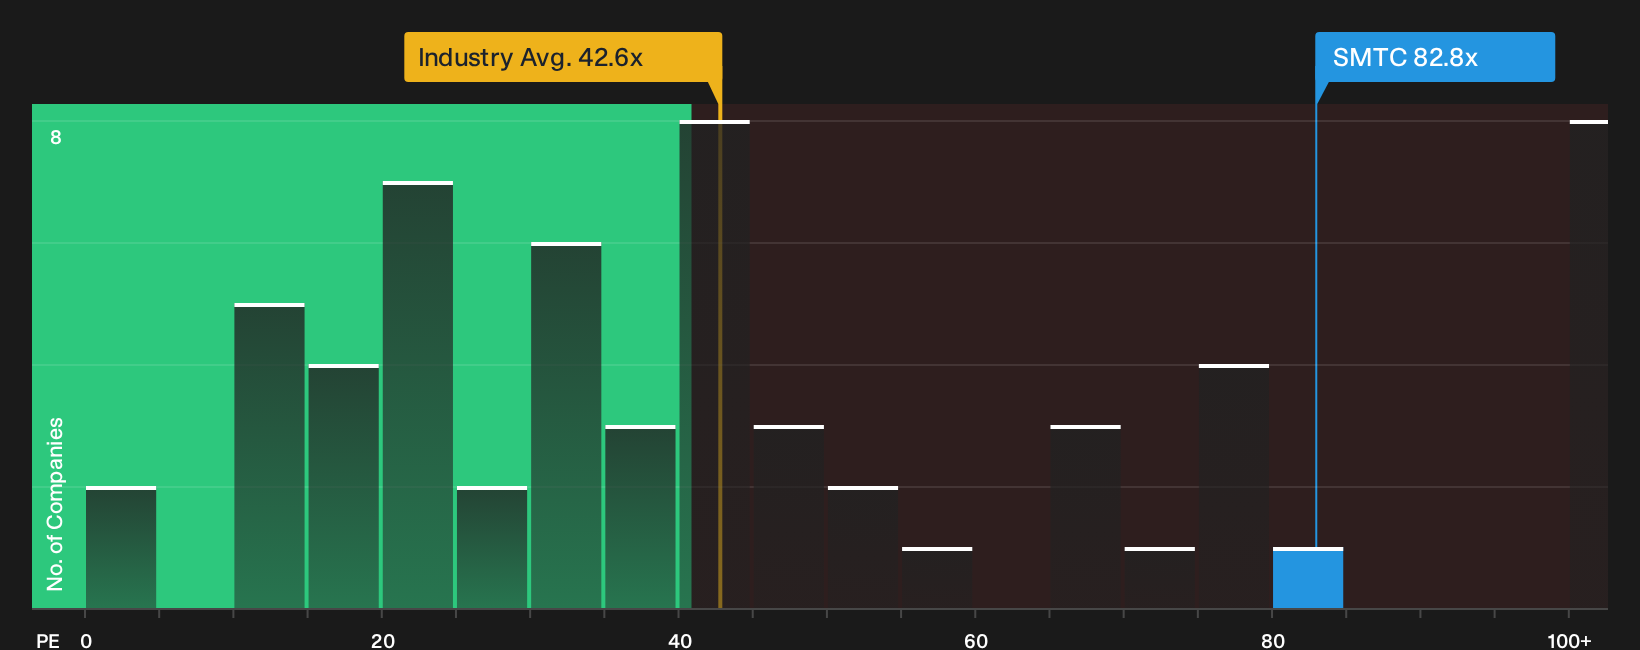
The DCF story paints Semtech as undervalued, yet the simple P/E check sends a very different signal. At 82.8x earnings, the stock trades at almost double the US Semiconductor industry on 42.6x and well above a fair ratio of 45.4x. That gap points to real valuation risk if expectations slip, so which signal do you trust more today?
For a closer look at how this earnings multiple compares with peers and the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of optimism and caution around Semtech feels familiar, treat it as your cue to act promptly and stress test the thesis against the 4 key rewards and 3 important warning signs.
Looking for more Semtech style investment ideas?
Do not stop your research with Semtech alone. Broader context from other high quality opportunities helps you judge whether this story really earns a place in your portfolio.
Use the Simply Wall Street Screener to quickly compare Semtech against other focused ideas and build a shortlist that actually matches your risk and return goals.
- Target potential upside with a curated 21 high quality undiscovered gems that highlights lesser known businesses with solid fundamentals before they gain wider attention.
- Prioritise resilience by scanning a list of solid balance sheet and fundamentals (24 results) so you can line up companies that pair financial strength with consistent execution.
- Calm portfolio swings by reviewing a 30 resilient stocks with low risk scores that filters for businesses with more stable risk profiles when markets turn choppy.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com