


EN
Cleveland-Cliffs (CLF) Dropped, So What Is Behind The Latest Attention?
Cleveland-Cliffs (CLF) is back in the spotlight after third quarter 2026 results showed sales of US$5,612 million and net income of US$152 million, compared with a loss a year earlier.
Cleveland-Cliffs shares trade at US$13.38 after a one day share price return that declined 3.74%. The 30 day share price return is up 9.85% and the 90 day move has risen 11.69%, while the five year total shareholder return is still down 42.40%. This suggests recent momentum is improving but long term holders have yet to recover earlier losses.
Scan how Cleveland-Cliffs stacks up against other potential rebound stories by reviewing our hand-picked list of 29 high quality undervalued stocks in the current market.
Cleveland-Cliffs has returned to profitability and the share price has started to move higher, yet five-year returns remain deeply negative. Is this an early entry worth considering now, or a story to revisit only after a more attractive price?
Most Popular Narrative: 6% Overvalued
The most followed narrative currently pegs fair value for Cleveland-Cliffs at $12.60, slightly below the last close of $13.38. This frames the stock as modestly ahead of that scenario while still tied to the same core drivers of tariffs, automotive demand and cost work.
Ongoing footprint changes and unit cost work, including a projected US$10 per ton decline in 2026 costs following several years of reductions, create scope for higher EBITDA and net margins if Cleveland-Cliffs maintains current shipment guidance.
See why 59 investors see Cleveland-Cliffs as 6% overvalued.
Result: Fair Value of $12.60 (OVERVALUED)
Still, the Cleveland-Cliffs narrative could be knocked off course if U.S. steel tariff enforcement loosens, or if another sharp spike in energy costs hits margins.
Find out about the key risks to this Cleveland-Cliffs narrative.
Another View: Cleveland-Cliffs On Simple Sales Maths
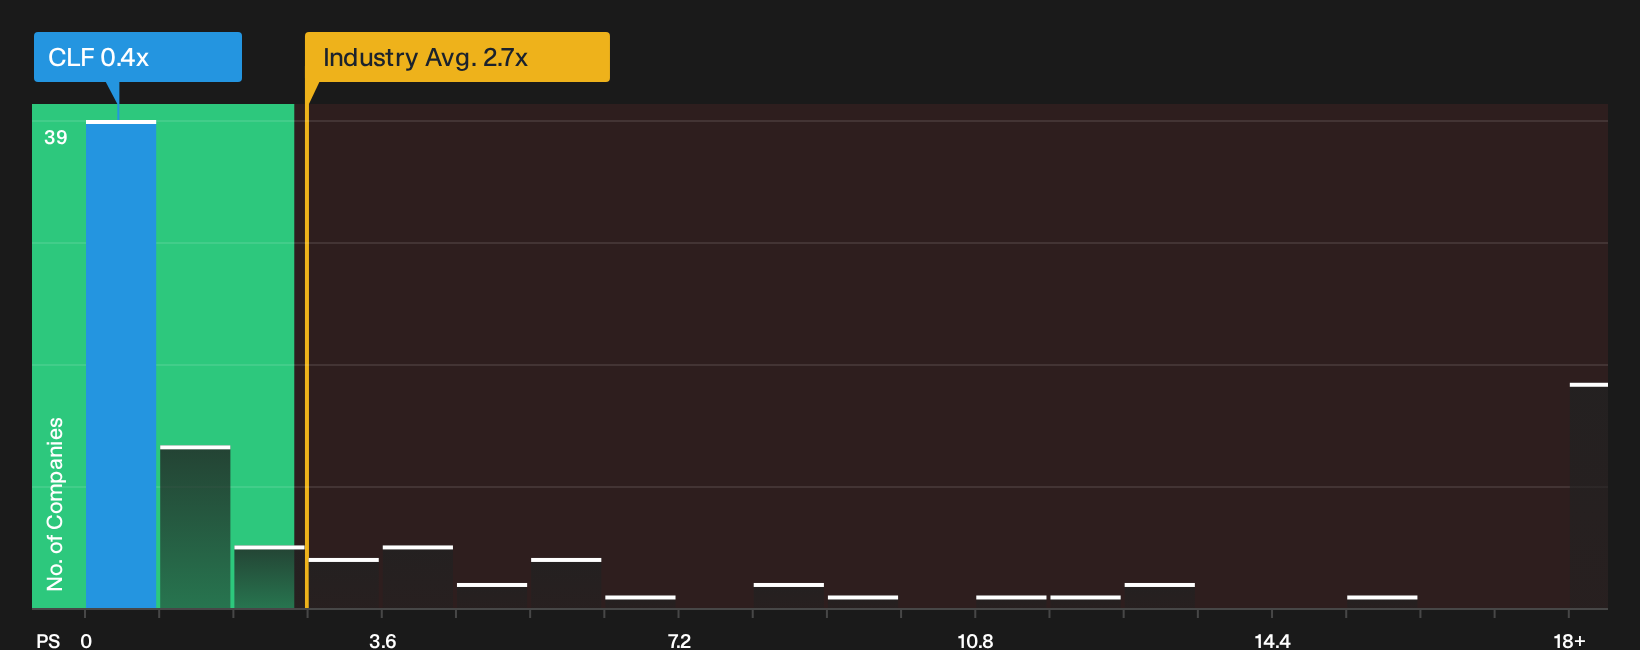
The narrative pegs Cleveland-Cliffs as about 6% overvalued at $12.60 fair value, yet the plain P/S number tells a very different story. The stock trades at 0.4x sales, compared with 2.7x for the US Metals and Mining industry, a 1.6x peer average and a fair ratio of 0.8x that the market could shift toward over time.
That gap means investors are paying materially less for each dollar of Cleveland-Cliffs revenue than for sector peers, while the fair ratio indicates room for sentiment to change direction. The question is whether current profitability issues, debt coverage and recent dilution justify that discount or leave mispricing on the table.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Be cautious about the mixed messages surrounding Cleveland-Cliffs and its recent share price recovery. Move quickly from headline impressions to hard data by weighing both upside and downside signals in the 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Cleveland-Cliffs?
If Cleveland-Cliffs has your attention, do not stop here. Use the Simply Wall Street Screener to surface other stocks that might better fit your goals.
- Target steady compounding by scanning a curated set of resilient companies in the 30 resilient stocks with low risk scores that aim to keep big drawdowns in check.
- Hunt for strong balance sheets by running through the list of solid balance sheet and fundamentals (24 results) so you are not caught out by fragile finances when conditions change.
- Spot potential future leaders early by combing through the 21 high quality undiscovered gems before attention and price move ahead without you.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com