


EN
How Peer Earnings Strength Will Impact First Financial Bancorp Stock
- First Financial Bancorp is scheduled to report quarterly earnings after the close, following a prior quarter where revenue of $262.9 million neither met analyst expectations nor management’s ambitions on net interest income, while EPS matched forecasts.
- The market is now focused on whether expected 15.6% year on year revenue growth will indicate that First Financial Bancorp’s lending and deposit engine is strengthening after mixed results last quarter.
- Attention will also be on how anticipation of that 15.6% revenue increase could reshape First Financial Bancorp’s broader investment narrative.
Scan the regional banking peer group before First Financial Bancorp reports by comparing its setup with our curated list of solid balance sheet and fundamentals (24 results) to identify potential standouts in the same space.
First Financial Bancorp Investment Narrative Recap
For you to own First Financial Bancorp, you need to be comfortable with a regional bank that leans on acquisitions in Chicago and Northwest Indiana, combined with disciplined balance sheet management to support its earnings engine. The key belief is that integrations keep delivering cost saves, low cost deposits, and stable net interest margin, rather than disruption.
The near term catalyst is the upcoming earnings print and whether revenue near the expected 15.6% year on year growth comes with healthier net interest income after last quarter’s miss. The biggest risk is that integration work or competitive deposit pricing pressures margins, which would dull that revenue story. If earnings land close to expectations, the recent news around peers does not look materially thesis changing.
The clearest reference point for this setup is Lakeland Financial’s latest quarter, where EPS of US$1.14 and revenue both came in ahead of estimates. That result puts a bit more attention on how efficiently similar regional banks are running their balance sheets.
For First Financial Bancorp, Lakeland’s beat matters mostly as a comparison tool rather than a direct driver. If First Financial’s report shows that Chicago and Northwest Indiana expansion and fee income lines are holding up against that kind of peer performance, investors may view the acquisition story and margin resilience as intact. A softer read across on net interest income or fees would highlight the existing risks around integration and competitive pressure rather than create new ones.
First Financial Bancorp’s current earnings sit at US$285.2 million and consensus points to US$455.1 million by 2029. This implies about a US$169.9 million increase, alongside revenue that analysts expect to reach US$1.4b on the back of 13.5% yearly top line growth over that period.
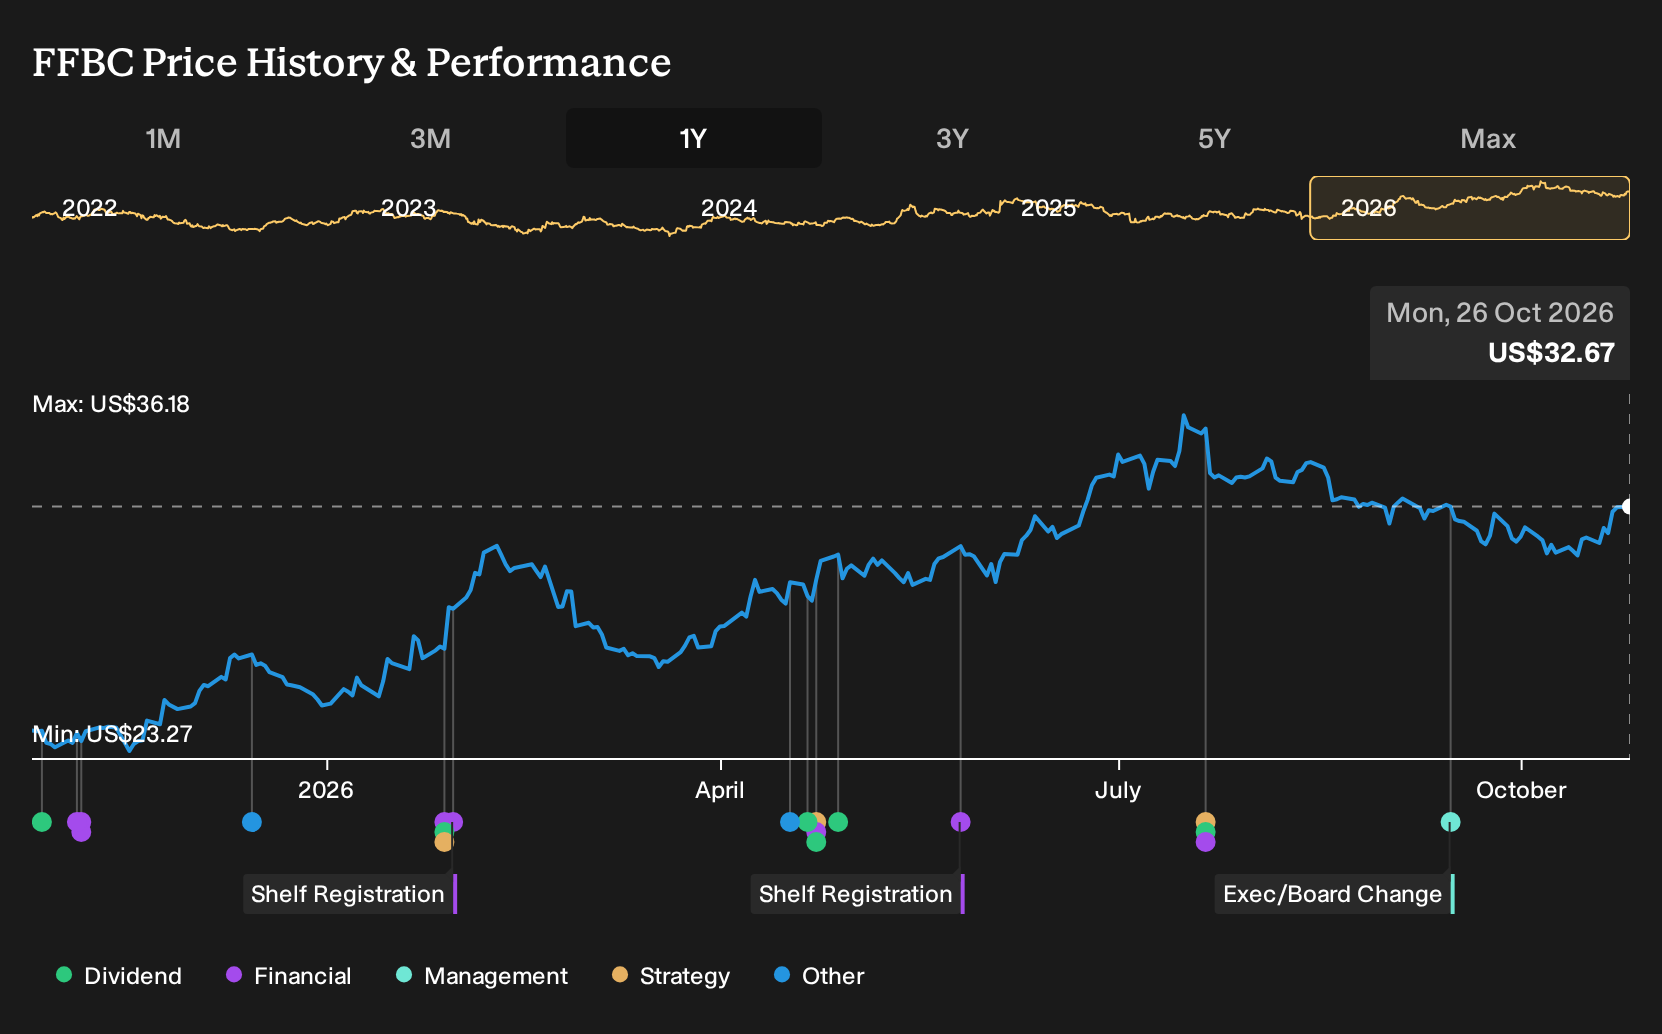
Uncover why First Financial Bancorp's fair value indicates a 16% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span roughly US$37.86 to US$52.63, so retail opinions on First Financial Bancorp are already wide before the upcoming earnings and any read across from Lakeland Financial’s beat. Use that spread, along with the integration and margin risks, to test your own angle against competing viewpoints.
Explore another First Financial Bancorp fair value estimate, including one that suggests as much as 61% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your First Financial Bancorp research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for First Financial Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Financial Bancorp's overall financial health at a glance.
Looking For More Ideas Beyond First Financial Bancorp?
If you want to cross check the First Financial Bancorp setup against other opportunities, a quick pass through a few focused screens can help you spot different types of risk and reward profiles in minutes.
- For investors who prioritize value combined with quality fundamentals, scan our curated set of 29 high quality undervalued stocks that may warrant a closer look beside regional banks.
- If capital preservation and steadier profiles matter most to you, compare First Financial Bancorp to a 30 resilient stocks with low risk scores that aim to limit downside while still offering equity exposure.
- When you want to broaden your watchlist with underfollowed stories, search across a 21 high quality undiscovered gems that pair solid numbers with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com