


EN
Boston Beer Company (SAM) Faces A 1% Fair Value Gap After Q3 Earnings Beat
Q3 earnings spark fresh attention on Boston Beer Company stock
Boston Beer Company (SAM) has moved back into focus for investors after its third quarter earnings topped market expectations and management inched full year guidance higher, despite softer revenue and shipments.
That backdrop has pulled Boston Beer Company into a tighter spotlight, with the share price up 23.0% over the past month and 10.8% over the last week, even as the 1 year total shareholder return has declined 11.5%. This points to short term momentum against a weaker multi year track record.
Capitalize on the renewed interest in Boston Beer Company by comparing this rebound with other hand picked consumer stocks screened for pricing and quality through the 21 high quality undiscovered gems.The recent jump in Boston Beer Company stock shows investors still rate the business, even though the latest nine-month figures include a loss. The real question now is whether that renewed confidence already fully shows up in the price.
Most Popular Narrative: 1% Overvalued
On the most followed view, Boston Beer Company screens as slightly overvalued, with a fair value of $199 against a last close of $201.48. The valuation gap is small and hinges on how much credit you give future margin repair.
The current valuation implies the share price does not fully reflect Boston Beer Company’s progress on gross margin expansion, the growth of Sun Cruiser into a roughly US$0.5b retail brand and the benefits of a net cash balance with no debt.
See why 14 investors see Boston Beer Company as 1% overvalued.
Result: Fair Value of $199 (OVERVALUED)
Still, that fair value story can break quickly if the long running softness in Twisted Tea and Truly volumes deepens, or the US$191m can dispute bites harder.
Find out about the key risks to this Boston Beer Company narrative.
Another View: Boston Beer Company on Sales-Based Metrics
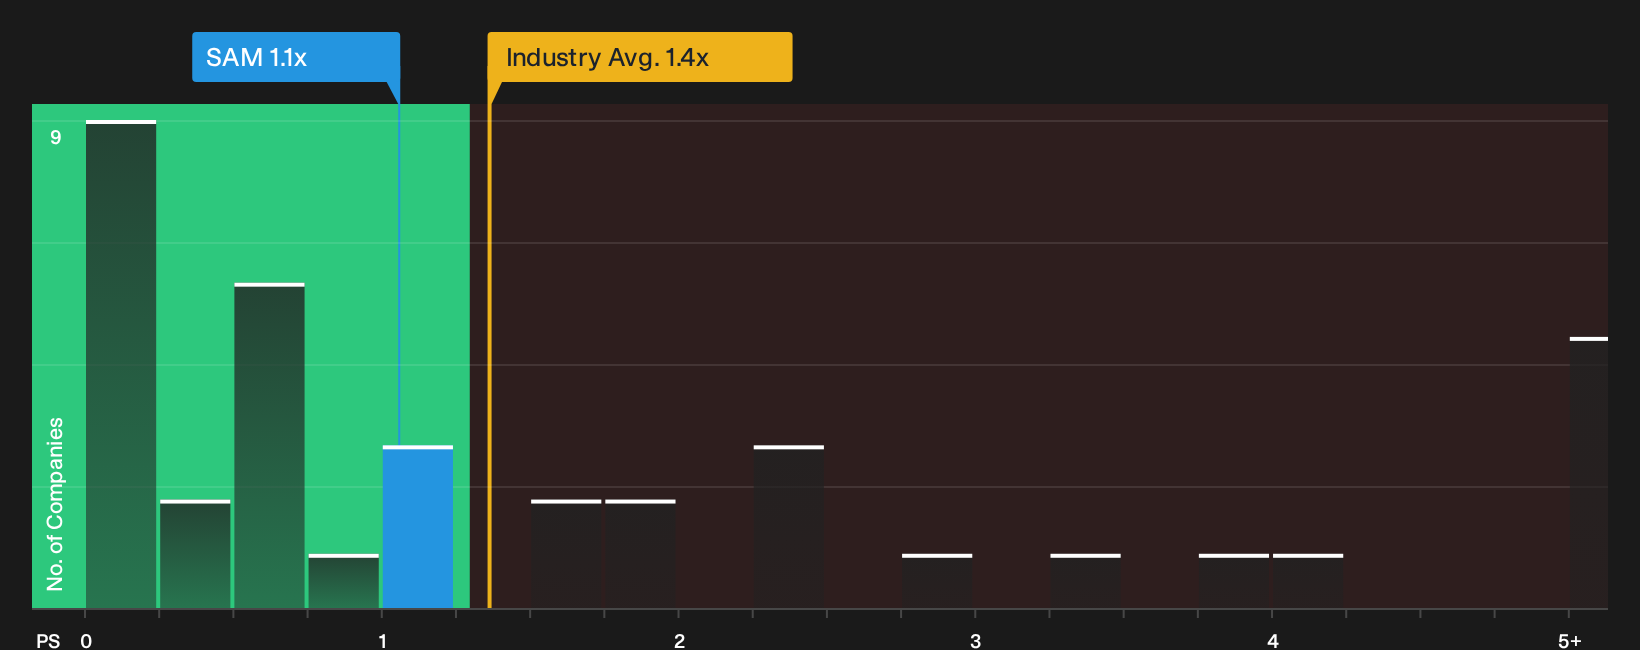
The first fair value of $199 flags Boston Beer Company as slightly overvalued against the current $201.48 share price. A different lens tells a softer story. On P/S of 1.1x, the stock lines up with its own fair ratio of 1.1x and sits below both US Beverage peers at 2.1x and the wider industry at 1.4x. That gap points to less exuberance baked into expectations, but also raises a blunt question for you as an investor: Is the discount on sales a genuine margin repair opportunity or a warning that the market doubts the earnings rebound narrative?
See what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Boston Beer Company is split, and that is exactly when your own work matters most. Move quickly, weigh the upside that others are watching, and check the 3 key rewards
Looking for more investment ideas beyond Boston Beer Company?
Do not stop with Boston Beer Company when there are other opportunities in plain sight that could better match your goals and risk comfort.
- Target quality at a discount by scanning companies that combine strong fundamentals with room for re rating through the 29 high quality undervalued stocks.
- Protect your downside by focusing on businesses with sturdy finances using the list of solid balance sheet and fundamentals (24 results).
- Hunt for future standouts early by tracking overlooked contenders with solid metrics inside the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com