


EN
Should Earnings Beat Require Action From Goldman Sachs (GS) Investors?
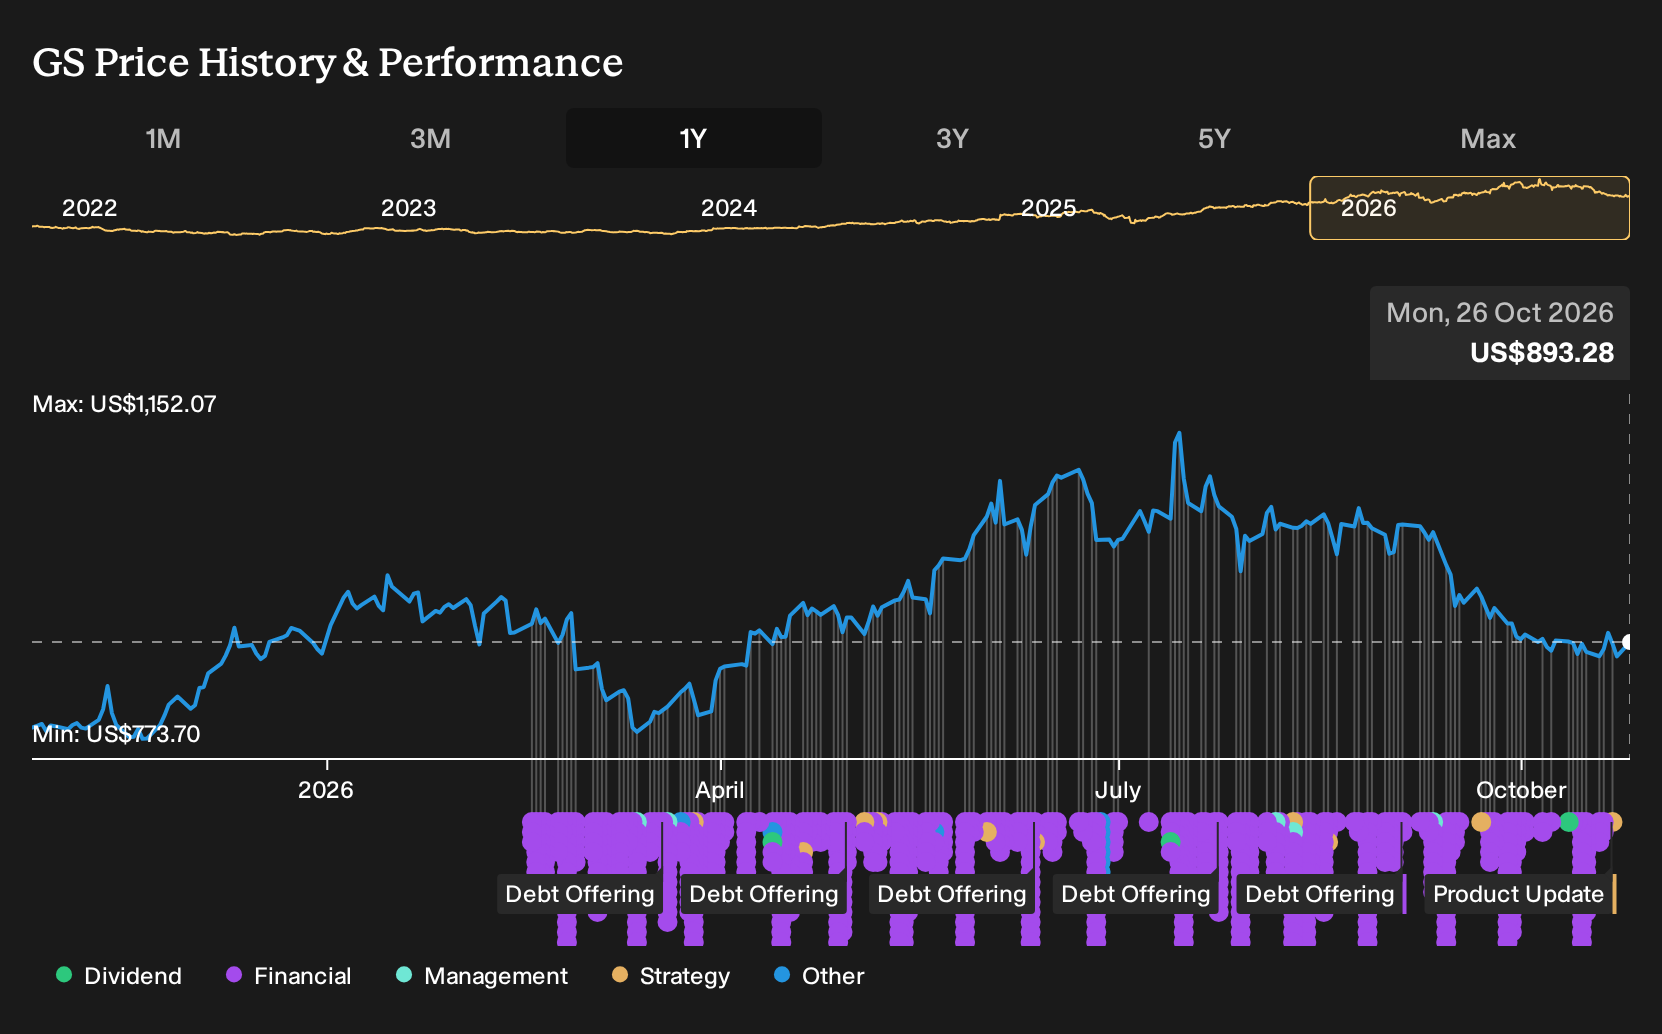
- Goldman Sachs Group reported third quarter 2026 net income of US$5,294 million and US$17,552 million for the first nine months, driven by Global Banking & Markets and Asset & Wealth Management. The firm also arranged multiple fixed income offerings across the curve with fixed coupons between 5.15% and 7.00%.
- The firm secured a lead underwriting role on Anthropic's planned IPO and launched a Small Business AI Institute with partners including Anthropic, Google, Meta and OpenAI. This initiative ties fee opportunities from AI related capital markets activity to longer term advisory, education and financing relationships.
- We will look at how Goldman Sachs Group's investment narrative is shaped by strong Q3 earnings alongside the Anthropic IPO mandate.
Scan how Goldman Sachs Group is leaning into AI themed capital markets deals, then compare it with 39 profitable AI stocks that aren't just burning cash already turning AI demand into real revenue and cash flow discipline.
Goldman Sachs Group Investment Narrative Recap
To own Goldman Sachs Group, you need to believe the firm can keep tilting toward fee based advisory, financing and asset and wealth management, while using AI and tech to prevent costs from running away. The recent surge in medium term notes and bonds shows funding access along the curve, but it does not, on its own, change that bigger story.
The near term swing factor is deal making and related financing volumes versus non compensation expenses that have been guided higher. The biggest risk is that heavier tech spending and activity related costs settle at a new level, squeezing margins if AI productivity and higher fee income do not offset that drag.
The Anthropic IPO mandate is the announcement that matters most here. It plugs directly into Goldman Sachs Group’s core catalyst of a fatter advisory backlog and more AI themed capital markets deals, which can support Global Banking & Markets alongside its fixed income issuance franchise.
This underwriting role also sits next to the new Small Business AI Institute, which anchors AI work across research, education and financing. Together, they show the business trying to tie near term deal fees to longer relationships in asset and wealth management, while still leaving it exposed to deal cycles and execution risk around tech and AI spending.
Goldman Sachs Group's narrative uses analyst assumptions that revenues reach US$74.4b and earnings reach US$21.7b by 2029, based on forecast revenue growth of 1.6% a year and an earnings increase of about US$0.4b from earnings today of US$21.3b.
Uncover why Goldman Sachs Group's fair value indicates a 16% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish twist on Goldman Sachs Group focuses on the credit cycle rather than AI fees. The most optimistic analysts were already penciling in US$79.5b of revenue and US$24.4b of earnings by 2029, assuming credit costs stay contained. You can now ask whether the Anthropic mandate and fresh bond issuance push that upbeat view even further or force a rethink.
Explore 4 other Goldman Sachs Group fair value estimates, including one that suggests there may be as much as 30% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A useful starting point for your Goldman Sachs Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could influence your investment assessment.
- See our latest analysis for Goldman Sachs Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which helps you evaluate Goldman Sachs Group's overall financial profile at a glance.
Looking for more investment ideas beyond Goldman Sachs Group?
Once you have a view on Goldman Sachs Group, it can help to widen the lens and compare it with other stocks that fit different return and risk profiles using the Simply Wall St Screener.
- If you care most about resilience, start with a 30 resilient stocks with low risk scores and see which businesses line up with a steadier risk profile than Goldman Sachs Group.
- If income matters to you, scan a focused set of 5 dividend fortresses that may offer stronger yield support alongside your Goldman Sachs Group thesis.
- If you want to spot earlier stage opportunities, broaden your watchlist with a curated 7 elite penny stocks with strong financials that match strict financial quality filters.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com