


EN
Bank of Chongqing (SEHK:1963) Draws Fresh Valuation Focus As Its P/E Trails Peers
Fresh attention on Bank of Chongqing (SEHK:1963) has been triggered by its current P/E trading below the broader banks sector and peer averages. This is raising pointed questions about how the market is pricing its earnings today.
Recent price action has been softer, with the 7 day share price return down 3.92% and the 30 day share price return down 5.54%. However, Bank of Chongqing still shows a very large 3 year total shareholder return of 143.75%, suggesting longer term momentum has been strong while near term sentiment has cooled.
Compare how Bank of Chongqing is priced against other potential value ideas by scanning a curated set of 195 high quality undervalued stocks that also pair earnings power with balance sheet strength.
Bank of Chongqing has a sizeable business footprint and a strong recent track record of shareholder returns, yet the P/E still trails sector and peer averages. Is this a solid franchise offered at a discounted price, or a value trap?
Price-to-Earnings of 4.3x: Is it justified?
On the numbers alone, Bank of Chongqing looks cheap, with a P/E of 4.3x while still trading at HK$7.85. That level sits below both the peer average of 5.1x and the Hong Kong banks sector on 4.9x, which points to a market that is pricing its earnings at a discount rather than a premium.
The P/E ratio tells you how many dollars investors are currently willing to pay for each dollar of earnings. For a bank like Bank of Chongqing, where profits and balance sheet strength are central to the story, P/E is a straightforward way to compare what you are paying for those earnings against other lenders in the same market.
Here the gap is clear. The stock trades below the peer average P/E of 5.1x and also below the estimated fair P/E of 7x from the SWS model. That is a level the market could move towards if sentiment and fundamentals line up. This spread suggests investors are assigning a lower multiple than both similar banks and the fair ratio imply, even though earnings quality is flagged as high and recent profit growth has outpaced the broader banks industry.
Explore the SWS fair ratio for Bank of Chongqing.
Result: Price-to-Earnings of 4.3x (UNDERVALUED)
Still, Bank of Chongqing faces risk if credit quality weakens in its Mainland China loan book or if funding costs squeeze earnings more than the market expects.
Find out about the key risks to this Bank of Chongqing narrative.
Another View on Bank of Chongqing’s Value
There is a second lens to use on Bank of Chongqing. The SWS DCF model points to a fair value of HK$29.25 per share while the stock trades at HK$7.85. That gap signals the cash flow view is much more optimistic than the current P/E suggests. Could the truth sit somewhere in between?
Look into how the SWS DCF model arrives at its fair value.
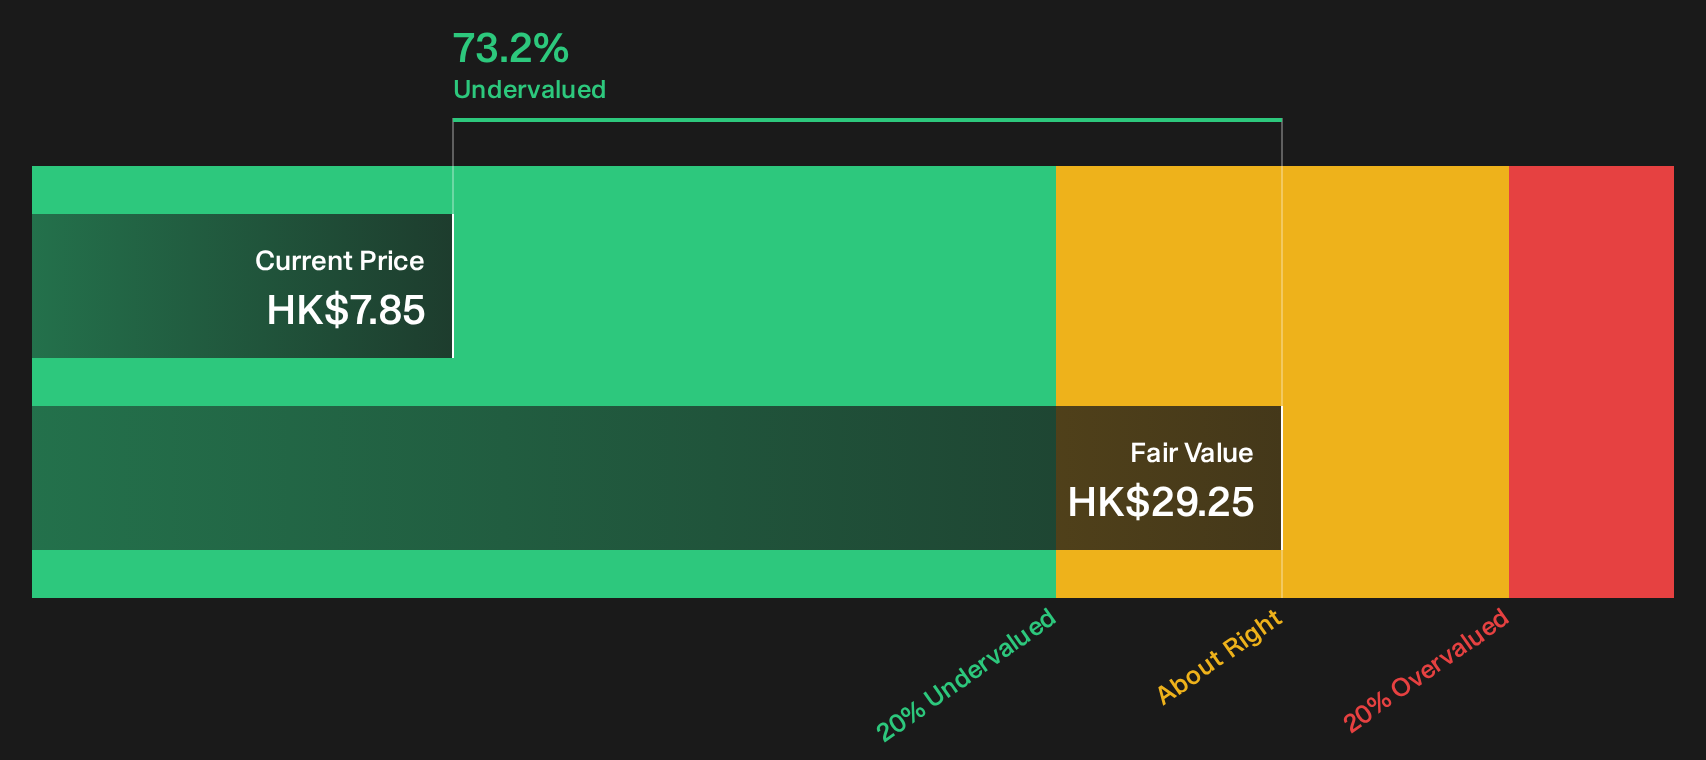
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bank of Chongqing for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Bank of Chongqing can cut both ways, so consider acting promptly, assess the potential upside and downside yourself, and then review the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Bank of Chongqing?
Do not stop with Bank of Chongqing. Use the Simply Wall St screener to compare fresh opportunities, sharpen your watchlist, and keep your capital working intelligently.
- Target reliable income streams by reviewing financially resilient high yield candidates in the 224 dividend fortresses.
- Hunt for potential mispricings by scanning the 610 high quality undiscovered gems that combine strong fundamentals with less crowded attention.
- Prioritise capital preservation and steadier journeys by assessing the 223 resilient stocks with low risk scores that score well on resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com