


EN
Why Sterlite Technologies Doubters Were Wrong Before A 628% Gain
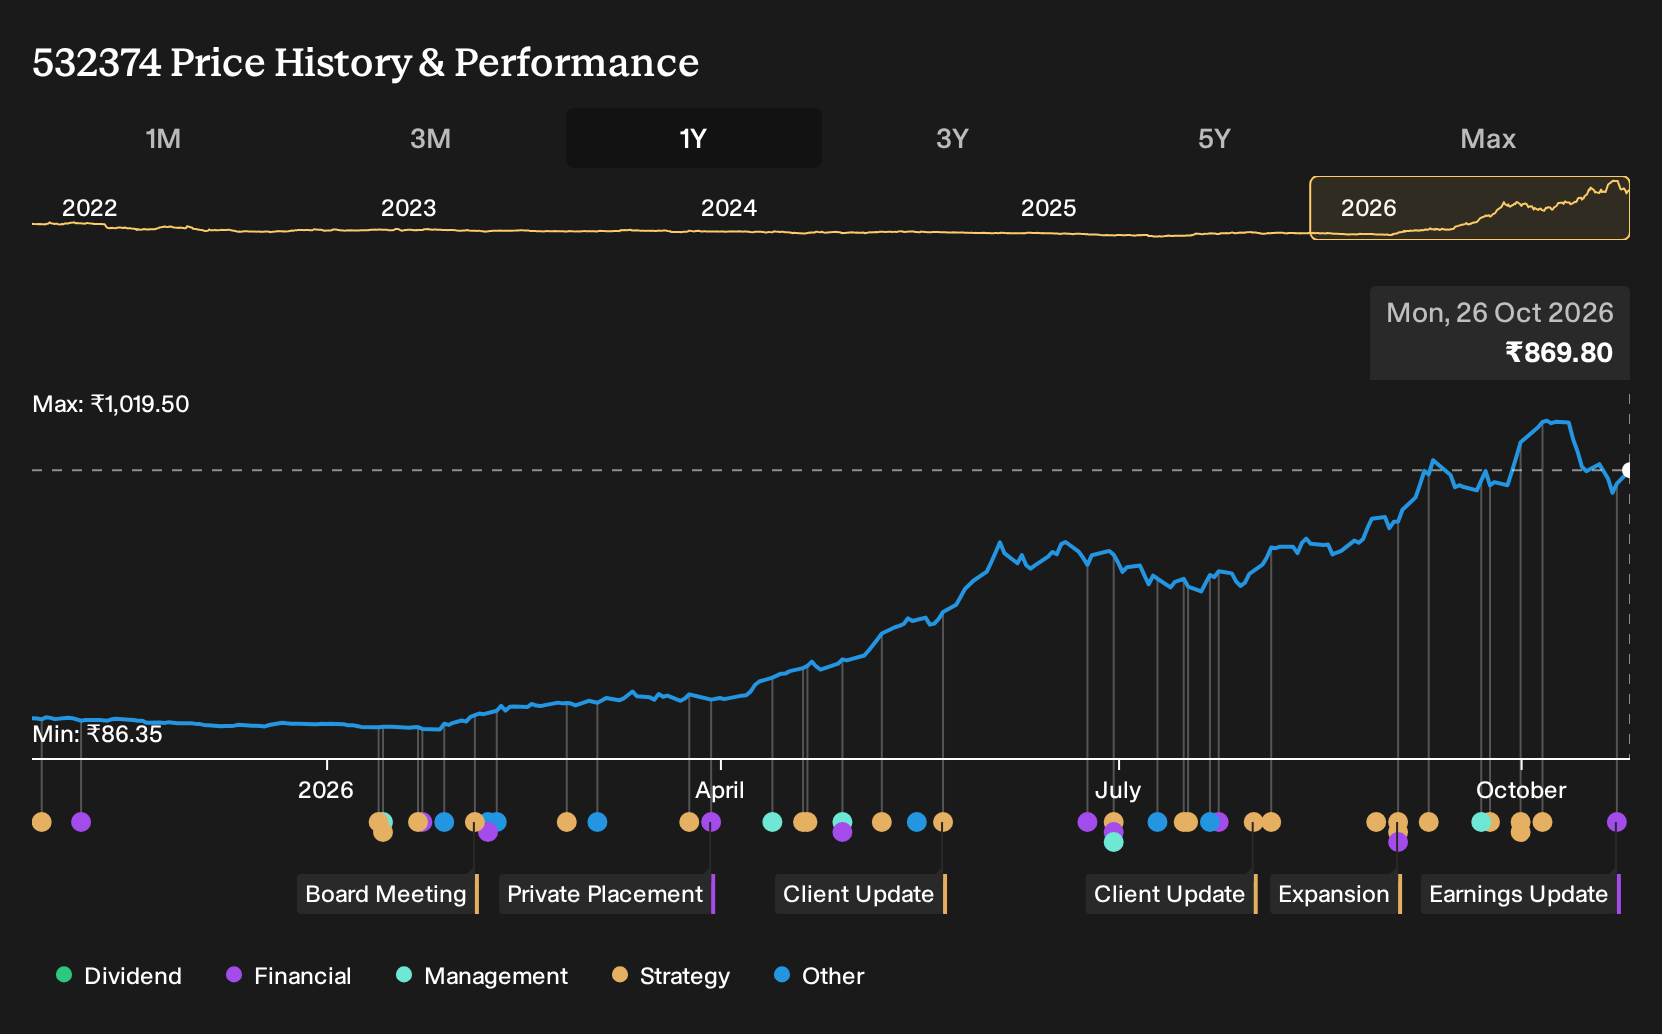
If Sterlite Technologies was on your watchlist rather than in your portfolio over the past year, the outcome may feel brutal. For Sterlite Technologies shareholders, the return over the past year was 627.9%, including dividends. That move now sits next to a huge jump in reported net margin, from 0.4% in Q2 2026 to 20.4% in Q2 2027, and invites a tougher question. What business assumption about fiber demand and high margin data center contracts could have helped you spot this before it showed up in the profit line?
Sterlite Technologies has already moved. See which of 195 high quality undervalued stocks still trade below our estimates.
The Two Sterlite Technologies Stories Investors Had To Choose Between
The shares cost ₹120 at the start of the period, which left Sterlite Technologies investors weighing two very different futures for fiber demand and data centers.
On the bullish side, one camp saw a Fair Value of ₹128, a price implied by assumptions that FTTx, data center builds, and 5G or AI infrastructure would keep lifting fiber orders, helped by long term contracts and a ramp up in global manufacturing.
The cautious narrative pointed to a Fair Value of ₹106, built on worries that wireless and satellite alternatives plus high debt could limit fiber demand, pressure pricing, and leave net earnings more exposed to financing costs and tariff risk.
What The Results Changed For The Sterlite Technologies Debate
The clearest fact was operational. Sterlite Technologies reported Q2 2027 revenue of ₹25,290m against ₹10,340m in Q2 2026, while net income shifted from ₹40m to ₹5,170m and net margin moved from 0.4% to 20.4%. That pattern leans toward the bullish case built on higher margin fiber and data center work. However, one quarter alone does not settle the cautious worries about debt and competition. On balance, the evidence supported the optimistic case.
The episode turned on whether high margin contracts would show up in reported profitability. When you test a similar story elsewhere, track the move in net margin and absolute profit against management claims about product mix, not just the growth in revenue.
What Sterlite Technologies' Price Now Assumes
Sterlite Technologies now trades at ₹870 after a very large gain over the past year, while the selected Narrative’s Fair Value sits above the current price.
The Narrative focuses on data center and enterprise connectivity and argues that today’s price still does not fully reflect Sterlite Technologies successfully scaling that mix while holding margins against input cost pressure.
"The rapid shift in Sterlite Technologies’ mix toward data center and enterprise connectivity, with these segments moving from 1% of revenue in FY 2026 to 21% in Q1 FY 2027 and guided to reach 50% of revenue in the current fiscal, creates room for a higher recurring revenue base and a richer product mix that can support future EBITDA margin and earnings quality beyond what is embedded in simple fiber volume forecasts."
One Narrative disagrees with today's price. → See where this Narrative says Sterlite Technologies should trade
Find Your Own Contrarian Opportunity
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 44% below our estimate - uses a shift from underwear into sports fashion to deepen operating leverage.
- Company 2 - 21% below our estimate - recruits senior lawyers onto a tech platform that shares more fees.
- Company 3 - 33% below our estimate - extends a dairy portfolio through product innovation aimed at higher value nutrition.
Those are three of them. See the full list of 207 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com