


EN
What Lam Research Stock Earnings Guidance Means For Shareholders
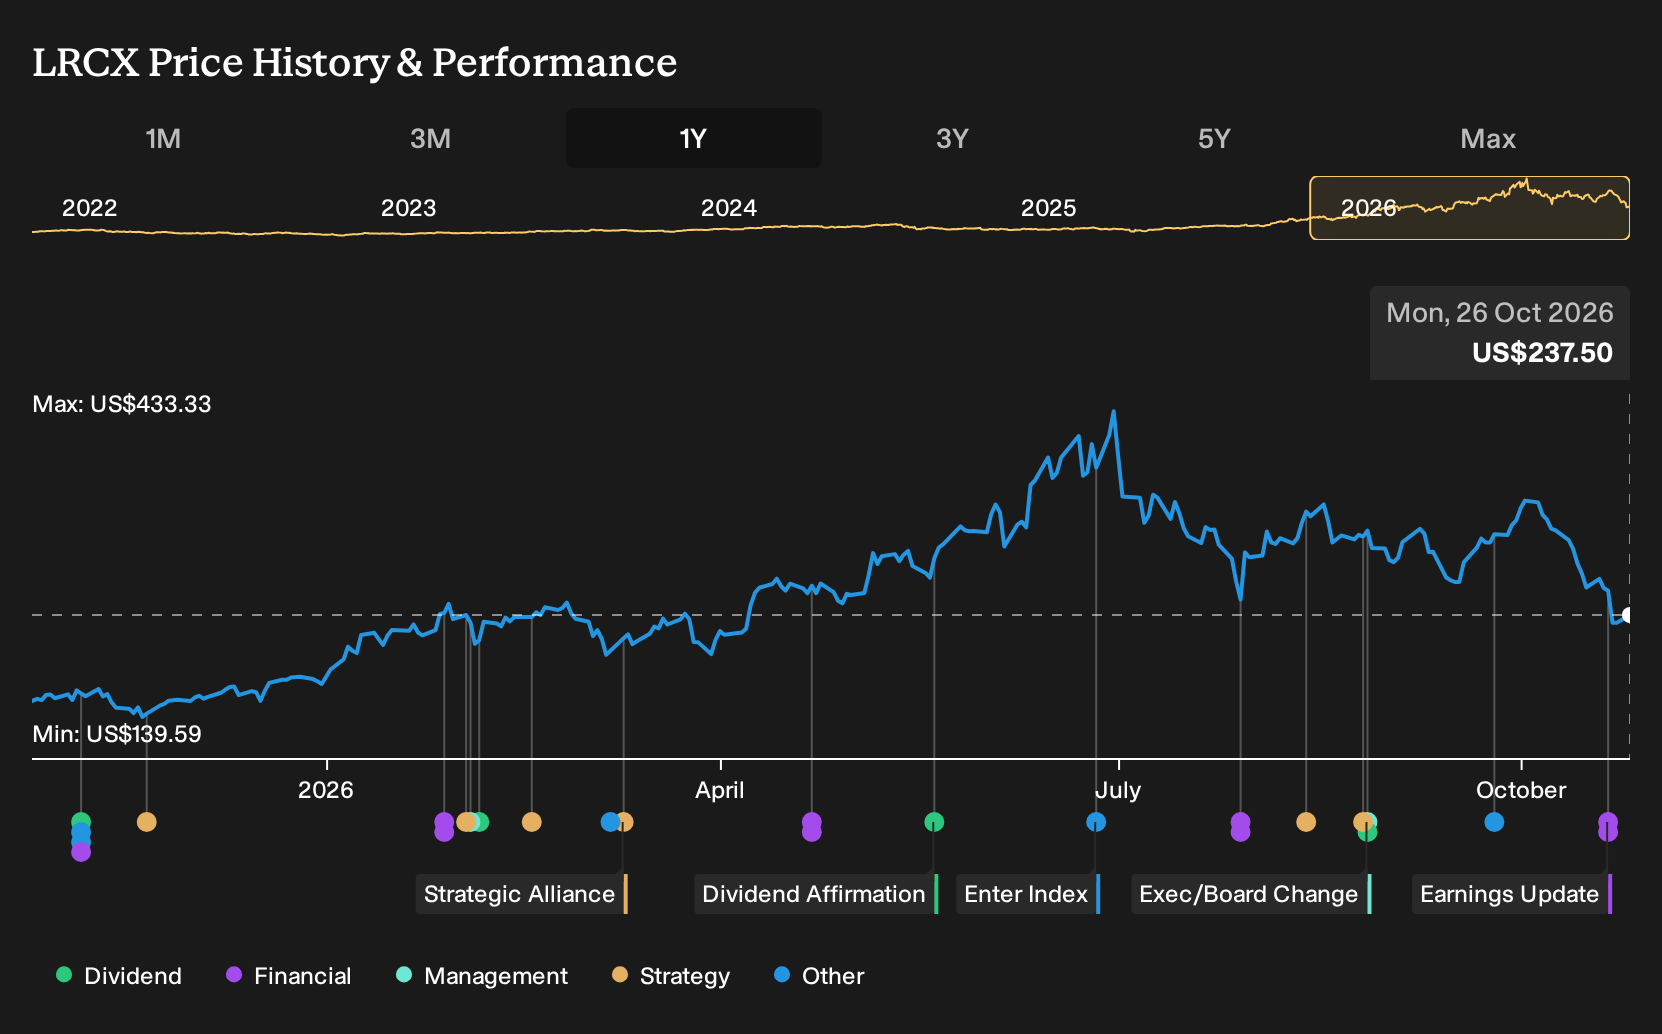
- Lam Research reported first quarter 2026 results in the past, with revenue of US$8.22b, net income of US$2.75b, and diluted EPS of US$2.19 from continuing operations. The company also provided guidance for December quarter revenue of about US$8.60b plus or minus US$400m and net income per diluted share of US$2.33 plus or minus US$0.15.
- The earnings update highlighted strong operational execution despite supply constraints and a softer contribution from China, with management providing quantified forward guidance that helps frame demand visibility and backlog normalization for Lam Research.
- We will look at how Lam Research's investment narrative is shaped by this quarterly revenue and earnings guidance update.
Lam Research Investment Narrative Recap
To own Lam Research, you need to believe that AI driven wafer fab equipment demand, new Tier 1 fabs and 3D chip architectures keep requiring its etch and deposition tools, while export controls and tax headwinds stay manageable. The latest quarter confirms the business is handling high volumes, with revenue of US$8.22b and net income of US$2.75b.
The key short term catalyst is how quickly supply constraints ease so delayed tool shipments convert to revenue, especially as China’s contribution softens and dependency shifts to other regions. The main risk remains export and policy limits on advanced China customers. The October earnings and guidance do not materially change that risk balance.
The clearest data point tied to near term catalysts is Lam Research’s guidance for the December 2026 quarter. Management is signaling expected revenue of about US$8.60b, plus or minus US$400m, and net income per diluted share of US$2.33, plus or minus US$0.15. That range frames how much AI and high performance computing demand is actually turning into equipment shipments.
For you, the relevance is simple. If Lam Research delivers within that band while working through supply bottlenecks and lower China mix, it supports the view that AI linked wafer fab equipment spending and the growing installed base are still feeding the business. If results land toward the low end, it would highlight how export controls and regional project timing can quickly affect reported earnings.
Lam Research's narrative projects US$49.9b revenue and US$18.5b earnings by 2029. This aligns with analyst assumptions for 24.1% yearly revenue growth and an earnings increase of about US$10.1b from US$8.4b today.
Uncover why Lam Research's fair value indicates a 53% potential upside to its current price before that discount to Lam Research closes.
Exploring Other Perspectives
The lowest analysts focus heavily on the risk that Lam Research’s AI related wafer fab equipment demand could cool if customers trim budgets. They were pencilling in about US$46.5b revenue and US$16.6b earnings by 2029, below consensus. That more cautious script could shift after this earnings and guidance update, so compare both narratives for yourself.
Explore 8 other Lam Research fair value estimates, including one that suggests as much as 27% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Lam Research research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Lam Research. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lam Research's overall financial health at a glance.
Looking For More Investment Ideas Beyond Lam Research?
Once you have a view on Lam Research, it can help to widen the lens and compare it with other businesses that share similar quality or risk traits. The Simply Wall St Screener lets you move from one story to a full watchlist of possibilities in a few clicks.
- For investors who care most about balance sheet strength and durable fundamentals, scan our list of solid balance sheet and fundamentals (24 results) to see which companies might handle stress without resorting to dilutive capital raises.
- If valuation discipline matters to you, use the 29 high quality undervalued stocks to surface candidates where pricing and fundamentals appear out of sync.
- Those who want growth potential without extreme downside risk can work through the 30 resilient stocks with low risk scores and build a list of resilient stocks that still leave room for upside.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com