


EN
European Growth Stocks Insiders Are Eager To Own
The European market has recently faced challenges, with the pan-European STOXX Europe 600 Index declining amid rising oil prices and geopolitical tensions. Despite these pressures, growth companies with high insider ownership continue to attract attention as insiders often signal confidence in a company's potential. In this article, we explore three European growth stocks that insiders are eager to own, highlighting their appeal in the current economic landscape.
Top 10 Growth Companies With High Insider Ownership In Europe
| Name | Insider Ownership | Earnings Growth |
| Pharma Mar (BME:PHM) | 12.1% | 39.3% |
| Kuros Biosciences (SWX:KURN) | 23.7% | 65.6% |
| KebNi (OM:KEBNI B) | 13.1% | 110.7% |
| Gold Road International (OB:GOLDR) | 36.7% | 89.8% |
| Envipco Holding (ENXTAM:ENVI) | 15.2% | 101.6% |
| CTT Systems (OM:CTT) | 17.4% | 55.3% |
| Clavister Holding AB (publ.) (OM:CLAV) | 19.4% | 41.1% |
| Bonesupport Holding (OM:BONEX) | 10.6% | 32.3% |
| Bergen Carbon Solutions (OB:BCS) | 11.9% | 52% |
| 2G Energy (XTRA:2GB) | 13.4% | 35.2% |
Here we highlight a subset of our preferred stocks from the screener.
HMS Networks (OM:HMS)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: HMS Networks AB (publ) offers industrial information and communication technology solutions globally, with a market cap of SEK24.82 billion.
Operations: The company's revenue segments include New Industries at SEK874.09 million, Industrial Data Solutions at SEK1.79 billion, and Industrial Networks Technology at SEK1.27 billion.
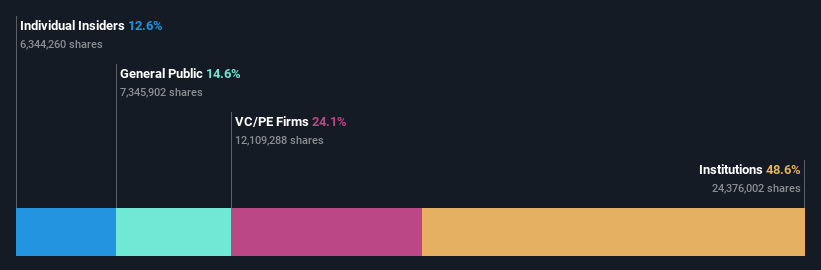
Insider Ownership: 12.3%
HMS Networks shows potential as a growth company with significant insider ownership. Its earnings are projected to grow significantly at 23.24% annually over the next three years, outpacing the Swedish market's 7.6%. Despite high debt levels and a forecasted low return on equity of 20%, its revenue is expected to increase by 10.6% annually, surpassing the local market's decline. Recent earnings reports indicate stable performance with increased sales but unchanged quarterly net income year-on-year.
- Click here to discover the nuances of HMS Networks with our detailed analytical future growth report.
- Our valuation report here indicates HMS Networks may be overvalued.
Rejlers (OM:REJL B)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Rejlers AB (publ) is an engineering consultancy firm operating in Sweden, Finland, Norway, and Abu Dhabi with a market capitalization of approximately SEK3.36 billion.
Operations: The company's revenue segments are Sweden with SEK3.09 billion, Finland with SEK1.46 billion, and Norway (including Embriq) with SEK404.70 million, alongside a group-wide contribution of SEK63.20 million and a segment adjustment of -SEK130.40 million.
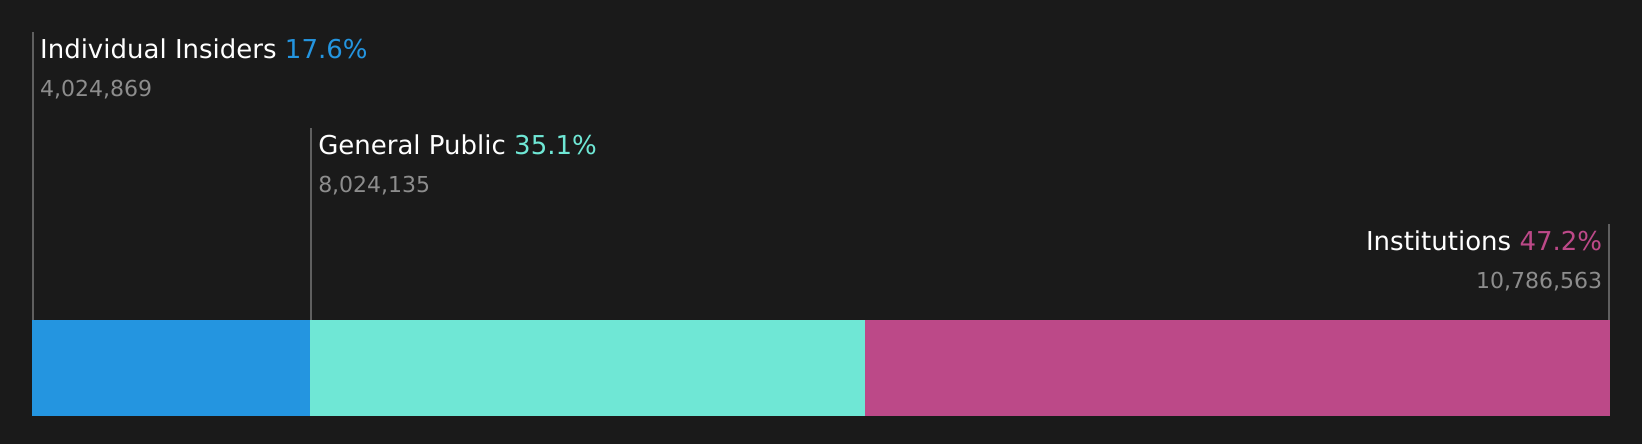
Insider Ownership: 17.6%
Rejlers, with high insider ownership and recent insider buying activity, is poised for significant earnings growth at 24.9% annually over the next three years, surpassing the Swedish market's average. Despite a low forecasted return on equity of 14.6%, Rejlers trades at a substantial discount to its estimated fair value. Recent collaborations with Viscaria and the Swedish Transport Administration highlight its expanding role in infrastructure projects, potentially bolstering long-term growth prospects amidst an unstable dividend history.
- Dive into the specifics of Rejlers here with our thorough growth forecast report.
- The analysis detailed in our Rejlers valuation report hints at an deflated share price compared to its estimated value.
Yubico (OM:YUBICO)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Yubico AB offers authentication solutions for computers, networks, and online services, with a market cap of SEK12.92 billion.
Operations: The company generates revenue primarily from its Security Software & Services segment, amounting to SEK2.12 billion.
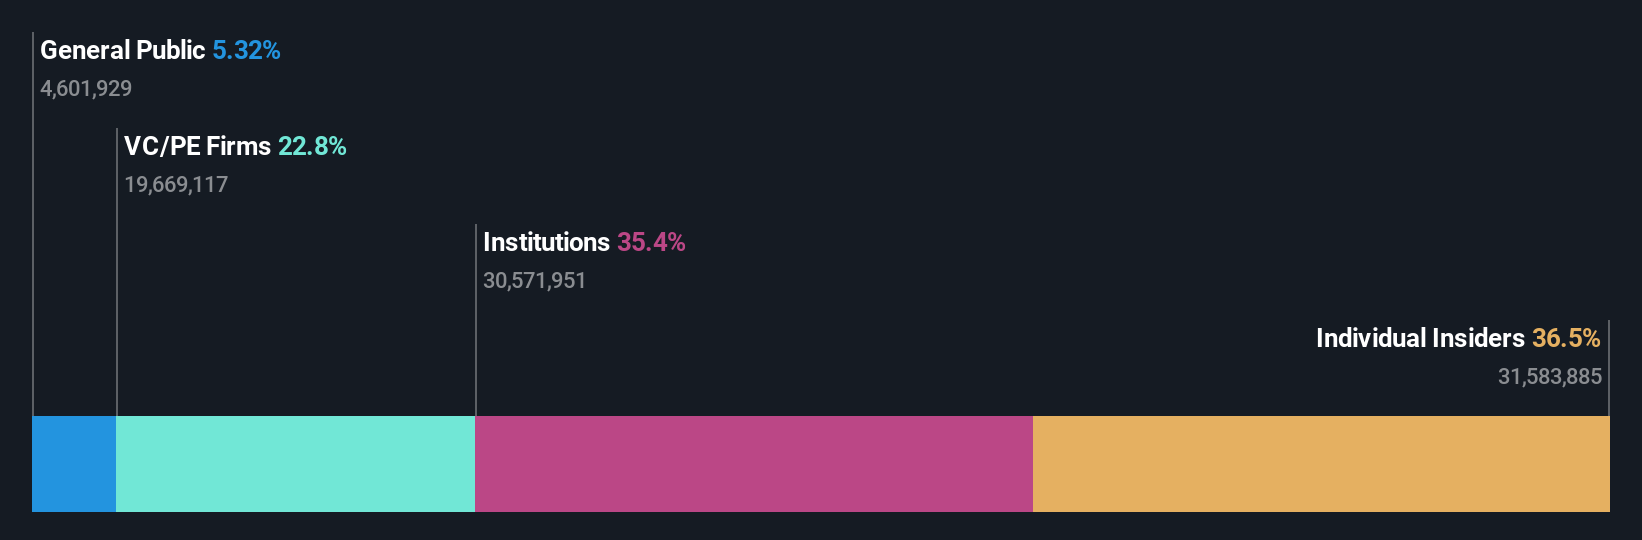
Insider Ownership: 20.3%
Yubico demonstrates strong growth potential with earnings forecasted to grow at 32.7% annually, outpacing the Swedish market. Despite a volatile share price and lower profit margins of 7.1% compared to last year's 10.9%, its revenue is expected to increase by 12.4% per year, surpassing the market's decline. Recent earnings reports show significant improvement, with second-quarter net income rising from SEK 8.9 million to SEK 61.5 million year-over-year, reflecting robust financial performance amidst high insider ownership levels.
- Navigate through the intricacies of Yubico with our comprehensive analyst estimates report here.
- In light of our recent valuation report, it seems possible that Yubico is trading beyond its estimated value.
Summing It All Up
- Gain an insight into the universe of 202 Fast Growing European Companies With High Insider Ownership by clicking here.
- Seeking Other Investments? Rare earth metals are the new gold rush. Find out which 34 stocks are leading the charge.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com