


EN
Generac Holdings (GNRC) Lands Amazon Deal, Is The Upside Already Priced In?
Generac Holdings (GNRC) is back in focus after disclosing a long-term backup power agreement with Amazon that starts shipping in 2027 and 2028, just ahead of the upcoming Q3 earnings update.
The Amazon agreement hits just as Generac Holdings trades at US$189.23, with the share price up 34.11% year to date but the 1 year total shareholder return slightly negative at 0.62%. This points to strong recent momentum after a tougher prior stretch.
Scan how Generac Holdings compares with other potential beneficiaries of grid reliability and backup power demand by reviewing the hand picked 42 power grid technology and infrastructure stocks now in focus.
Bulls point to the Amazon deal and recent momentum, while bears flag the patchy multi year return record. Which side does Generac Holdings valuation actually support as you weigh the current price?
Most Popular Narrative: 35% Undervalued
Generac Holdings most followed narrative points to a fair value near $289.56, well above the recent $189.23 close. This puts the Amazon contract and data center backlog at the center of the debate.
Accelerating AI driven build outs of hyperscale and colocated data centers are now supported by Generac Holdings having about US$450m of expected 2026 data center revenue, a US$1.6b dedicated backlog, and multiple multiyear hyperscale agreements including an Amazon deal projected at about US$2.4b of deliveries in 2027 to 2028. Together, these factors point to a multi year runway for higher C&I revenue and operating leverage.
See why 30 investors see Generac Holdings as 35% undervalued.
That story leans on a 9.75% discount rate and assumes Generac Holdings can convert a larger fixed cost base into stronger profitability as utilization improves, particularly in data centers and commercial and industrial energy solutions. At the same time, the narrative flags capital intensity, residential sensitivity to outages, and the recent earnings decline as live risks that could challenge those expectations.
Result: Fair Value of $289.56 (UNDERVALUED)
Still, the bullish Generac Holdings story depends on data center demand actually absorbing new capacity, as well as on residential buyers looking past softer outage activity and affordability pressure.
Find out about the key risks to this Generac Holdings narrative.
Another View: Generac Holdings Through The P/E Lens
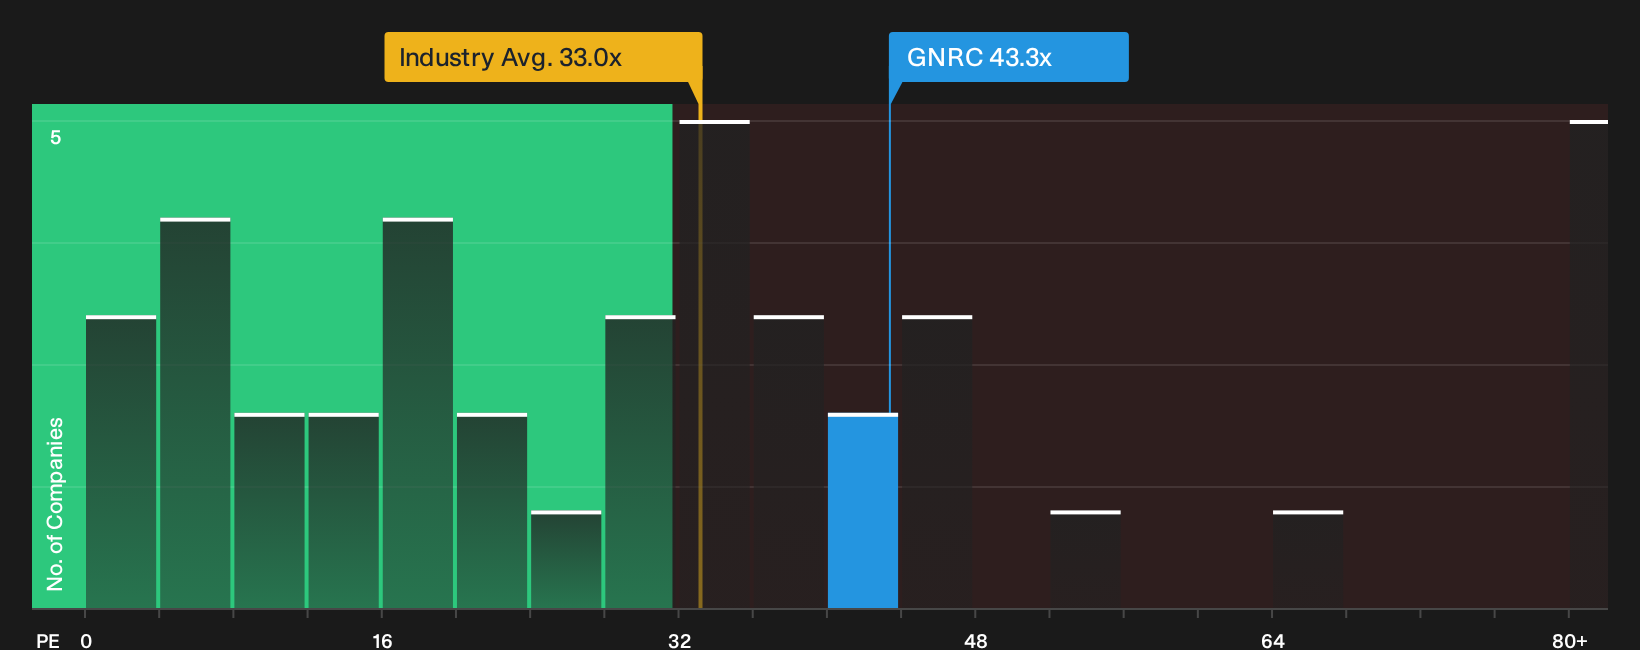
The story shifts when you swap cash flow models for a simple earnings multiple. Generac Holdings trades on a P/E of 43.3x, which is higher than the US Electrical industry at 33x, peers at 29.5x, and even its own 39.1x fair ratio. That premium raises the question of how much good news is already in the price.
To see how that earnings multiple stacks up against the broader peer group and the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of optimism runs through this Generac Holdings story, yet the real test is how the numbers stack up for you today. Act while the market is debating the outlook, and carefully evaluate the upside case against the 3 key rewards
Looking For More Generac Holdings Investment Ideas?
If Generac Holdings is only one piece of your portfolio puzzle, widen the lens now so you are not late to other opportunities lining up.
- Spot potential mispricing early by scanning a focused group of 29 high quality undervalued stocks that pair quality fundamentals with compressed expectations.
- Strengthen portfolio resilience by filtering for a list of solid balance sheet and fundamentals (24 results) that can better handle shocks to earnings or credit conditions.
- Get ahead of the crowd by tracking a curated set of 21 high quality undiscovered gems before wider attention starts to price in their qualities.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com