


EN
How Investors Are Reacting To Globe Life (GL) Updated Growth Guidance
- Globe Life updated its outlook, issuing full year 2026 and 2027 guidance that details expected premium trends, earnings per share ranges, and sales growth targets across life and health segments and distribution channels.
- The guidance breaks out differing growth expectations for Liberty National, Direct to Consumer, United American, and Family Heritage, giving investors a clearer view of which units management expects to drive future premium and earnings contributions.
- We will now explore how Globe Life's multiyear premium and EPS guidance shapes the existing investment narrative around health and life growth.
Compare Globe Life's guidance playbook with other insurers targeting similar premium and earnings momentum by scanning our curated list of 30 resilient stocks with low risk scores across the sector.
Globe Life Investment Narrative Recap
To own Globe Life, you need to be comfortable with a slow and steady insurance story where premium growth, underwriting discipline, and capital efficiency matter more than headline excitement. The new 2026 and 2027 guidance reinforces that view, with management outlining 6% to 8% total premium growth and 7% midpoint EPS growth as the core path forward.
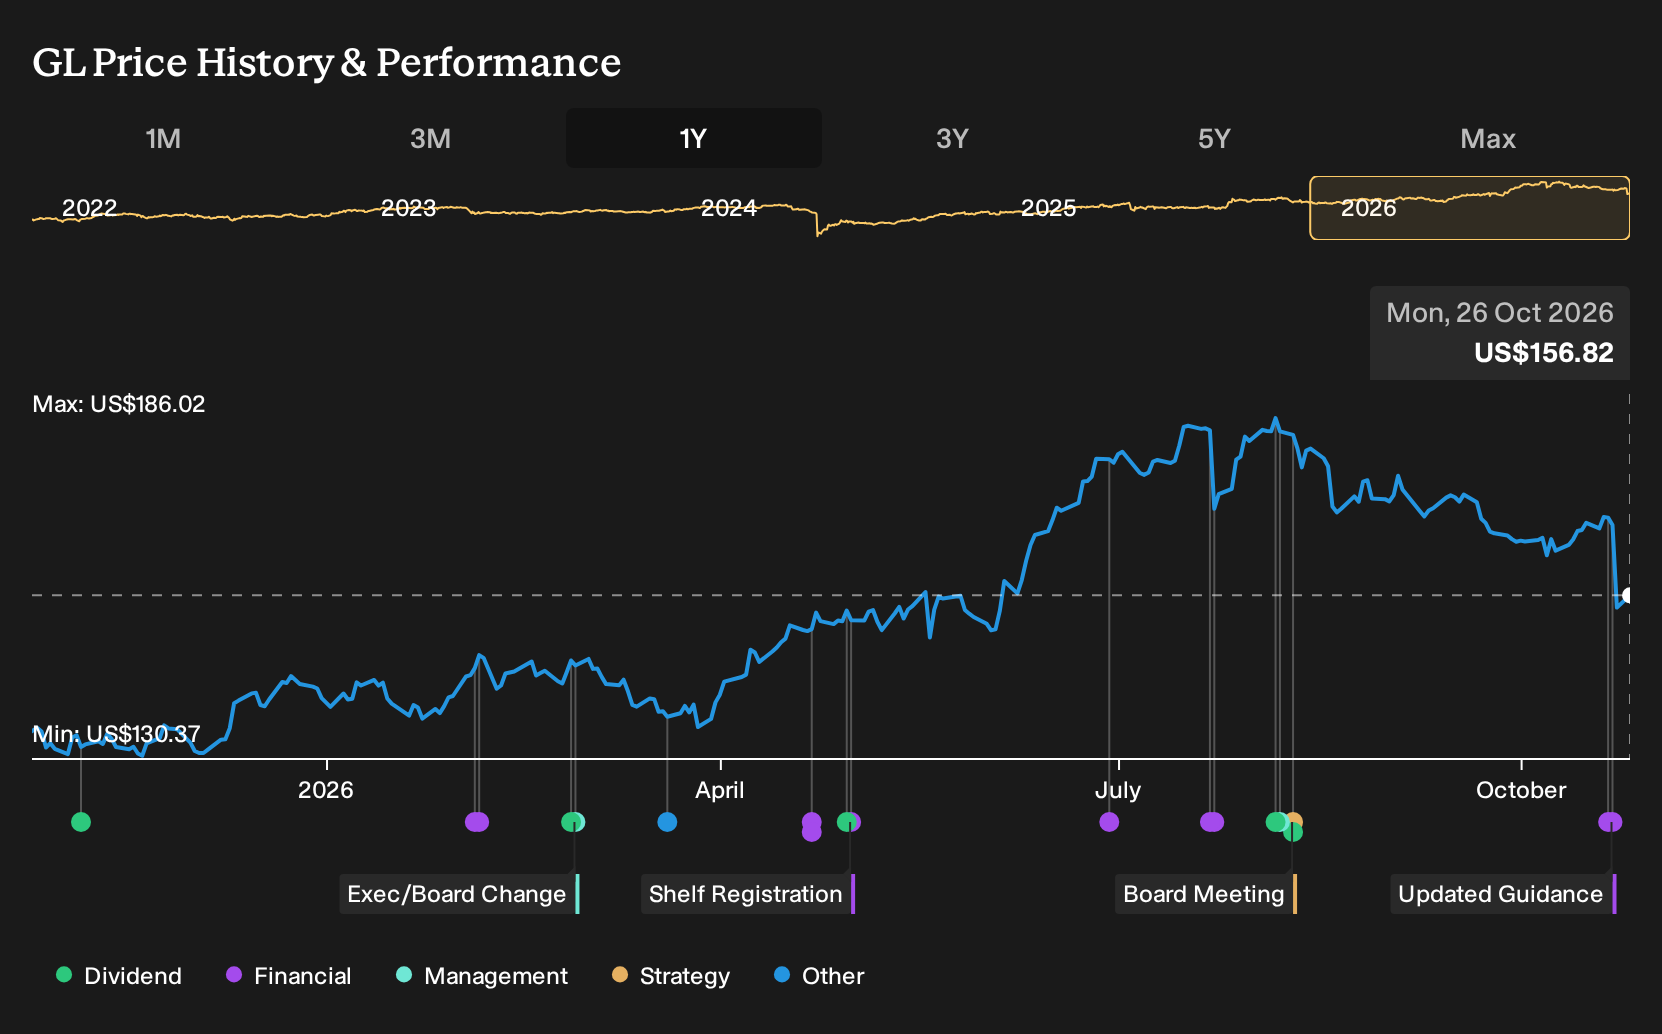
The key short term catalyst is simple, consistent execution against that guidance after earlier EPS and book value misses shook confidence. The biggest risk is still health claims volatility and direct to consumer softness. This latest outlook clarifies the destination, but it does not remove those pressure points.
The most relevant update for that thesis is the October 22 guidance detail. Globe Life now expects life premium revenue growth of 2% to 4% and health premium revenue growth of 13% to 15% in 2027, with different sales ranges by channel, such as low double digit growth at Liberty National and low single digit at Direct to Consumer.
For you as a shareholder, the question is whether the business can hit a US$16.10 to US$17.10 EPS range while keeping claim ratios and acquisition costs in check across Liberty National, United American, Family Heritage, and direct channels. Execution against those segment level goals is likely to drive how the existing risks and catalysts actually play out.
Globe Life's narrative projects US$7.5b revenue and US$1.4b earnings by 2029, based on analyst estimates that assume 6.0% yearly revenue growth and an earnings increase of about US$200m from US$1.2b today.
Uncover how Globe Life's fair value indicates a 20% potential upside to its current price, which could narrow quickly as confidence in the guidance rebuilds.
Exploring Other Perspectives
One alternate view focuses on Globe Life’s health margin pressure rather than the growth targets in the new guidance. The most cautious analysts already worked off lower expectations, with revenue modeled at about US$7.2b and earnings of roughly US$1.3b by 2029. Those forecasts came before this update, so opinions may change as guidance is digested.
Explore 3 other Globe Life fair value estimates, including one that suggests it could be worth just $185.64.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Globe Life research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Globe Life. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Globe Life's overall financial health at a glance.
Looking for more Globe Life style investment ideas?
If Globe Life's steady premium and earnings profile appeals to you, it can help to compare it with other businesses that share similar risk or balance sheet characteristics. The Simply Wall St Screener lets you quickly filter for different traits so you can build a watchlist that matches how you like to invest.
- If you want resilient businesses where risk indicators look more contained, start with our curated set of 30 resilient stocks with low risk scores that aim to keep downside surprises in check.
- If value is your priority and you are hunting for quality on sale, scan the 29 high quality undervalued stocks that combine stronger fundamentals with prices that may not fully reflect them.
- If reliable cash returns appeal to you, focus on income opportunities by reviewing the 5 dividend fortresses that pair higher yields with more durable payout profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com