


EN
3 Great Copper Stocks To Own In October 2026
China’s industrial profits recently rose 14.4%, helped by a manufacturing boom tied to artificial intelligence and higher commodity prices. That kind of broad factory demand leans heavily on copper, which sits at the centre of power grids, data centres and electric machinery. If you believe this build out has legs, the most resilient low cost copper producers may warrant closer attention. This article walks through three standouts from that group.
The stocks highlighted below are only a small sample, and the full screen surfaced 13 more copper producers with equally compelling stories that do not fit into this brief article. If you want to go straight to the source, use the Top Copper Stocks screener to identify, compare and analyze your highest conviction ideas.
China Nonferrous Mining (SEHK:1258)
Overview: China Nonferrous Mining runs copper and cobalt mining, processing and smelting operations in Zambia and the DRC, supplying refined copper products worldwide.
Operations: The group generates about US$1.5b from leaching and US$2.5b from smelting, with sales concentrated in Singapore, Switzerland, Hong Kong and Africa.
Market Cap: HK$48.9b
China Nonferrous Mining offers direct exposure to African copper supply that is used in grids, data centres and electric machinery, with earnings and margins already moving higher alongside copper prices. Investors focused on the tight copper market may watch how pricing power holds up if a single key assumption breaks.
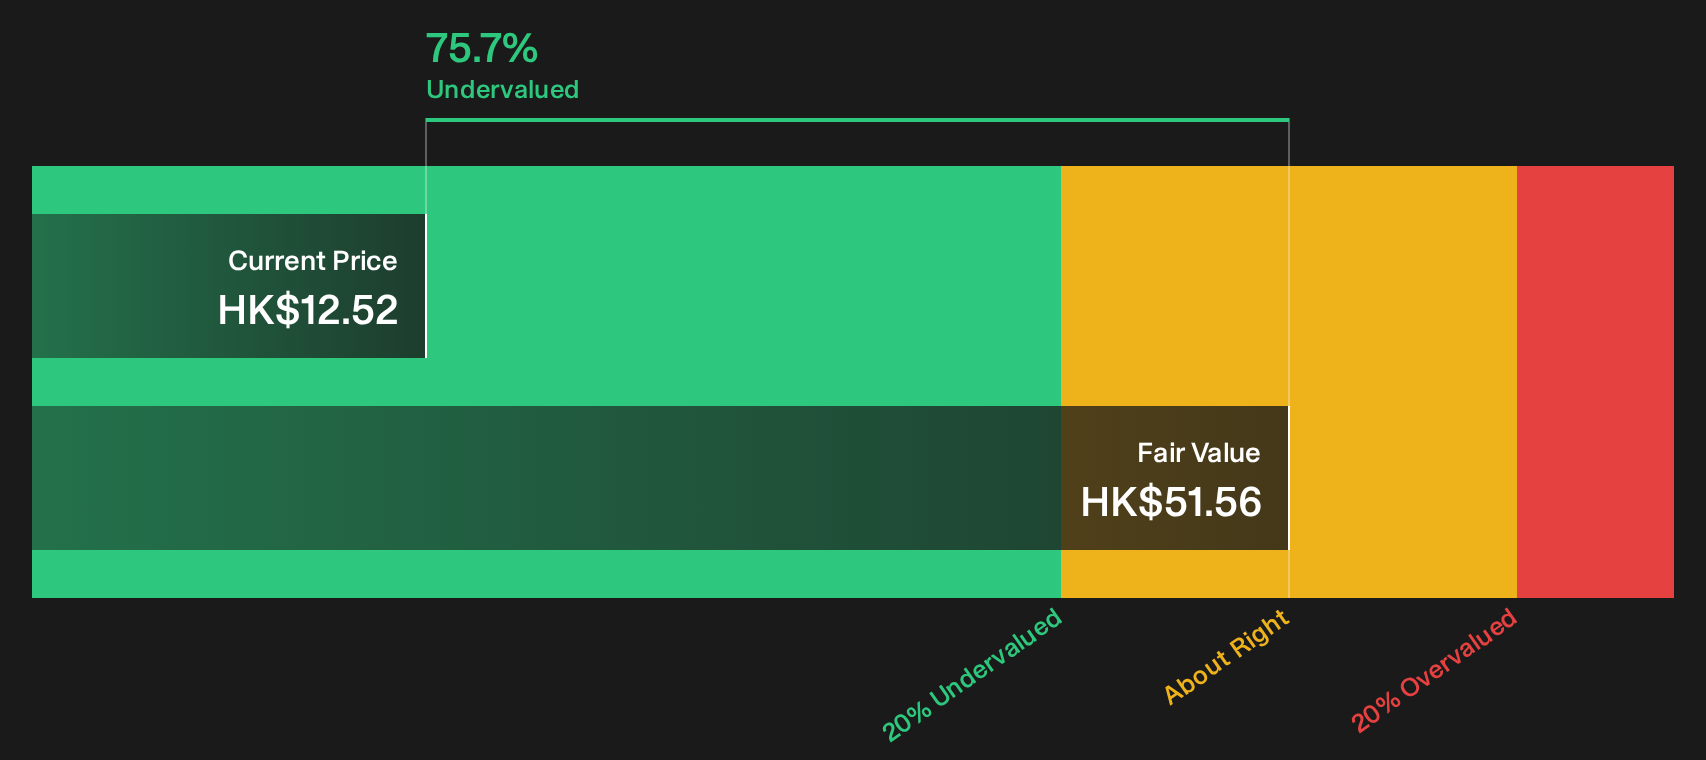
If that assumption proves shaky, the DCF valuation analysis for China Nonferrous Mining shows where China Nonferrous Mining’s pricing power, cash flows and copper exposure could start to decouple.
Aurubis (XTRA:NDA)
Overview: Aurubis refines copper concentrates and recycled scrap into cathodes, copper rod and specialty products, while also processing other metals and by products.
Operations: Aurubis reports about €22b from Custom Smelting & Products and €5.6b from Multimetal Recycling, with a smaller €516m segment adjustment.
Market Cap: €5.9b
For the Top Copper Stocks theme, Aurubis matters because its copper refining and recycling network feeds the wires, motors and grids that power electrification, even though a meaningful slice of income still comes from non copper metals and sulfuric acid.
"The push to expand multimetal recycling and cathode capacity through projects such as Complex Recycling Hamburg and the Pirdop tankhouse aims to lift EBITDA by about €260 million overall. Yet the timing of full utilisation and payback on the €1.4 billion of CapEx that is now largely spent remains ahead of Aurubis and can influence whether future revenue and EBITDA justify the current valuation."
For investors watching Aurubis, a single tension around how future copper-linked earnings balance against this already-committed investment could prove decisive.
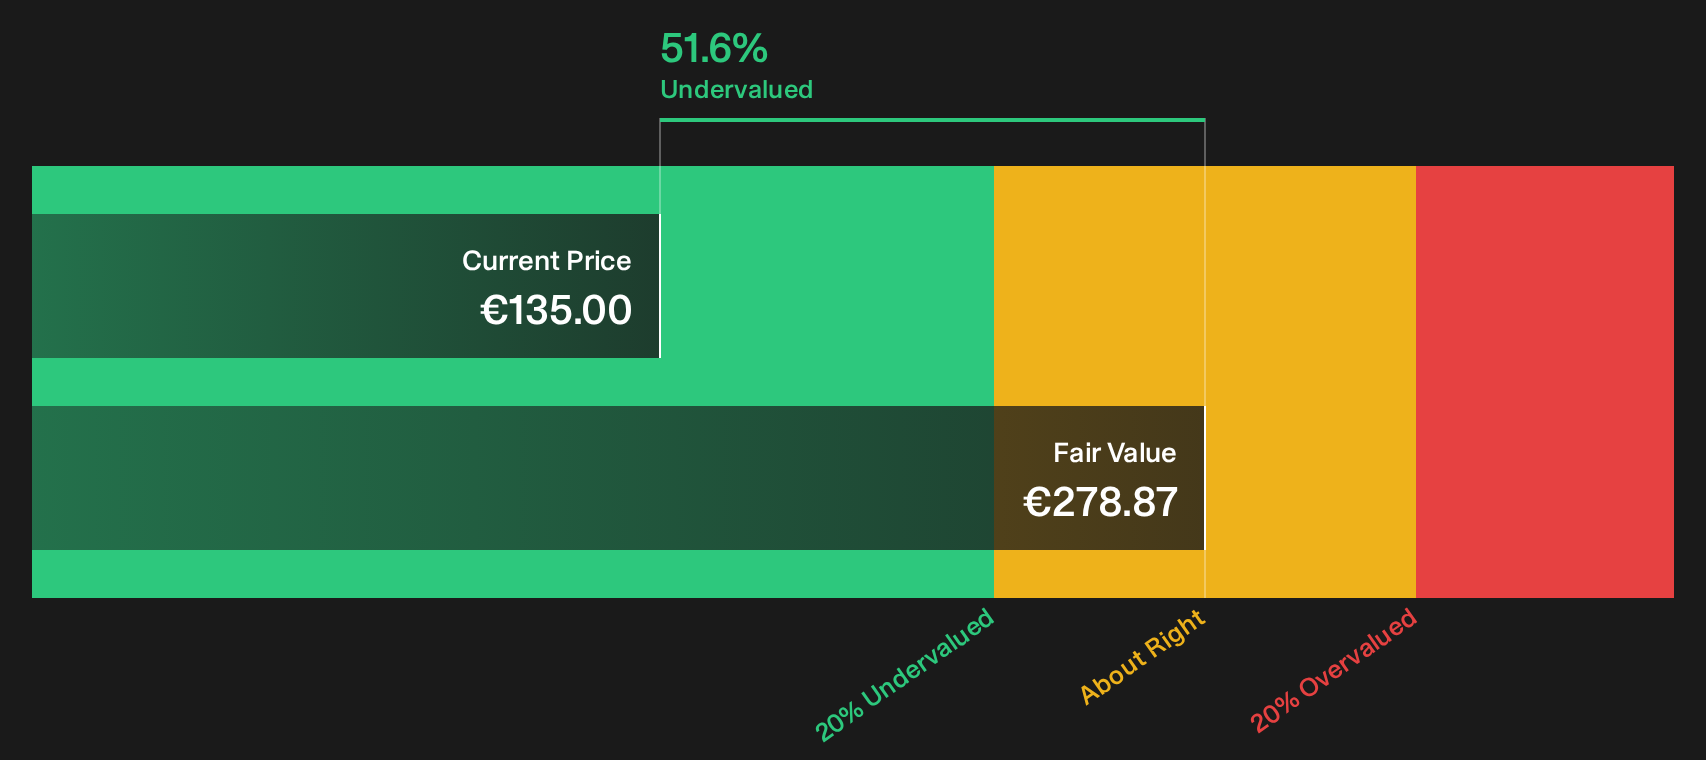
That future balance depends on more than one project, and the full narrative for Aurubis explains how Aurubis could turn today’s heavy buildout into either accelerating copper earnings or a stalled rerating.
Antofagasta (LSE:ANTO)
Overview: Antofagasta is a London headquartered miner that runs large Chilean copper operations supplying cathodes and concentrates for global electrification and AI build outs.
Operations: Antofagasta generates about $4.6b from Los Pelambres, $3.6b from Centinela, $1.0b from Antucoya and $172 million from its Transport Division.
Market Cap: £31.3b
Antofagasta matters for the Top Copper Stocks theme because its low cost mines ship the copper units that power grids, data centres and electric fleets at scale, with the investment case now tightly linked to how efficiently those assets turn ore into cash.
"Record EBITDA margins of around 60% to 63% and strong operating cash flow give Antofagasta more internal funding capacity than many peers."
What that cash ultimately delivers for Antofagasta’s future copper volumes and unit costs hinges on how one crucial operational variable plays out.
That hinges on how that operational swing factor plays out, and the full narrative for Antofagasta maps where Antofagasta’s copper engine could accelerate, stall or quietly decouple from peers.

Seeking Alternatives Before Momentum Flies
Fresh ideas can be identified early, gaps can close quickly and price momentum can accelerate before the broader market reacts. Scan what is still under the radar for now and consider potential opportunities promptly.
- Spot cash rich balance sheets before they appear on many watchlists by filtering for a list of solid balance sheet and fundamentals (207 results) that still look reasonably priced.
- Seek a combination of potential income and resilience by zeroing in on 224 dividend fortresses built to keep paying when markets drop or sentiment swings.
- Track early grid and infrastructure activity by focusing on 42 power grid technology and infrastructure stocks before transmission and stability spending is widely covered in headlines.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com