


EN
Undiscovered Gems in Asia to Explore This October 2026
As of October 2026, the Asian markets have been navigating a complex landscape marked by global economic shifts and regional developments. With small-cap stocks gaining traction amid broader market rotations, investors are increasingly looking towards undervalued opportunities in Asia's dynamic economies. In this environment, identifying stocks with strong fundamentals and growth potential becomes crucial for those seeking to explore promising ventures.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Eurocharm Holdings | 2.66% | 3.48% | 7.39% | ★★★★★★ |
| AMPAK Technology | 34.99% | -10.73% | -19.52% | ★★★★★☆ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Silvery Dragon Group Tianjin | 25.01% | 2.55% | 25.62% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Primo Global Holdings | 64.63% | 9.93% | 28.27% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
| Ta Tun Electric Wire & Cable | 70.16% | 6.67% | 33.41% | ★★★☆☆☆ |
Let's review some notable picks from our screened stocks.
HANA Micron (KOSDAQ:A067310)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: HANA Micron Inc. offers semiconductor back-end process packaging solutions in South Korea and has a market capitalization of approximately ₩2.02 trillion.
Operations: The primary revenue stream for HANA Micron Inc. is Semiconductor Manufacturing, contributing approximately ₩3.26 billion, followed by Semiconductor Material at ₩333.01 million. The company also engages in New Technology Business financing, generating around ₩1.26 million in revenue.
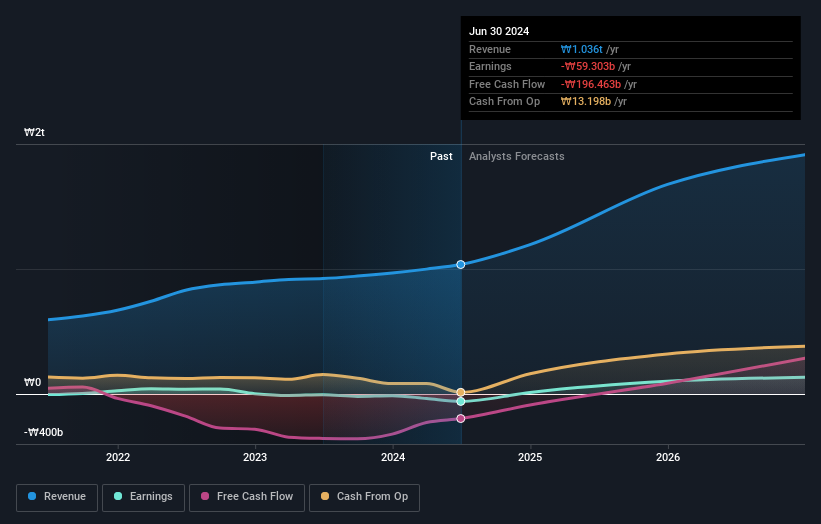
HANA Micron, a notable player in the semiconductor sector, has demonstrated impressive performance with earnings skyrocketing by 3074% over the past year, far outpacing industry growth of 72%. The company trades at a significant discount, approximately 84% below its estimated fair value. Recent financials reveal substantial sales growth to KRW 683.16 billion for Q2 2026 from KRW 340.18 billion the previous year and net income rising sharply to KRW 71.73 billion from KRW 3.21 billion. Additionally, a recent transaction saw IMM Credit and Solutions acquiring a stake valued at about ₩100 billion, highlighting investor interest in this promising entity.
- Click here to discover the nuances of HANA Micron with our detailed analytical health report.
Gain insights into HANA Micron's historical performance by reviewing our past performance report.
PC Partner Group (SGX:PCT)
Simply Wall St Value Rating: ★★★★★★
Overview: PC Partner Group Limited is an investment holding company engaged in the design, development, manufacturing, and sales of computer electronics with a market capitalization of SGD1.02 billion.
Operations: PC Partner Group generates revenue primarily from the design, manufacturing, and trading of electronics and PC parts, amounting to HK$14.05 billion.
PC Partner Group, a tech player in Asia, showcases strong financials with earnings growth of 147.9% over the past year, outpacing the industry average of 41.6%. The company has reduced its debt to equity ratio from 40% to 38.3% over five years and maintains more cash than total debt, highlighting robust fiscal health. Trading at a substantial discount of 73.5% below fair value estimates suggests potential upside for investors seeking undervalued opportunities. Recent inclusion in the S&P Global BMI Index and an interim dividend increase further underscore its growing market presence and shareholder-friendly approach.

Smartsens Technology (Shanghai) (SHSE:688213)
Simply Wall St Value Rating: ★★★★★☆
Overview: Smartsens Technology (Shanghai) Co., Ltd. is a company specializing in the development and production of semiconductor integrated circuit chips, with a market capitalization of CN¥43.67 billion.
Operations: The company's primary revenue stream comes from semiconductor integrated circuit chips, generating CN¥9.84 billion.
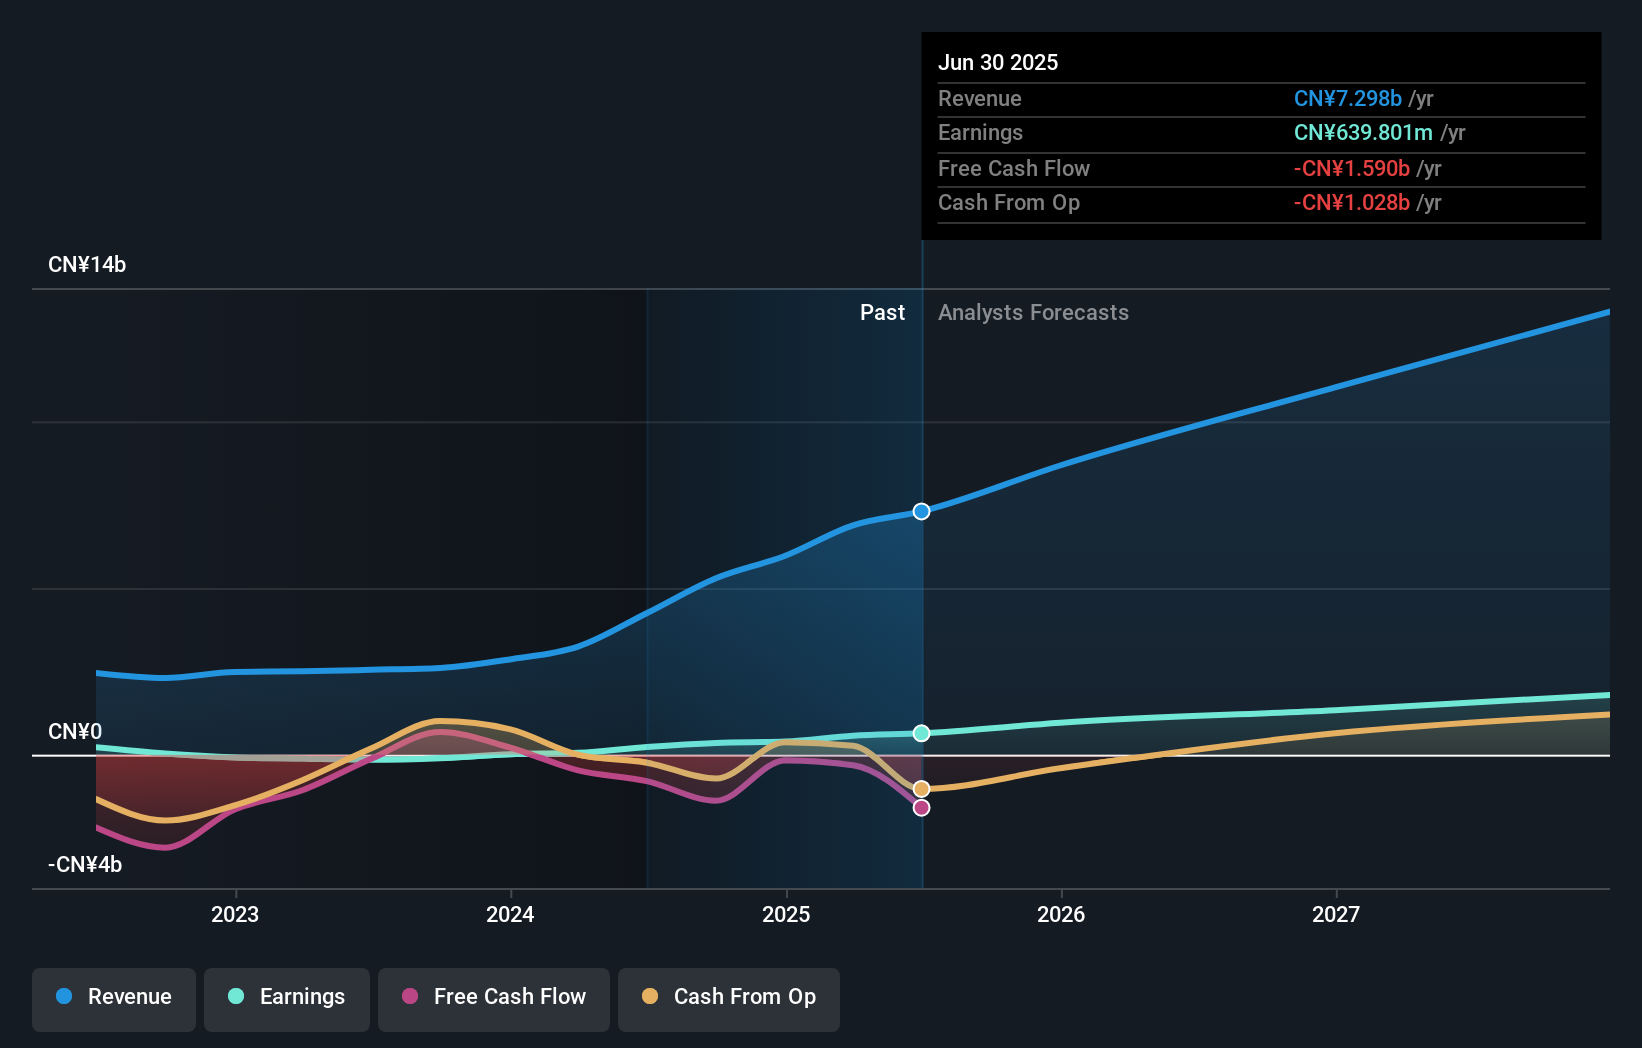
SmartSens Technology, a notable player in the semiconductor industry, has been making waves with its innovative camera module solutions. The company's earnings surged by 77% over the past year, outpacing the industry's 20% growth rate. Trading at nearly half of its estimated fair value, SmartSens appears undervalued relative to peers. Its net debt to equity ratio stands at a satisfactory 34.8%, although this has risen from 27.3% five years ago to 71.6%. Recent product launches and strategic investments signal promising momentum for future growth in automotive imaging technology and beyond.
Turning Ideas Into Actions
- Click through to start exploring the rest of the 130 Asian Undiscovered Gems With Strong Fundamentals now.
- Invested in any of these stocks? Simplify your portfolio management with Simply Wall St and stay ahead with our alerts for any critical updates on your stocks.
- Unlock the power of informed investing with Simply Wall St, your free guide to navigating stock markets worldwide.
Searching for a Fresh Perspective?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com