


EN
Why British American Tobacco Rose Even Though Profit Fell
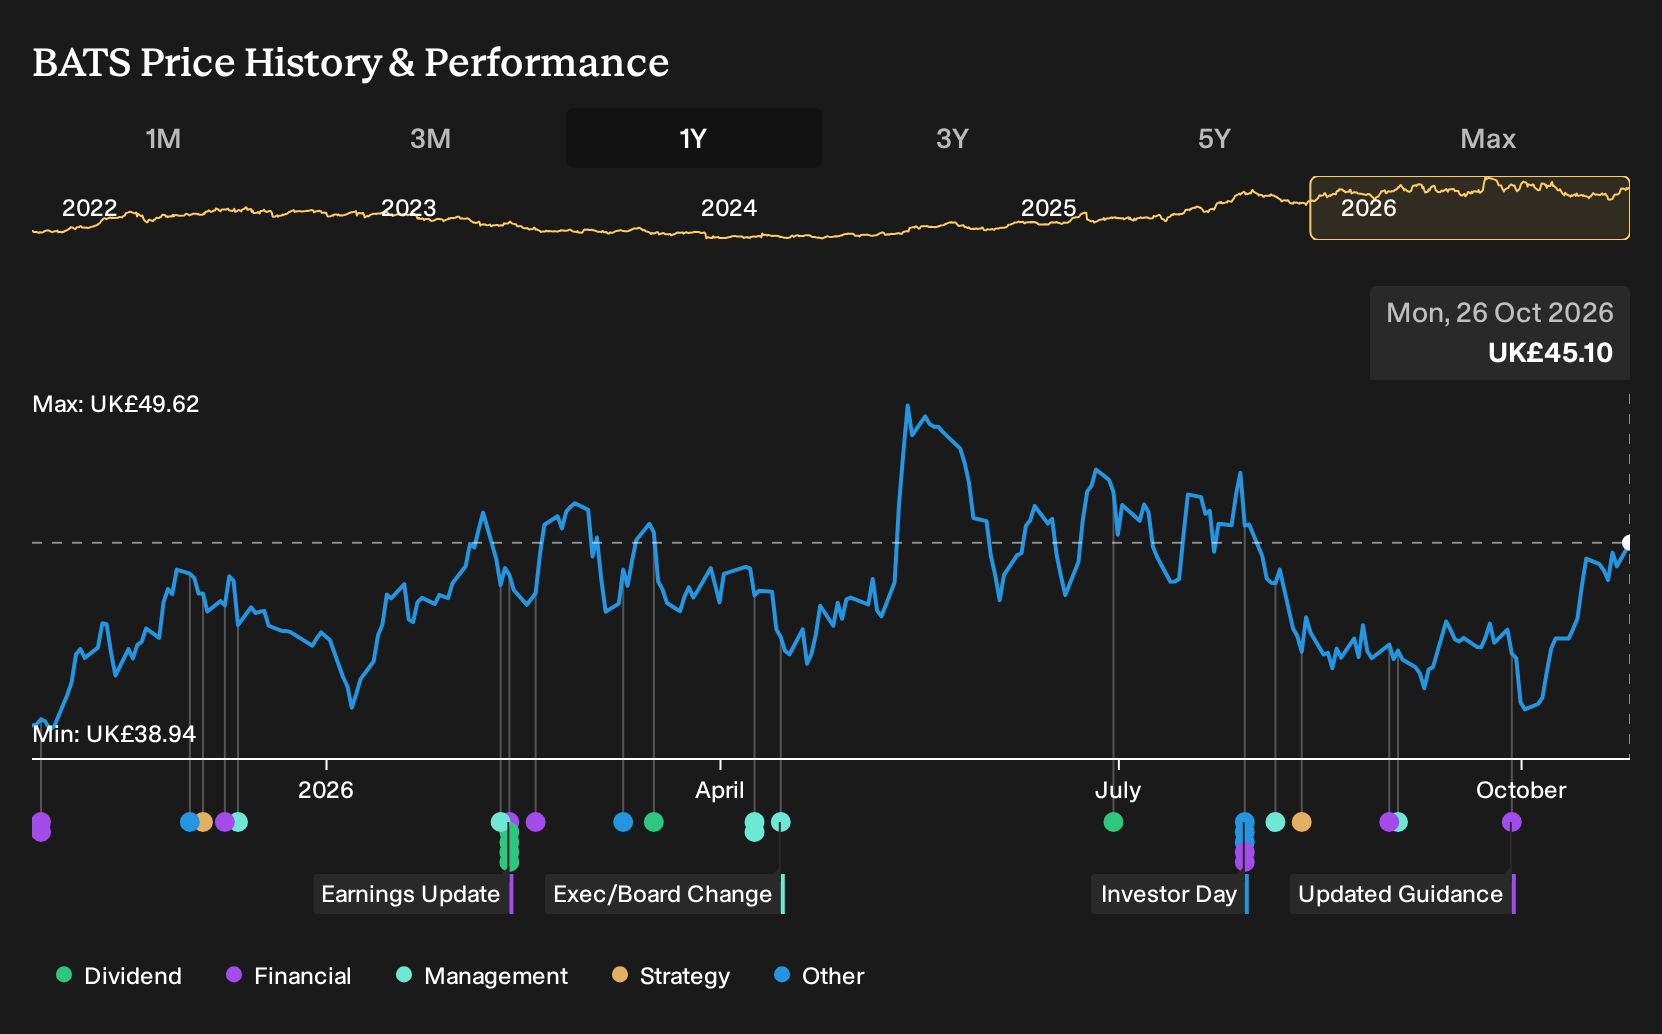
If British American Tobacco was on your watchlist rather than in your portfolio, the return may sting. Investors who held British American Tobacco over the past year are up 22.1%, including dividends. That outcome sits between bullish hopes for emerging market new-category growth and bearish worries about regulation and ESG-driven selling. If you rewind to late October 2025, what might have signalled that the bet on reduced-risk products and digital efficiency could outweigh declining combustibles?
If the move has made British American Tobacco harder to judge, start where the gap is still open and scan 10 high quality undervalued stocks.
The Two British American Tobacco Stories Investors Were Weighing
The shares cost £38.99 at the start of the period, and British American Tobacco sat between two very different but plausible stories about where the business could head next.
On the optimistic side, the bull Narrative suggested the shares were worth a Fair Value of £42.67, the price implied if its assumptions played out, with revenue growing 2.4% a year and profit margins reaching 30.3% as reduced-risk products and digital programmes scaled.
The bear Narrative pointed to a Fair Value of £26.5, built on concerns that tougher global regulation and shifting norms around nicotine could curb prospects even if margins rose and earnings reached £8.2b by 2028.
What The Results Changed For The British American Tobacco Story
British American Tobacco’s Fit2Win restructuring, including 5,500 job cuts and £600m targeted savings by 2028, lined up cleanly with the bull case that leaned on cost programmes and digital efficiency. However, the reported numbers told a tougher story. Revenue moved from £12,069m in H1 2025 to £12,235m in H1 2026, while net income fell and net margin dropped from 37.2% to 25.8%. The evidence cut both ways.
The useful takeaway is clear. When a thesis leans on efficiency and higher profitability, do not stop at new cost plans or tech partnerships. Track the reported net margin and absolute profit to see if they actually move in the direction the story needs.
What British American Tobacco’s Price Now Assumes
British American Tobacco now trades at £45.1, while the selected Narrative’s Fair Value sits below the current price. That assessment reflects pressure in cigarettes, new vaping taxes and weakness in heated products, set against progress in smokeless categories and cost savings.
The question for anyone paying today’s level is what must keep going right for £45.1 to make sense. The specific hurdle is whether smokeless and New Categories can grow fast enough, for long enough, to offset heated product softness and cigarette volume pressure.
"Although British American Tobacco reports smokeless products now account for 19.8% of revenue and New Category revenue grew 18% with a 55% contribution increase, the company still needs much faster progress in heated products where revenue fell around 12% to 13% in the first half of 2026 and is guided to a low double digit decline for the year."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Another Habit Investors Might Consider
British American Tobacco is one version of a habit-driven business. Investors are paid to wait while customers repeat familiar choices.
There is a different kind of repeat purchase story nearby. Instead of nicotine, it revolves around drinks and snacks in fridges, offices and stadiums.
This other group focuses on steady cash generation and regular shareholder returns. Management prioritises funding operations, then maintaining distributions, then considering buybacks.
If you care about resilience of everyday demand rather than product risk alone, that pattern may interest you. The real question is how that trade off fits your portfolio.
One Narrative has already put a figure on it. → Uncover the company trading 32% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com