


EN
How Nevada Growth Plans Will Impact i-80 Gold Stock Investors
- i-80 Gold updated its Nevada development plan, confirming progress on the Lone Tree processing hub, Archimedes underground, and the Mineral Point open pit, with capital spending, permitting, and refurbishment timing tracking its December 2025 engineering study.
- The decision to prioritize Mineral Point, described as hosting one of the largest undeveloped bulk-mineable oxide gold-silver resources in Nevada, reshapes i-80 Gold's long-term production mix and capital allocation.
- The next step is to see how i-80 Gold's investment narrative shifts as Lone Tree moves toward in-house processing and away from toll milling.
i-80 Gold Investment Narrative Recap
To own i-80 Gold, you need to believe the Nevada hub and spoke plan can move from engineering slides to reliable tonnes and recoveries. The short term focus sits on keeping Lone Tree refurbishment and Archimedes development on schedule and on budget. The update helps here, since capex, permits and construction progress remain aligned with the December 2025 plan.
The biggest risk still sits with execution across several high capex builds while the business remains loss making. Any slippage at Lone Tree or slower underground ramp up would likely matter more to the near term story than the longer dated Mineral Point heap leach plan.
The clearest operational hinge in this news is the Lone Tree autoclave and CIL plant, which i-80 Gold expects to commission in late 2027. Management is sticking with an estimated US$430 million capital cost, contingency included, with roughly 44% of that already committed and only about 10% of the contingency drawn so far.
For you, Lone Tree is the practical link between project updates and future catalysts. Moving from toll milling to in house processing, with a federally permitted plant and state permits in hand, concentrates both upside and risk in a single complex construction job. Execution there will heavily frame how investors read later milestones at Archimedes and Mineral Point.
i-80 Gold's analyst narrative points to $752.0 million of revenue and $268.7 million of earnings by 2029, based on a 79.5% yearly revenue growth profile and a swing in earnings of about $527 million from a current loss of $258.6 million.
Uncover how i-80 Gold's fair value indicates a 99% potential upside to its current price before other investors close that gap.
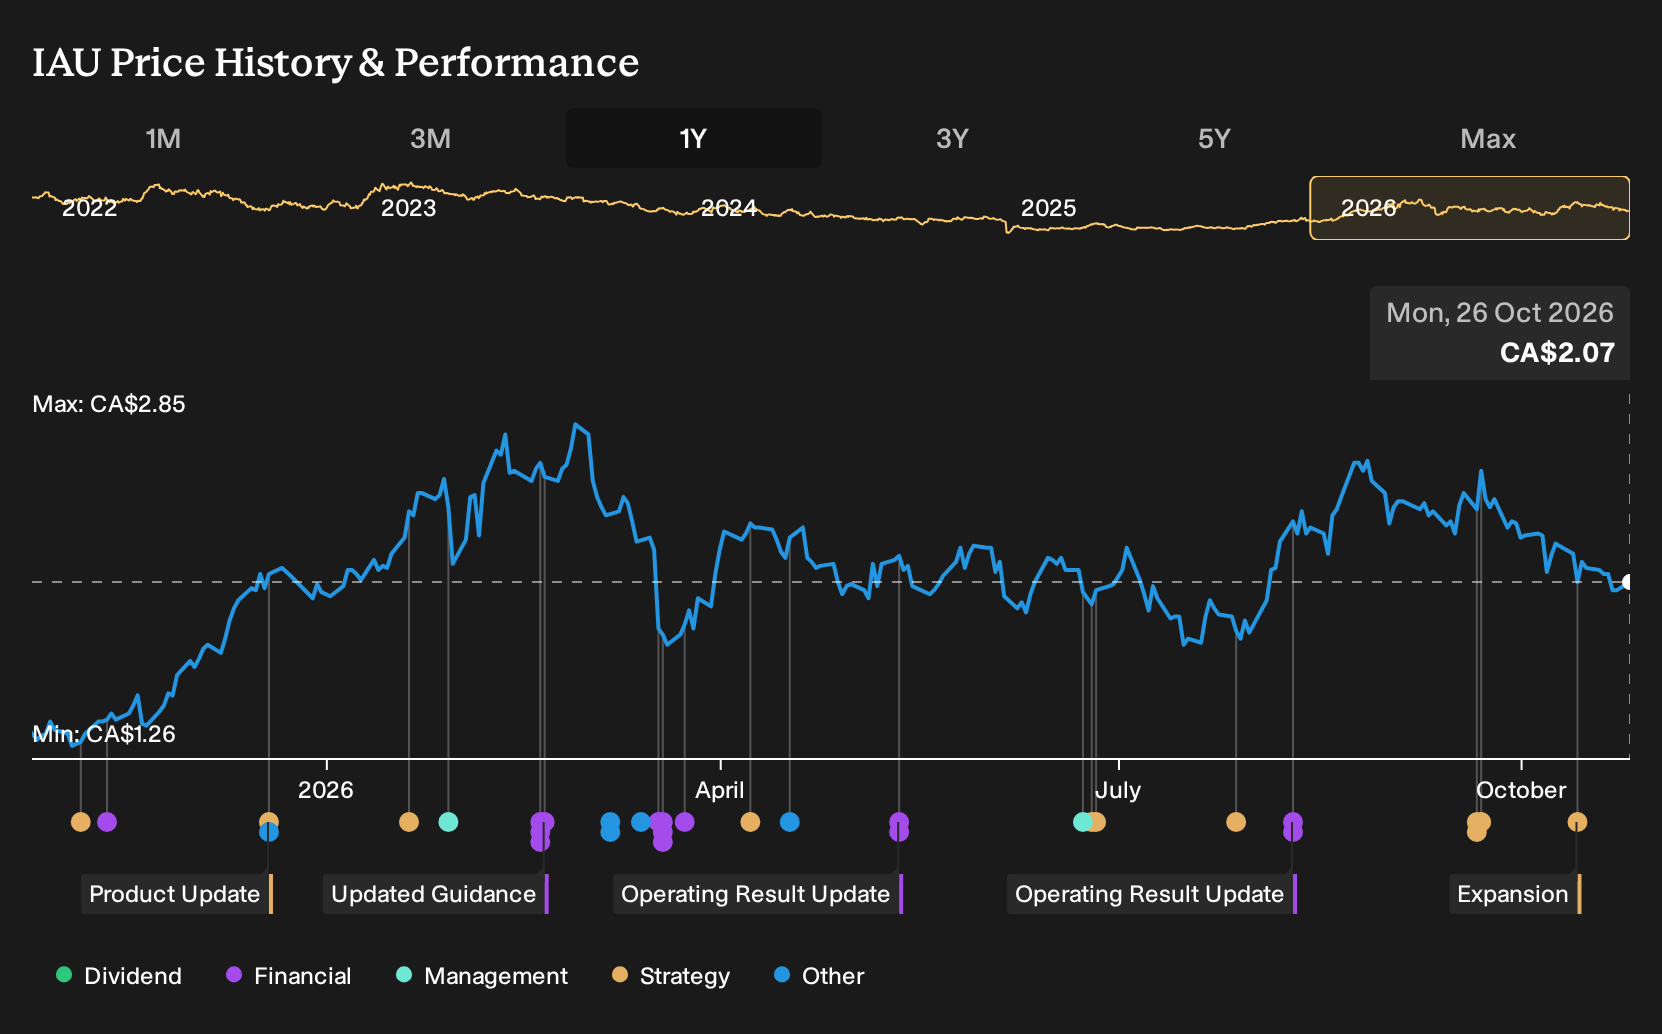
Exploring Other Perspectives
One alternate view on i-80 Gold leans hard into the potential upside from internal processing. The most optimistic analysts were modelling about $1.3b of revenue and $512.4 million of earnings by 2029, compared with $752.0 million and $268.7 million in the baseline scenario. Those projections came before this Nevada plan update, so expectations may change in either direction as the situation is reassessed.
Explore 3 other i-80 Gold fair value estimates, including one that suggests as much as 165% potential upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your i-80 Gold research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for i-80 Gold. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate i-80 Gold's overall financial health at a glance.
Looking for more investment ideas beyond i-80 Gold?
If the i-80 Gold story has you thinking about where else to put fresh capital to work, the Simply Wall St Screener can help you quickly filter the market down to a shortlist that actually fits your risk and return preferences.
- For investors who want potentially mispriced opportunities with quality fundamentals, start with our hand picked set of 3 high quality undervalued stocks that may merit a closer look.
- If resilience matters more to you than headline growth, focus on companies in the 8 resilient stocks with low risk scores that score well on stability and business strength.
- Prefer sturdier finances and less fragile balance sheets, especially around cycles and funding conditions, then lean on the list of solid balance sheet and fundamentals (7 results) to narrow your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com