


EN
3 Export Stocks Retail Investors Are Watching After China’s Trade And Export Rebound
China just posted 4.5% Q3 GDP growth and a powerful export rebound, even with steep tariffs on U.S. trade, and that combination has pushed Emerging Asia’s export story back into the spotlight. Investors are rethinking where future capital might flow. This article walks through three stocks from an Emerging Asia export-oriented industrials screener that appear closely tied to these shifting global supply chains.
The three stocks highlighted next are only a small sample, and the full Emerging Asia export-oriented industrials screen surfaced 110 more companies with equally compelling narratives that are not covered in this article.
To go beyond this shortlist, analyze, compare, and identify your highest conviction ideas directly in the Emerging Asia Export-Oriented Industrials screener.
BizLink Holding (TWSE:3665)
BizLink Holding plugs directly into the Emerging Asia export theme, supplying wiring and system integration from Taiwan into global supply chains for AI data centers, electric vehicles, and industrial equipment, which sets up a clearer view of what really drives its story.
"The accelerating build out of AI data centers and high density compute systems continues to shift bottlenecks toward rack level power delivery, cooling and connectivity. This keeps BizLink Holding tied into customer roadmaps where deeper system content can support revenue and sustain earnings quality."
What happens to that opportunity depends heavily on how one quiet pressure on future margins and cash generation ultimately resolves.
That margin pressure is exactly what the full narrative for BizLink Holding unpacks in detail, laying out how BizLink Holding could balance AI upside against export cyclicality.

J&T Global Express (SEHK:1519)
J&T Global Express plugs directly into the Emerging Asia export story, running an express parcel and cross border logistics network that joins Chinese factories, Southeast Asian sellers and overseas buyers. That scale is now big enough for small shifts in mix to really matter.
"The shift in J&T Global Express revenue mix toward non China markets, which reached 50% of group revenue in the first half of 2026 and 33% of parcel volume in the third quarter, creates room for a higher group average revenue per parcel and potentially steadier earnings if these regions carry structurally different pricing and customer profiles."
What happens to that opportunity hinges on how one fast rising cost and investment line ultimately feeds through to margins and cash returns.
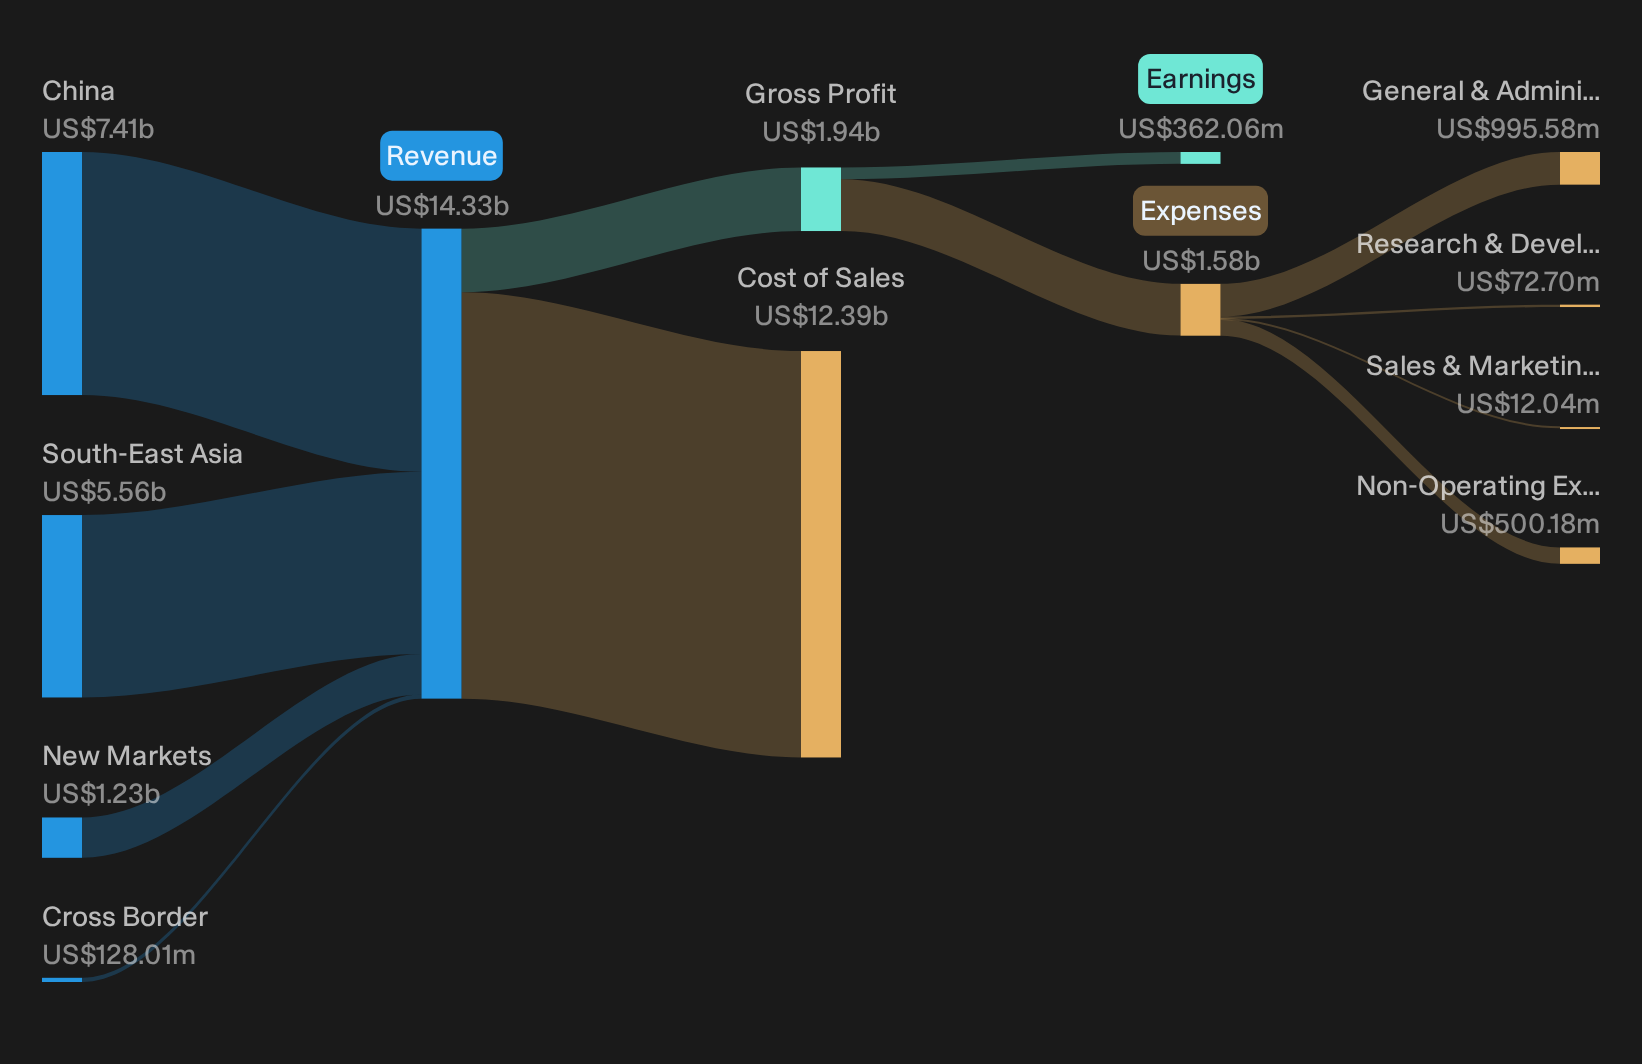
J&T Global Express runs an export linked express delivery and cross border logistics platform, generating about US$14.3b from air freight transportation, with a market value of roughly HK$87.7b.
That rising cost line is only half the story, and the full narrative for J&T Global Express maps how J&T Global Express could turn that heavy investment into accelerating export leverage and pricing power.
Solar Industries India (NSEI:SOLARINDS)
Solar Industries India gives the screener direct exposure to export linked mining and defense supply chains, manufacturing explosives and high energy materials and generating about ₹113,515 million from explosives, accessories and related services, with a market value of roughly ₹1,690.6b.
For Emerging Asia’s export oriented industrial theme, Solar Industries India brings something different. It links Indian mining and defense demand with overseas customers across about 90 countries, and the key question now is how durable that global order book really is.
"Defence revenue is guided to reach about ₹4,500 crores in FY27 from ₹2,634 crores in FY26, supported by a defence order book of roughly ₹18,000 crores within a total order book above ₹21,000 crores. This indicates multi year visibility for revenue and earnings."
What happens to Solar Industries India’s margin profile and export firepower hinges on how one tight constraint on funding and execution ultimately plays out.
That funding constraint is exactly what the full narrative for Solar Industries India unpacks for Solar Industries India, revealing where export demand could accelerate and where execution risks may still bite.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. By the time momentum is obvious, early entry points are already dropping away. Scan under the radar for now, then act promptly to secure earlier entry.
- Spot higher-yield opportunities before they are crowded by income hunters by reviewing the curated 224 dividend fortresses that balances payout strength with balance sheet resilience.
- Track companies powering AI infrastructure momentum while it still flies under wider market attention by scanning the focused 55 AI infrastructure stocks built around mission critical enablers.
- Catch robotics demand shifts early by reviewing the hand picked 94 robotics and automation stocks that link automation, productivity gains and real operating cash generation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com