


EN
Solaris Energy Infrastructure (SEI) Lifts Turbine Spending, Is The Stock Fully Priced?
Solaris Energy Infrastructure (SEI) has drawn fresh attention after management increased capital spending on turbines and power equipment, a move directly tied to expanding contracted capacity and supporting the stock’s currently elevated P/E ratio.
That spending decision comes after a sharp run followed by a pullback. Solaris Energy Infrastructure has a 90 day share price return of 31.52% and a year to date share price gain of 23.80%. However, the 30 day share price return is down 12.33%, while long term total shareholder returns remain very large over three and five years. This signals that momentum has cooled in the short term even as investors who stayed in the stock over several years have been strongly rewarded.
Scan how Solaris Energy Infrastructure compares with other power-focused businesses by reviewing our handpicked list of 42 power grid technology and infrastructure stocks.
The question now is simple. Is the pullback in Solaris Energy Infrastructure a reset of sentiment around a stretched P/E, or a temporary pause while the heavier turbine spend catches up to the valuation math?
Most Popular Narrative: 39% Undervalued
On the most followed view of Solaris Energy Infrastructure, a fair value of $101.27 sits well above the last close at $62.22, so the key question is whether the contracted power pipeline and funded buildout really justify that gap.
The main factor that has to go right is Solaris Energy Infrastructure successfully executing its capital intensive build out of more than 3.1 GW of secured and planned capacity, including integration of recent acquisitions and delivery of power and services projects described as high return, under increasing leverage.
Executing on a capital program funded by over US$2.5b of issued notes, an undrawn US$650m revolver and more than US$800m of cash, alongside internal underwriting that targets unlevered returns above 20% on deployed capital, gives Solaris Energy Infrastructure a path to scale its contracted portfolio into a larger adjusted EBITDA contribution relative to current earnings.
See why 27 investors see Solaris Energy Infrastructure as 39% undervalued.
Result: Fair Value of $101.27 (UNDERVALUED)
Still, this upbeat Solaris Energy Infrastructure story can fray if the capital heavy turbine rollout strains cash flows, or if new multi gigawatt contracts fail to refill the pipeline.
Find out about the key risks to this Solaris Energy Infrastructure narrative.
Another View: Solaris Energy Infrastructure Looks Expensive On Earnings
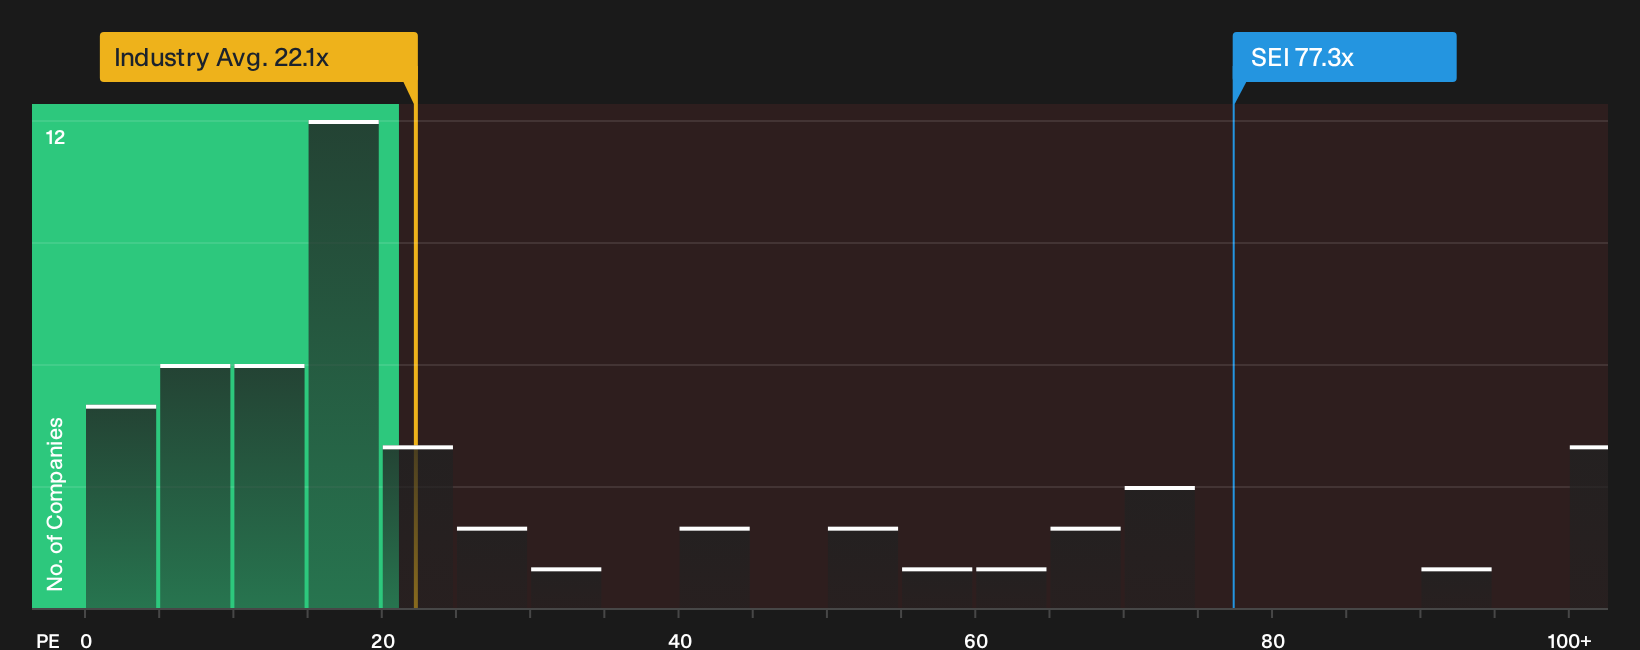
While the most popular Solaris Energy Infrastructure story leans on a rich fair value, the current P/E of 77.3x tells a tougher tale. The fair ratio sits at 24.5x, the US Energy Services group averages 22.1x, and close peers trade on 29.3x. That kind of gap can mean meaningful valuation risk if expectations cool. Which story do you trust more right now: the cash flow model or the earnings multiple?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between the upbeat cash flow story and the rich earnings multiple on Solaris Energy Infrastructure is normal. Move quickly to inspect the data, weigh the competing signals, and decide where you stand using our breakdown of 4 key rewards and 3 important warning signs
Looking for more Solaris Energy Infrastructure investment ideas?
If Solaris Energy Infrastructure has your attention, do not stop here. Broaden your watchlist with a few focused stock ideas that match your own risk and return preferences.
- Target potential upside by scanning a curated pool of undervalued opportunities using our 29 high quality undervalued stocks so you are not relying on a single story.
- Prioritize resilience and sleep better at night by filtering for companies with strong finances through our list of solid balance sheet and fundamentals (24 results) before the crowd notices.
- Get ahead of the herd by zeroing in on overlooked quality using our 21 high quality undiscovered gems and avoid finding out later that you missed them early.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com