


EN
Should Full Processing Restart Require Action From Endeavour Silver (TSX:EDR) Investors?
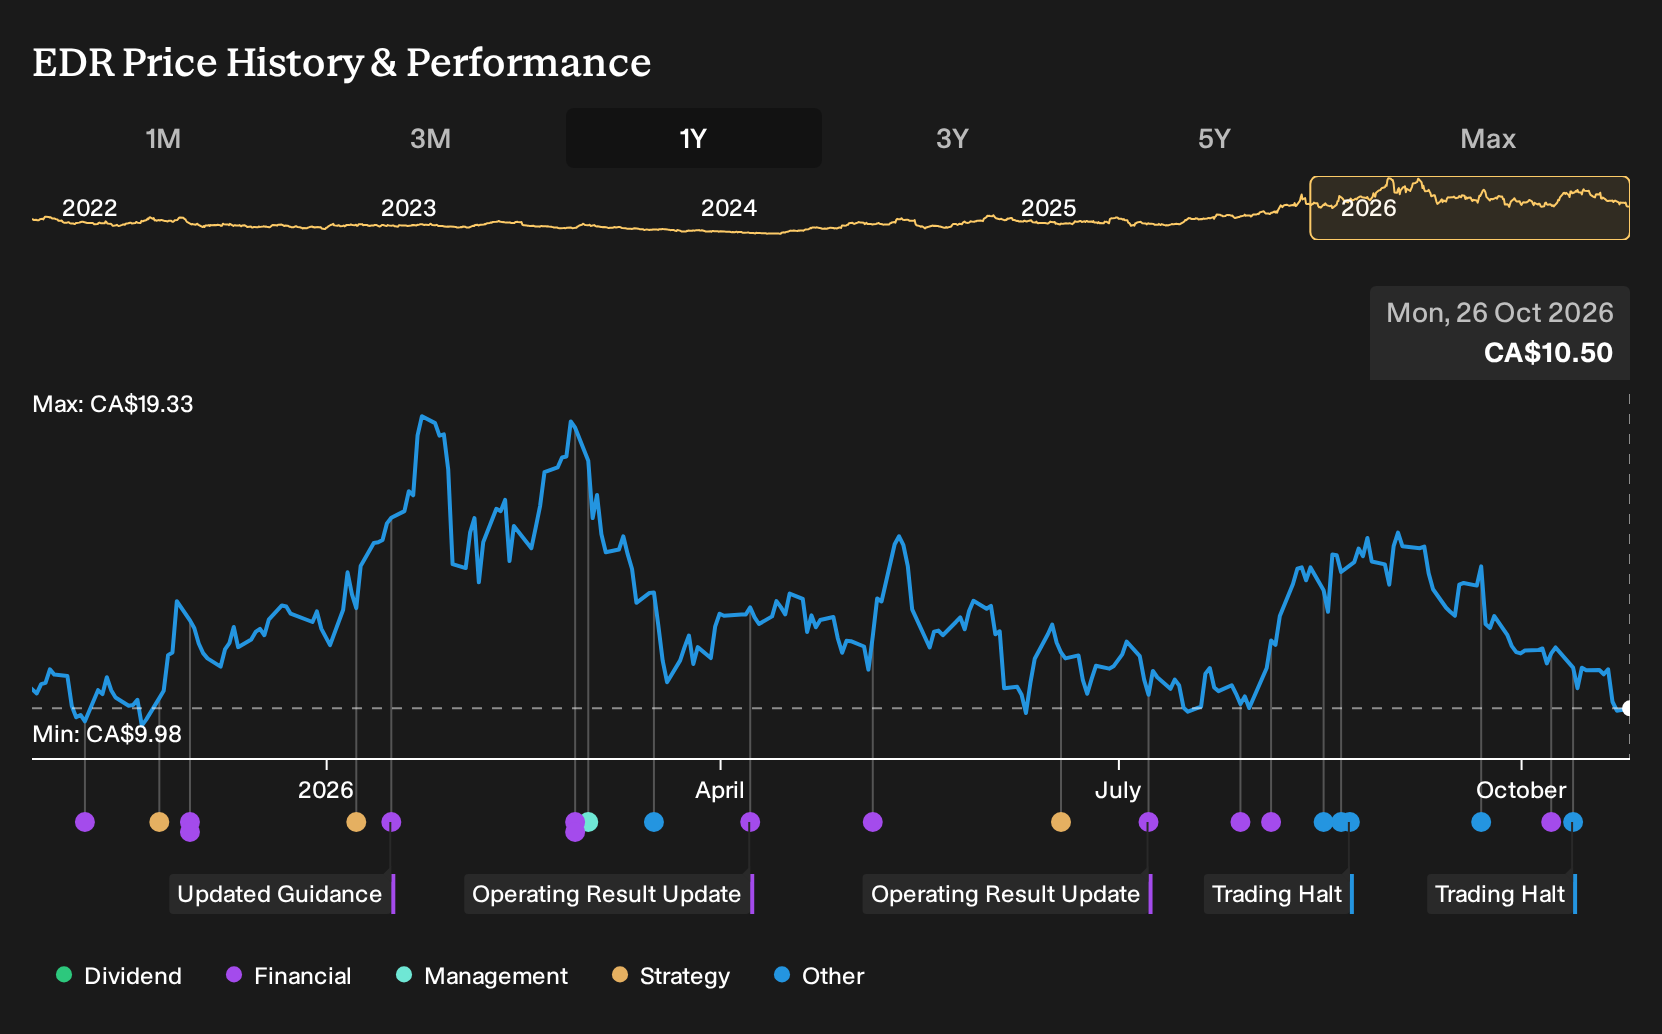
- Endeavour Silver reported that repairs to the primary ball mill trunnion at the Guanaceví mine were completed, and processing is now back at full capacity.
- The return to full throughput at Guanaceví restores a key processing hub, which directly affects unit costs, production reliability, and near-term cash generation.
- Investors can now evaluate how Endeavour Silver’s investment narrative is influenced by Guanaceví’s return to full processing capacity after the recent repairs.
Scan beyond Endeavour Silver and assess other precious metal producers that are either under pressure or quietly gaining momentum with the curated list of 10 top silver producer stocks.
Endeavour Silver Investment Narrative Recap
To own Endeavour Silver, you need to be comfortable with a production story that leans heavily on smooth execution at multiple mines and a tight handle on costs. Guanaceví returning to full processing capacity helps support that narrative because it removes an immediate operational drag and gives management one less moving part to worry about in the near term.
The key short term swing factor is still how efficiently new and acquired operations such as Terronera and Kolpa run in real conditions, especially given past net losses and liquidity pressure. The biggest risk is that commissioning issues, cost creep or regulatory delays at these sites offset benefits from Guanaceví’s recovery and keep cash flow under strain.
The repair update at Guanaceví ties directly into earlier commentary about operational setbacks and liquidity risk. When a core plant is constrained, unit costs tend to rise and cash generation can soften, which matters for a business that has relied on external borrowing and carries a negative working capital position.
With Guanaceví back at full throughput, attention naturally shifts to whether Terronera can move from commissioning losses to meaningful operating contribution and whether Kolpa integration costs can be contained. That is where the larger catalysts sit in relation to this event, because stable output from existing hubs gives Endeavour Silver more room to focus on execution at those growth projects.
Endeavour Silver's current analyst storyline points to revenues of $807.1 million and earnings of $207.7 million by 2029, off current earnings of $65.7 million. That profile assumes revenue growth of 3.1% per year and requires earnings to more than triple, rising about 3x from today.
Discover why Endeavour Silver's fair value points to a 94% potential upside compared to its current price before that gap begins to narrow.
Exploring Other Perspectives
For a contrasting angle, focus on the bullish catalyst around Pitarrilla. The most optimistic analysts were pencilling in revenue of $1.2b and earnings of $407.5 million by 2029, far above the $807.1 million and $207.7 million consensus figures. Those views predate the Guanaceví repair news, so opinions may evolve as different scenarios are reviewed.
Explore 5 other Endeavour Silver fair value estimates, including one that suggests potential upside of up to 717% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Endeavour Silver research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Endeavour Silver. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Endeavour Silver's overall financial health at a glance.
Looking for more Endeavour Silver investment ideas?
Once you have a handle on Endeavour Silver, it often helps to set it against a wider field of opportunities. The Simply Wall St Screener can help you quickly surface other stocks with very different risk and return profiles, so you can see where this miner fits in your broader portfolio.
- If you are hunting for value with quality backstops, compare Endeavour Silver against a 3 high quality undervalued stocks that combine stronger cash generation with solid balance sheets.
- For investors who care more about stability than excitement, weigh this stock against a 8 resilient stocks with low risk scores that historically carry lower risk scores.
- If you want to broaden your watchlist beyond well known tickers, scan a 9 high quality undiscovered gems that pair quieter profiles with stronger fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com