


EN
After Jenoptik's 94% Climb, The Story Has Changed
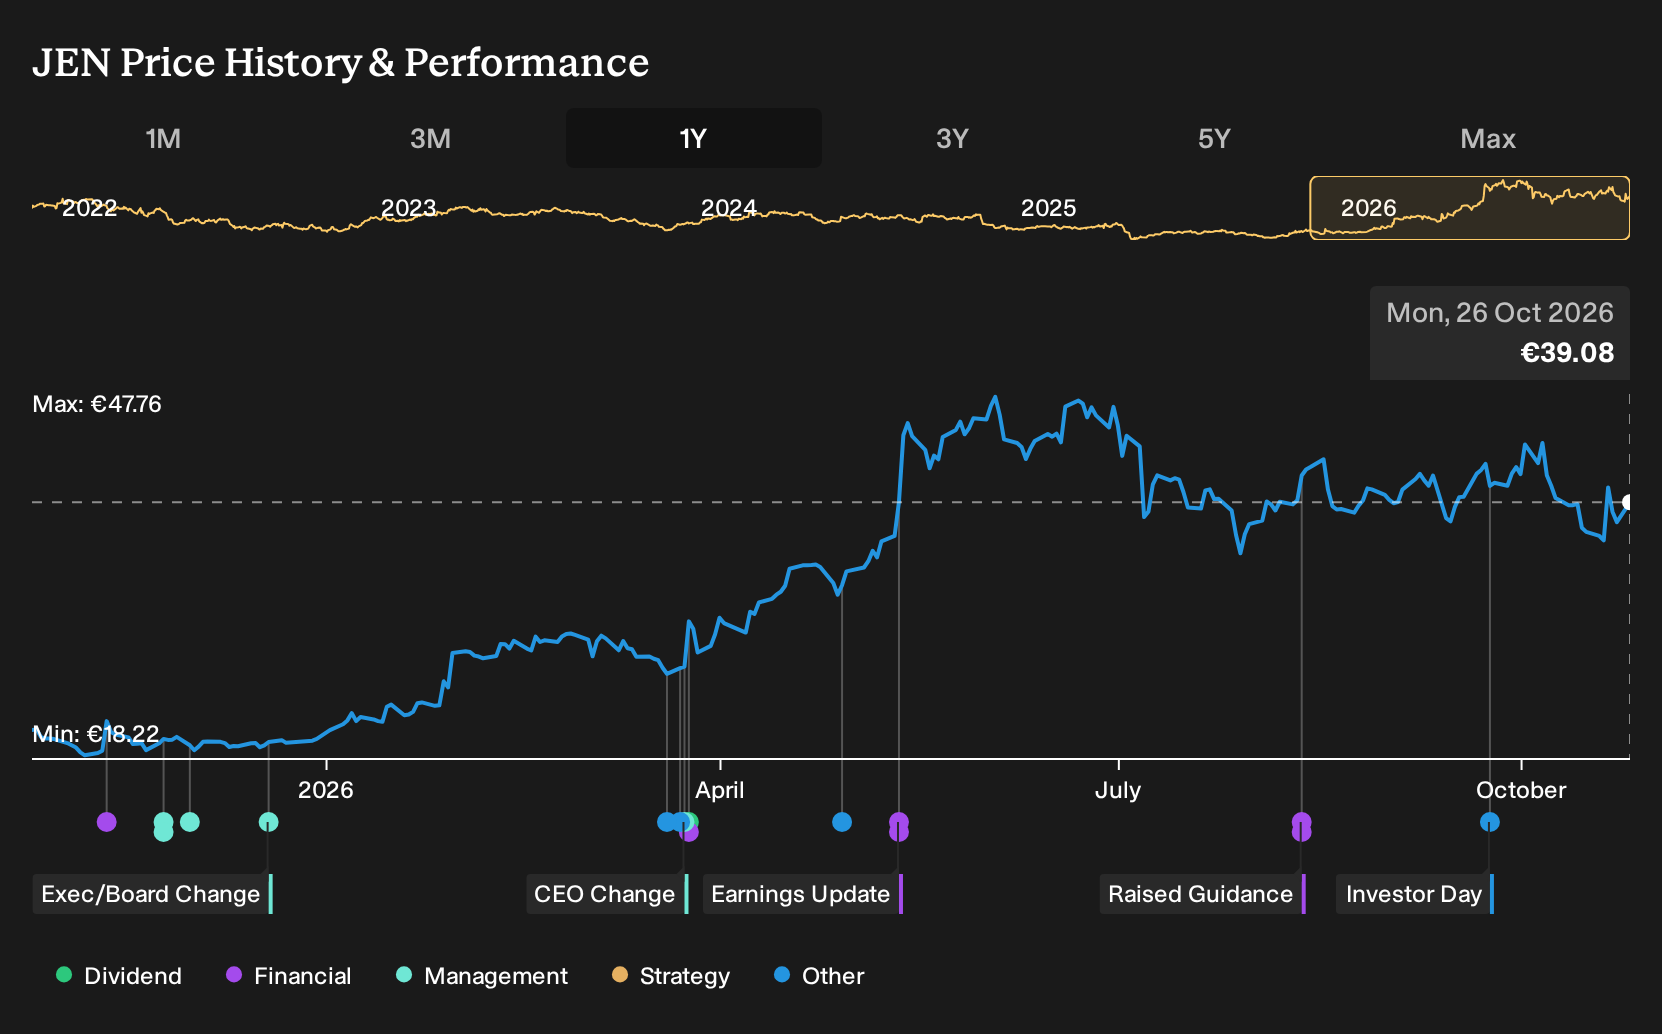
Jenoptik spent this year sending mixed signals. Headlines highlighted a 74% jump in Q1 2026 orders and a later plunge after weaker demand, while full-year commentary pointed to single digit revenue growth guidance and solid EBITDA margins. For Jenoptik shareholders, the return over the past year was 93.7%, including dividends. If you had been weighing those clashing narratives back in October 2025, what exactly were you being paid to believe about this business?
Jenoptik is not the only name tied to this theme. Zero in on 55 AI infrastructure stocks and compare how each one is priced.
The Argument Jenoptik Investors Were Really Pricing
The shares cost €20.2 at the start of the period, and you had to decide which story about Jenoptik you trusted more.
The bullish narrative saw a fair value of €24.46, a price implied by assumptions around 4.2% revenue growth and a 9.6% profit margin, supported by a greater mix of higher margin photonic solutions and disciplined cost control. This view relied on momentum in semiconductor, biophotonics, and smart mobility, as well as expansion in North America and Asia.
The bearish case anchored on a fair value of €19 and focused on demand volatility in semiconductor and automotive markets. It also emphasized the risk that order swings, tariffs, and underutilised assets could keep overall revenue under pressure even if margins improved.
What The Jenoptik Evidence Actually Tested
The key development was Jenoptik’s record Q1 2026 order intake of €357m, largely from semiconductor and biophotonics customers, which supported the positive demand narrative. Later, revenue for Q2 2026 reached €261.958m with net income of €22.8m, lifting net margin to 8.7%. However, a separate earnings miss and weaker demand in several end markets supported the more cautious perspective. Overall, the evidence pointed in both directions.
The central assumption was that strong semiconductor and biophotonics orders would translate into sustained, higher quality earnings. When assessing another supplier to AI or chip spending, track whether rising intake and higher margins are reflected in reported net income, not only in optimistic guidance.
What Jenoptik’s 94% Run Now Asks You To Believe
Jenoptik trades at €39.08 today after a 93.7% gain over the past year, and the selected Narrative’s Fair Value sits above the current price. That view leans heavily on photonics exposure to AI infrastructure, plus reported order backlog and early signs of better earnings quality.
The same Narrative still argues that today’s price does not yet fully credit Jenoptik’s shift toward higher margin photonic solutions, supported by global expansion and cost discipline, if those trends hold.
"Ongoing portfolio shift towards higher-margin, software-enabled photonic solutions, combined with disciplined cost and cash management (evidenced by a material increase in cash conversion rate and reduced headcount), is likely to support margin expansion and enhance earnings quality over the medium term."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Another Piece Of The AI Build
Jenoptik gives you one way to think about AI infrastructure. It focuses on sensing, measurement, and precision equipment around those chips.
Step sideways and a different need appears. All that computing power depends on fast, reliable networking gear tying huge data centers together.
One specialist concentrates on Ethernet based systems and a single software stack. Its hardware and code help customers run dense, data heavy workloads efficiently.
The more AI spreads into cloud and enterprise environments, the more that kind of networking backbone matters. That is where the next narrative starts.
One Narrative has already put a figure on it. → Uncover the company trading 26% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com