


EN
Did AI Data Center Demand Just Shift Monolithic Power Systems Stock Narrative?
- Monolithic Power Systems is drawing fresh attention after recent commentary highlighted how its power management chips are embedded in AI data centers, cloud servers and other high performance computing systems, with data center related demand now representing a sizeable share of the business.
- The interesting angle for investors is that data center exposure is described as moving toward roughly 50% of revenue, which puts AI related workloads at the center of Monolithic Power Systems' current demand mix and investment decisions.
- The focus is now on how Monolithic Power Systems' rising AI data center revenue mix could reshape the existing investment narrative around execution.
Compare Monolithic Power Systems' AI data center angle with a curated set of infrastructure plays by scanning our hand picked 55 AI infrastructure stocks for your watchlist.
Monolithic Power Systems Investment Narrative Recap
To own Monolithic Power Systems, you need to be comfortable with a business heavily tied to AI data center demand and willing to accept execution risk around that exposure. The short term swing factor is whether Enterprise Data and related AI workloads keep absorbing the manufacturing footprint that management is building out toward beyond US$6b in annual revenue capacity.
The main near term risk has not really changed with this news. If orders slow or design wins stall, that extra capacity and the Singapore partnership could weigh on free cash flow for longer. Ongoing investigations and prior margin compression from 65.6% to 24.5% also keep operational quality and customer trust in focus.
Without fresh company announcements attached to this update, the earlier decision to extend manufacturing capacity beyond US$6b in annual revenue equivalents and commit to long term 300mm volume out of Singapore remains the key reference point. That move ties Monolithic Power Systems even more tightly to a thesis that AI data center power demand will efficiently utilize this footprint.
For you as a shareholder, the link between that capacity build and AI related design wins is central. Stronger Enterprise Data demand could help support revenue growth and protect margins as silicon carbide, GaN and high voltage AC DC products ramp. If those product lines or AI oriented sockets underperform, fixed costs and capital intensity become more of a constraint on future earnings power.
What The Current Forecasts Assume For Monolithic Power Systems
Analyst models around Monolithic Power Systems rest on some punchy numbers. Consensus expects revenue to compound at 28.3% a year over the next three years as AI heavy data center demand, automotive sockets and newer power products absorb the extra manufacturing capacity. Profit margins in those same models move from 24.5% today to 30.2% in three years, which asks the business to both grow the top line quickly and lift efficiency at the same time.
Earnings forecasts sit at the center of this setup. Analysts project that profit climbs from US$801.9m today to US$2.1b by 2029, with a wide spread between the most bullish call at US$2.5b and the most cautious at US$1.8b. That step up implies earnings a bit over 2.5x the current level, which puts execution on capacity, pricing and mix under close watch for anyone tracking Monolithic Power Systems.
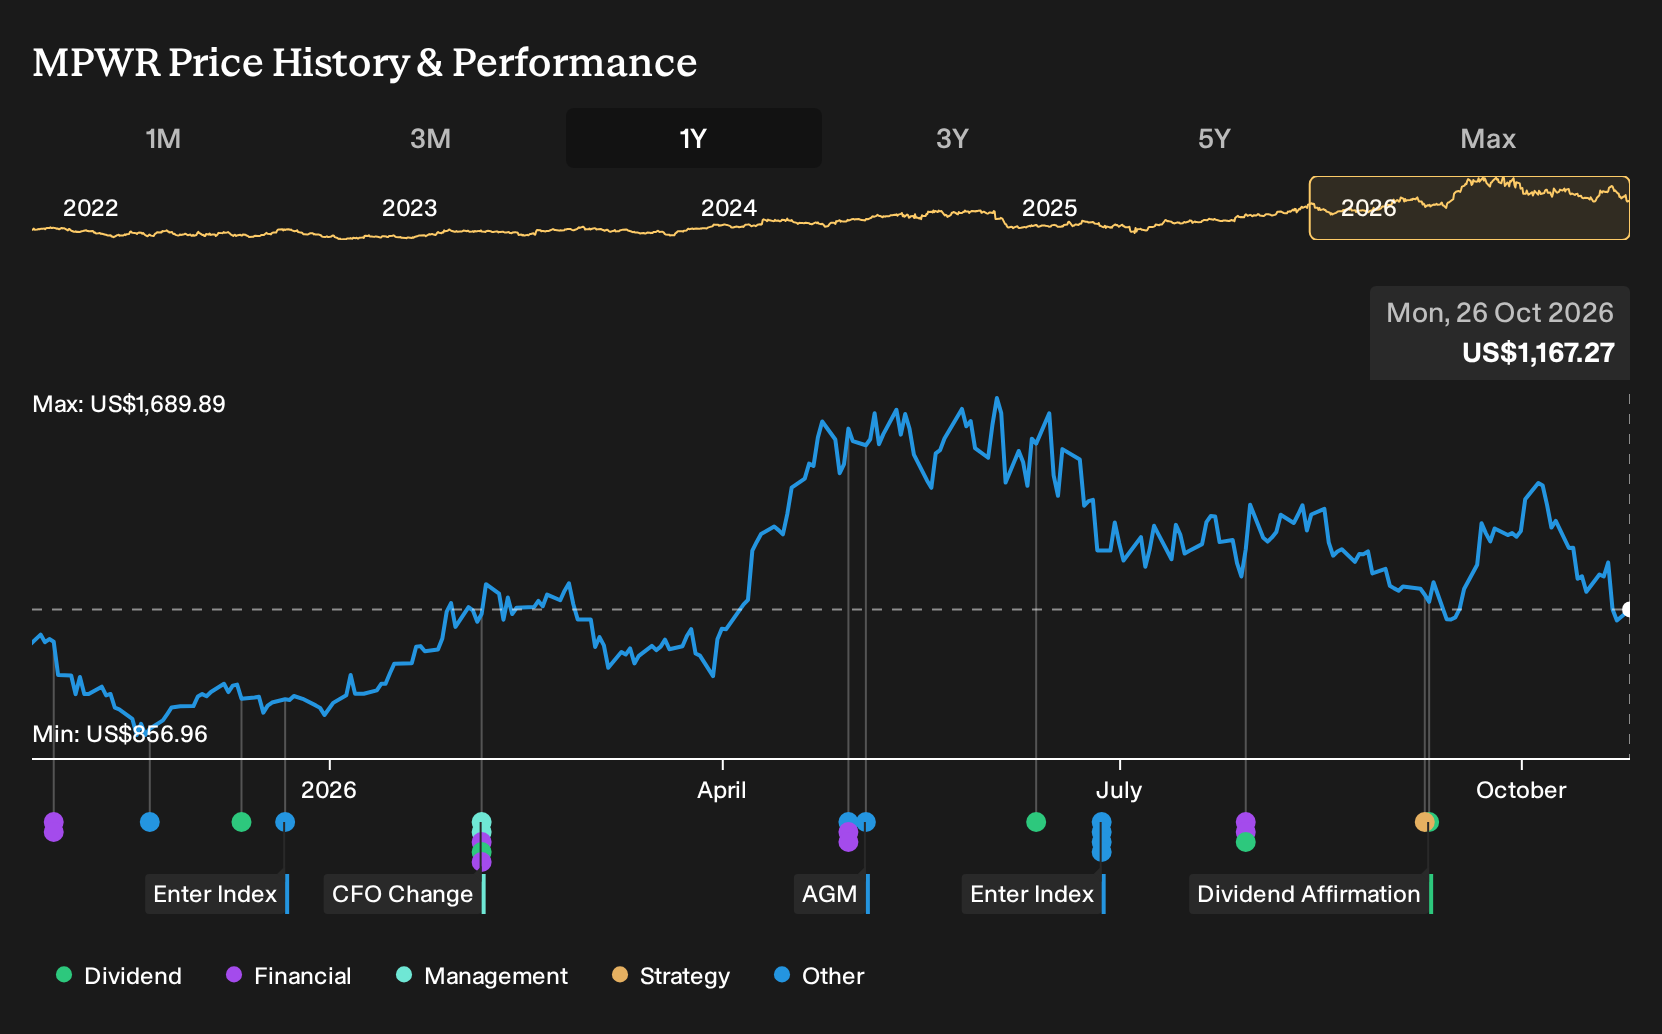
Valuation work in the report ties those earnings to a future P/E of 63x on 2029 earnings, compared with 69.9x today and 42.4x for the wider US semiconductor peer group. For the current share price of US$1,140.12 to reach the consensus target of US$1,799.80, the company would need to move toward the assumed 2029 profile of US$6.9b in revenue and US$2.1b in earnings while maintaining investor confidence in that higher multiple.
Monolithic Power Systems' narrative projects US$6.9b revenue and US$2.1b earnings by 2029. This rests on 28.3% yearly revenue growth and an earnings increase of about US$1.3b from US$801.9m today.
Uncover how Monolithic Power Systems' fair value indicates a 54% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You can read the same Monolithic Power Systems update in two very different ways. The most bullish analysts focus on the AI data center angle and previously mapped out revenue climbing to about US$10.4b and earnings near US$2.4b by 2029, while others were closer to US$6.9b and US$2.1b. Both views pre date this news, so expect opinions to shift and examine several of them before updating your own narrative.
Explore 4 other Monolithic Power Systems fair value estimates, including one that suggests as much as 80% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Monolithic Power Systems research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Monolithic Power Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Monolithic Power Systems' overall financial health at a glance.
Looking For More Investment Ideas Beyond Monolithic Power Systems?
If the Monolithic Power Systems story has sharpened your thinking on AI infrastructure and execution risk, you can apply that same perspective across the wider market with the Simply Wall St Screener. You can filter for balance sheet strength, valuation support or income potential and quickly build a watchlist that fits your own priorities.
- If capital preservation is a high priority for you, you can start with companies that screen as more resilient and carry lower risk scores by reviewing the 30 resilient stocks with low risk scores.
- If you want income in addition to potential capital gains, you can focus on high yield payers that aim for stability by scanning the 5 dividend fortresses.
- If you are looking for quality that the wider market may not be paying full attention to yet, you can consider stocks flagged as strong fundamental performers inside the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com