


EN
Murphy USA (MUSA) Lifts Its Dividend, Is The Stock Still Below Fair Value?
Murphy USA (MUSA) just raised its quarterly cash dividend to $0.72 per share, an 11% increase, a move that underscores management’s confidence in the business and its cash generation.
Murphy USA’s latest dividend move comes after a choppy stretch for the shares. The 30-day share price return is 5.4%, the 90-day share price return is down 10.41%, the year-to-date share price is up 33.01%, and the 1-year total shareholder return is 37.6%.
Scan how Murphy USA’s dividend move compares with other potential income ideas by checking out a curated set of 5 dividend fortresses that may warrant a closer look after this kind of announcement.
Murphy USA is throwing off cash, raising its payout, and has a share price that has already moved hard over the past year. The real tension now is simple: Does that strength still come at a reasonable price?
Most Popular Narrative: 13% Undervalued
Murphy USA’s most followed valuation narrative puts fair value around $617.80, compared with the latest close at $539.14. This frames this dividend increase against a stock already priced below that estimate.
Structurally higher all in fuel margins, supported by guidance of about $0.35 per gallon for the back half of 2026 and evidence of rational pricing and higher breakeven levels for marginal retailers, could keep Murphy USA’s gross profit and net margins above prior cycles.
Consistent contribution from the integrated fuel supply chain, with controllable economics in the range of $0.02 to $0.03 per gallon and leverage to periods of tight physical supply and price volatility, creates an additional earnings stream that can support overall margin resilience.
See why 12 investors see Murphy USA as 13% undervalued.
Result: Fair Value of $617.80 (UNDERVALUED)
Still, the bullish Murphy USA story can crack if fuel margins soften faster than analysts expect, or if insider selling keeps pressure on the P/E multiple.
Find out about the key risks to this Murphy USA narrative.
Another View: Murphy USA Through A Cash Flow Lens
There is a catch to the bullish fair value of $617.80 for Murphy USA. Our DCF model, which prices the stock on future cash flows, points to a lower figure of $484.11 at the latest close of $539.14, implying Murphy USA trades above that cash flow estimate.
This gap between the DCF result and the narrative fair value highlights a simple question for investors. Do you place more weight on the cash flow math or on the earnings power story that supports the higher target? Look into how the SWS DCF model arrives at its fair value.
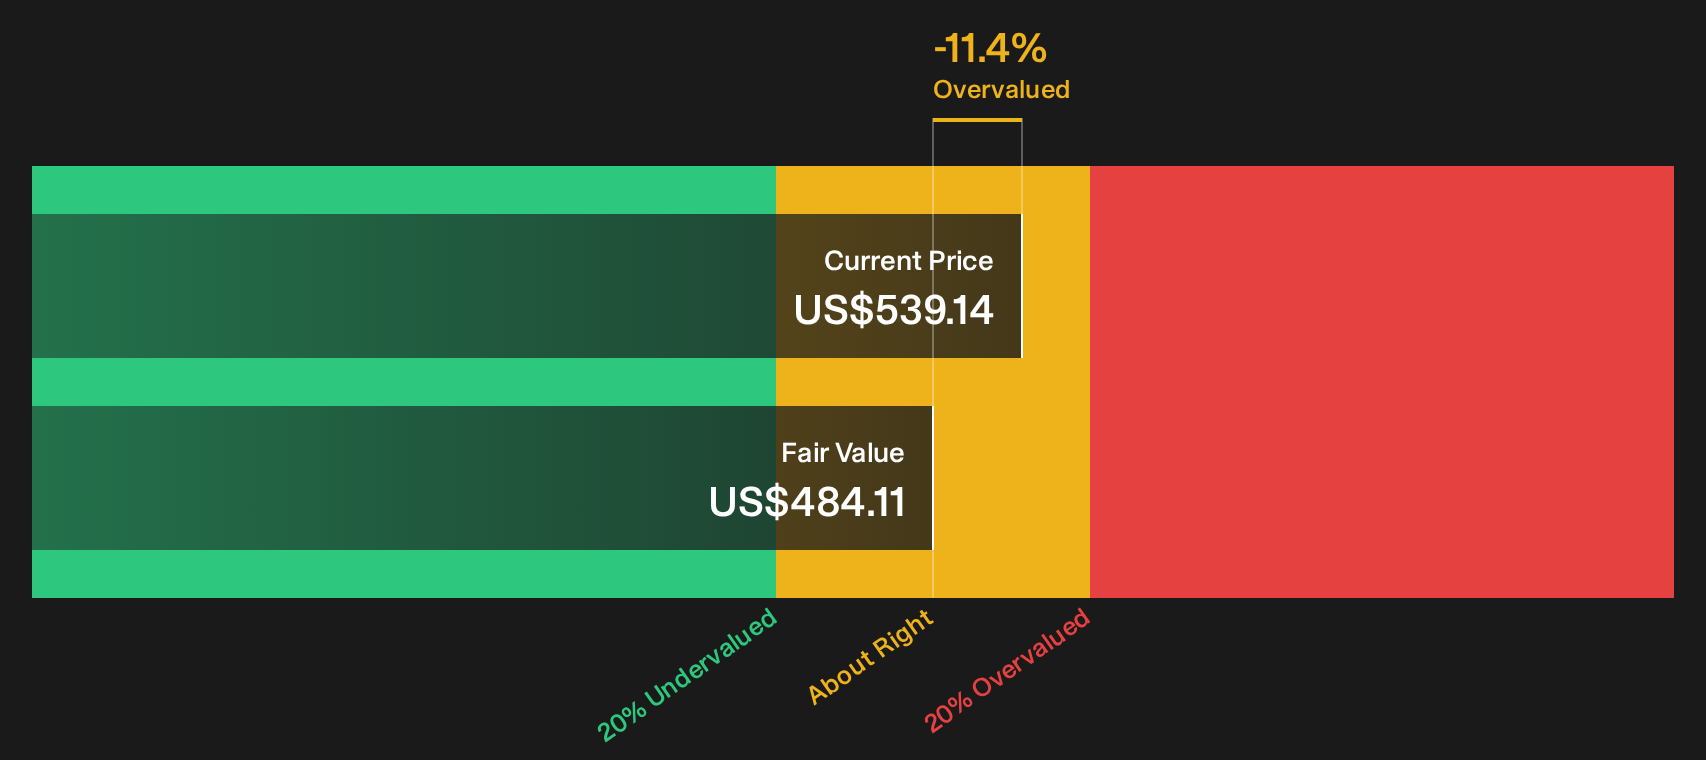
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Murphy USA for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Murphy USA so far. If you want a clear view, move quickly, weigh the evidence, and focus on the 2 key rewards and 3 important warning signs.
Looking for more Murphy USA style investment ideas?
If Murphy USA has your attention, do not stop here. Broaden your watchlist now with focused tools built to surface opportunities you might otherwise miss.
- Target resilient payouts by scanning a curated 5 dividend fortresses that puts income and staying power at the center of your research.
- Hunt for quality at a sensible price by working through a focused 29 high quality undervalued stocks that balances solid fundamentals with appealing valuations.
- Spot potential future leaders early by checking a 21 high quality undiscovered gems before attention and capital move elsewhere.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com