


EN
Did Lindt's Fall Catch You Out? What Investors Missed
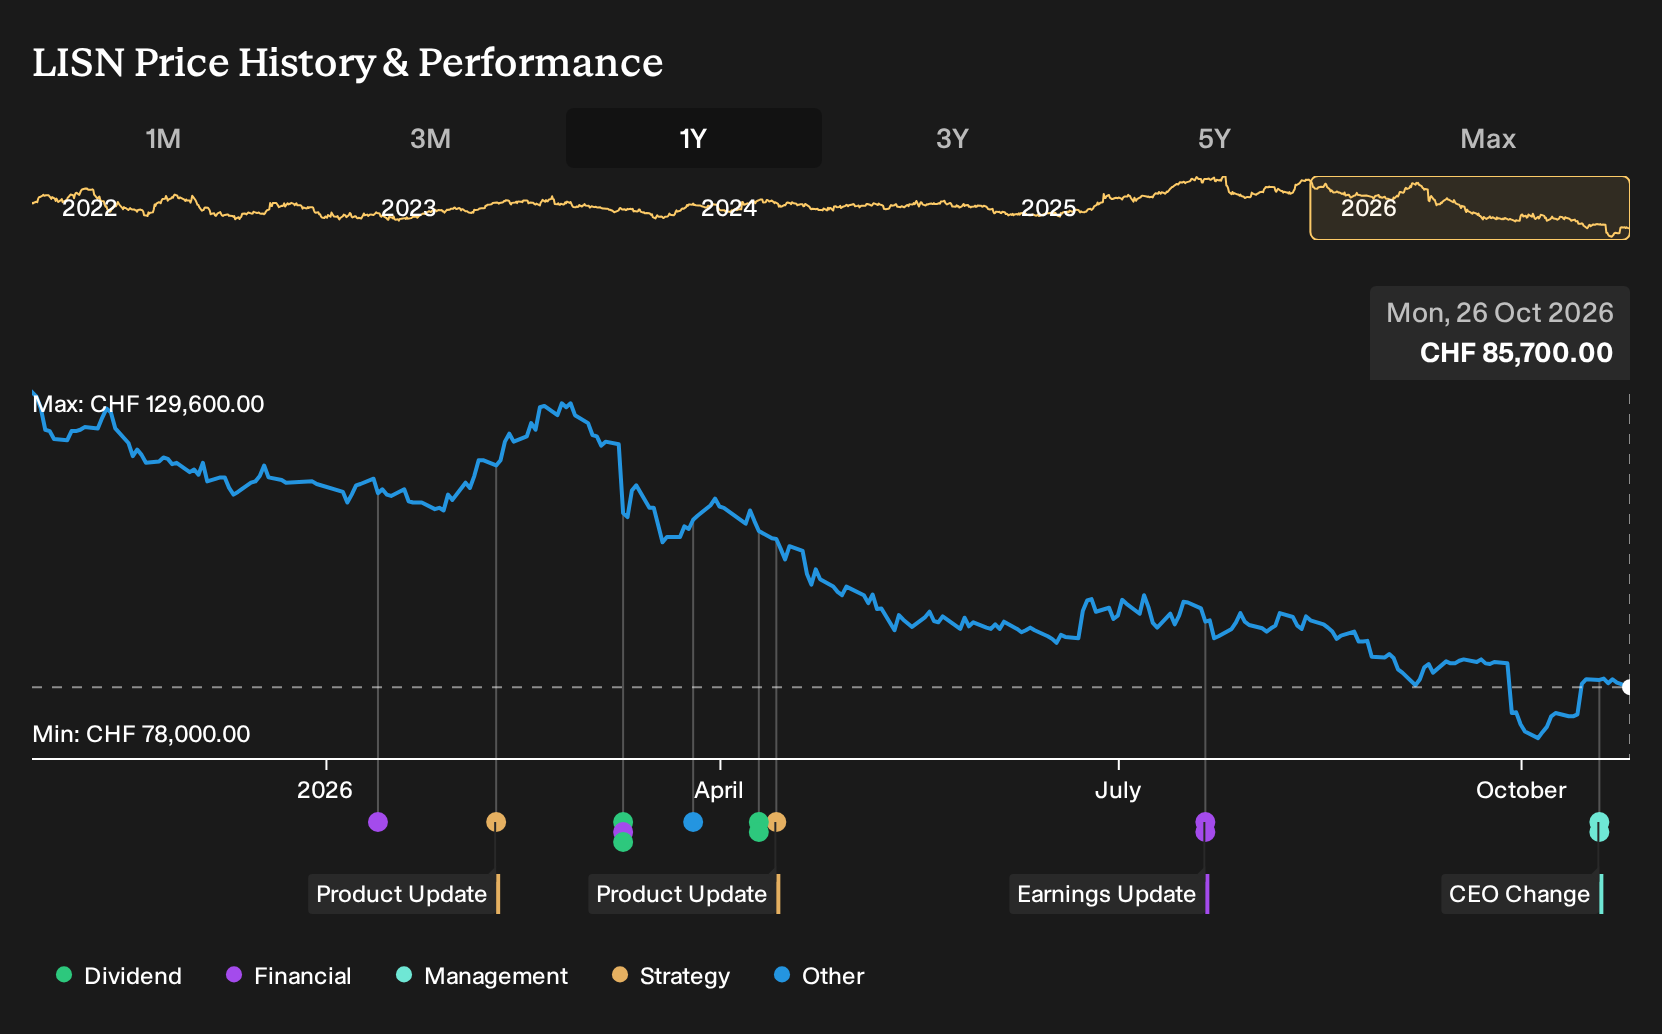
If you had looked at Chocoladefabriken Lindt & Sprüngli in late October 2025 and decided it felt too expensive after strong optimism about premium chocolate, direct retail and emerging markets, stepping aside might now feel like an escape. Investors who held Chocoladefabriken Lindt & Sprüngli over the past year are down 32.7%, including dividends. With that result in hand today, which expectations about growth, pricing power or margins were already being stretched at the start?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Chocoladefabriken Lindt & Sprüngli has already moved. See which of 195 high quality undervalued stocks still trade below our estimates.
Two Competing Stories Around Chocoladefabriken Lindt & Sprüngli
The shares cost CHF131,600 at the start of the period, and investors weighing Chocoladefabriken Lindt & Sprüngli had two clear stories to choose from.
The bullish narrative put fair value at CHF147,000 and leaned on revenue rising 8.7% a year with profit margins reaching 13.0%, supported by direct retail and emerging market expansion.
The more cautious view set fair value at CHF120,706 and still assumed 6.6% annual revenue growth, while highlighting persistently high cocoa costs as a key threat to future profitability.
What The Results Changed For Chocoladefabriken Lindt & Sprüngli
The key development was Chocoladefabriken Lindt & Sprüngli’s leadership shakeup after a sales slump and guidance cuts, which challenged the bullish story about smooth execution in premium chocolate and direct retail. H1 2026 revenue of CHF2,365.7m was slightly below H1 2025, while net income edged up to CHF192.2m and margin moved to 8.1%. The evidence cut both ways.
The useful takeaway is clear. When a thesis leans on pricing power and expansion, you need to track unit volumes, margin direction and any CEO turnover, and then test whether those datapoints still line up with the original growth story.
What Chocoladefabriken Lindt & Sprüngli’s Lower Price Now Asks You To Believe
Today the Chocoladefabriken Lindt & Sprüngli share price is CHF85,700, and this Narrative’s Fair Value sits above that level based on its own assumptions rather than any proven truth.
The Narrative leans on premium chocolate demand, global retail and cash generation, so any fresh view turns on whether that mix can really absorb cost swings and softer sentiment.
"The main factor that has to go right is that Lindt converts price-led growth and heavy cocoa and cost volatility into sustained volume growth and stable or improving margins across Europe, North America and newer markets, while maintaining premium brand strength."
One Narrative disagrees with today's price. → See where this Narrative says Chocoladefabriken Lindt & Sprüngli should trade
Another Angle On Indulgence
Thinking about Chocoladefabriken Lindt & Sprüngli already puts you in consumer-goods territory. That focus on treat spending can open a different door.
Chocolate relies on brand trust and habit. Everyday cupboard staples lean on those same instincts, just with dinner plates instead of gift boxes.
One large packaged-food group is quietly using that loyalty to support ongoing brand investment and tighter operations across its shelves.
It leans on cash generation and disciplined spending rather than sweeping reinventions or structural breakups. If that steady repair continues, your “comfort food” watchlist might need more than confectionery in it.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 42% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com