


EN
Top 3 Australian Cash Flow Stocks To Watch In October 2026
Energy costs in Europe are surging again as gas prices hit a four year high, which keeps pressure on inflation, interest rates, and household budgets worldwide. Australian investors watching this rollercoaster may want anchors that rely on solid cash coming in today rather than blue sky stories. This article walks through three Australian stocks where current cash flow suggests the share price looks too cheap based on simple discounted cash flow logic.
The three stocks that follow are just a small sample, since the full screen surfaced six more companies with equally compelling cash flow stories that are not covered here.
To go deeper on this idea, head straight into the Undervalued Stocks Based On Cash Flows screener to identify, analyze, and focus on the highest conviction cash flow opportunities that fit your own criteria.
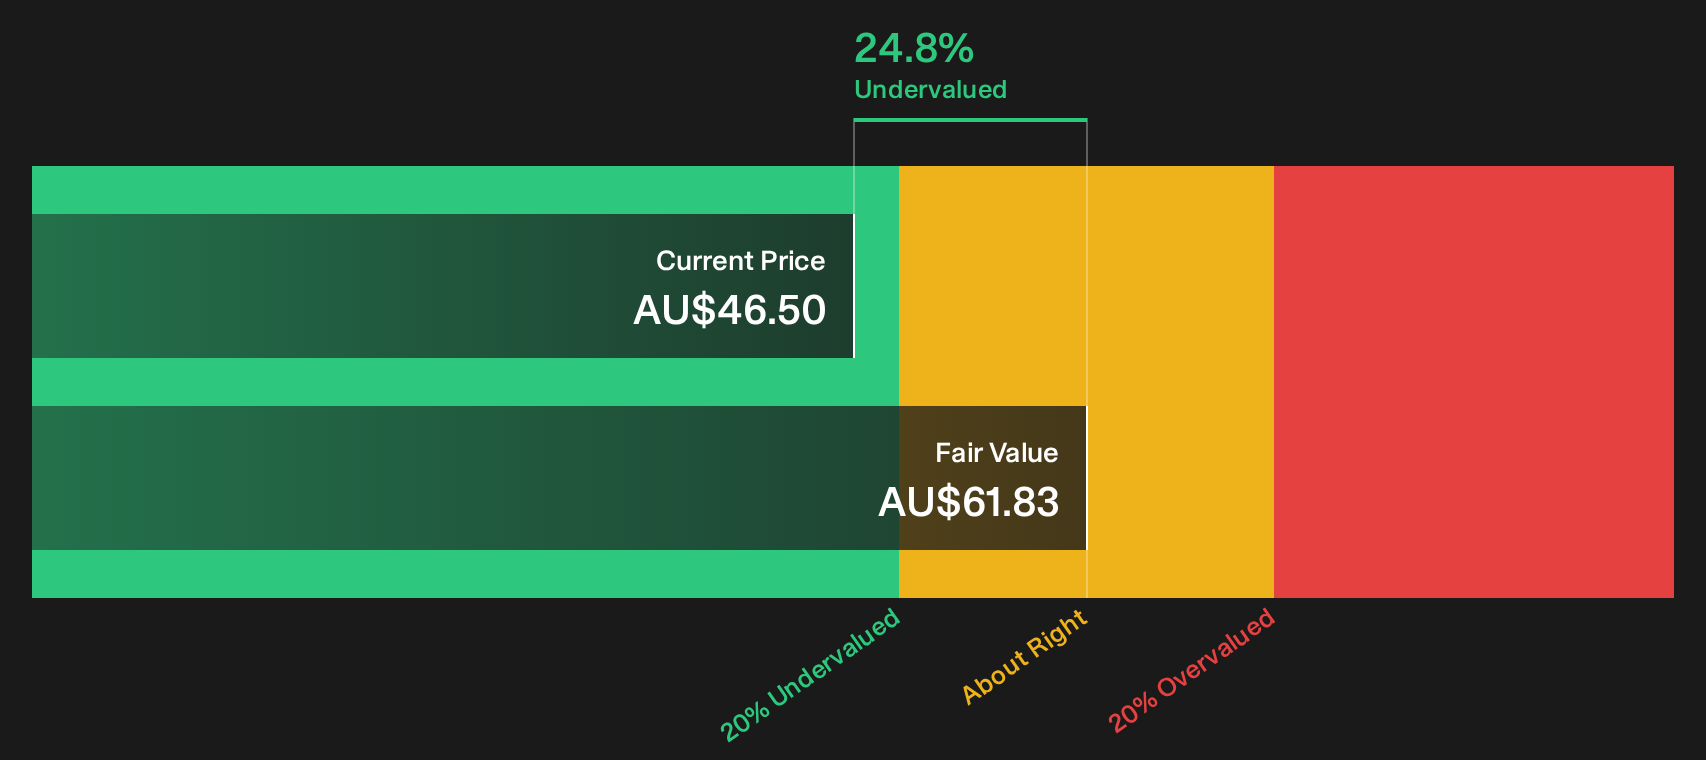
Ansell (ASX:ANN)
Ansell is a global protective gear specialist whose healthcare glove operations generate the kind of recurring cash flows this screener focuses on, giving investors a way to link everyday medical usage to long term valuation through discounted cash flow logic.
Ansell develops and sells hand and body protection, with Healthcare contributing about US$1.2b of revenue and Industrial about US$947 million, and the group valued at roughly A$6.5b by the market.
"Ansell is well placed to capture increased structural demand in PPE, driven by tightening workplace-safety regulation, rising healthcare and hygiene standards, and accelerating industrialisation in emerging markets."
What really matters now is how one quiet shift in the cost base filters through to margins and keeps that cash flow story intact.
If that cost shift is what you are watching, read the full narrative for Ansell to see how cash flows, valuation and risks really line up.
Origin Energy (ASX:ORG)
Origin Energy taps the screener theme through its cash generation in Energy Markets, where wholesale generation and retail electricity and gas contracts shape how current cash flows compare with today’s share price.
Origin Energy runs an integrated utility and gas portfolio, with the Energy Markets division producing about A$15.3b in revenue and Integrated Gas contributing roughly A$307 million, and the group valued at around A$20.8b by the market.
For investors watching how cash returns line up with valuation, Origin Energy offers a mix of regulated-style earnings and market exposed cash flows that can re-price quickly if conditions shift.
"Investor expectations around Origin Energy’s exposure to electrification remain high. Management guidance points to efficiency gains and distributed resources partly offsetting new residential load, which could limit long term electricity revenue growth if demand stays broadly flat."
The real test will be how one big capital spending wave filters into future margins if customer behaviour and policy do not cooperate.
If that payoff from heavy investment is what you care about, read the full narrative for Origin Energy to see how electrification risks and cash returns could be decoupling.
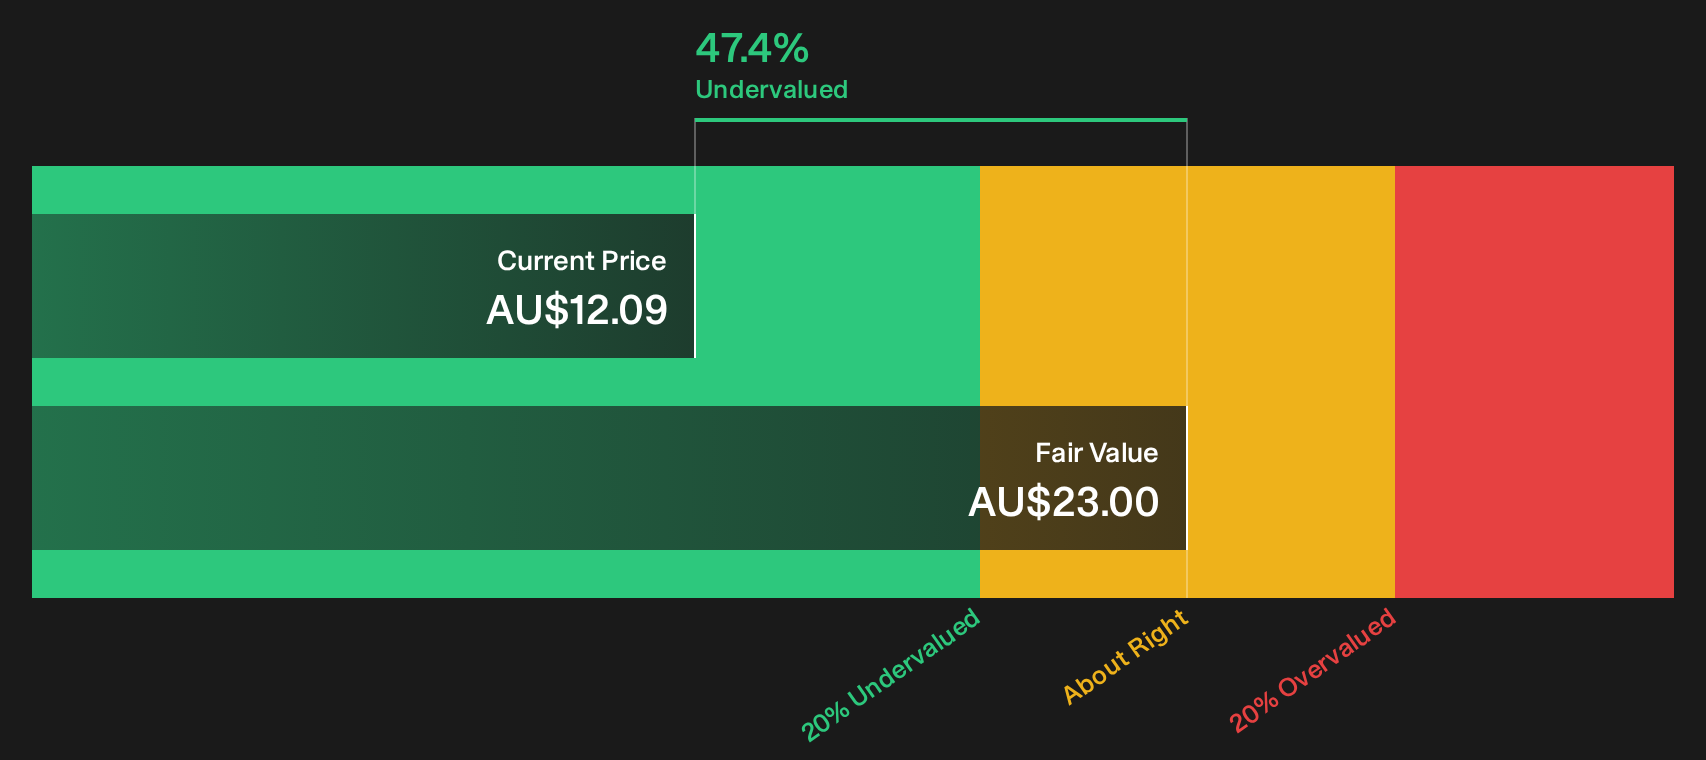
Life360 (ASX:360)
Life360 runs a freemium safety and location platform where paid tiers and Tile services create recurring cash flows that fit this screener’s focus on subscription driven value rather than one off gadget sales.
Life360 generates about $573 million from software and programming tied to its app and services, supported by Tile devices and related offerings worldwide, with the stock valued at roughly A$5.2b.
"Although Life360 has resumed its intended MAU glide path with over 102 million monthly active users, the earlier technical issues on Android and lower end devices that forced management to trim full year MAU expectations to 17 to 20% show how sensitive user growth is to product reliability. Similar setbacks, if they recur, could affect future subscription revenue and advertising reach."
One risk to consider is what happens if an unseen pressure in Life360’s cost base keeps pulling harder than subscriber and advertising monetisation can comfortably offset.
When that cost pressure keeps tugging, read the full narrative for Life360 to see whether Life360’s cash engine is quietly compounding or at risk of stalling.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. Stocks can break out while the crowd hesitates and information goes stale fast. Scan these under the radar lists while it matters and get in early.
- Spot cash machines with low volatility and stress test your defensive watchlist against the 6 resilient stocks with low risk scores before they get crowded by late arrivals.
- Target income workhorses that keep portfolios funded and pressure test your yield goals against the curated 4 dividend fortresses while prices and payouts still align.
- Ride next wave infrastructure momentum and line up potential compounding stories with the hand picked 42 power grid technology and infrastructure stocks before grid upgrades fully hit the headlines.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com