


EN
Is DexCom (DXCM) Cheap After CONNECT Trial Results Backed G7 Adoption?
DexCom (DXCM) is back in focus after publishing CONNECT trial data in The New England Journal of Medicine, highlighting clinical benefits of its G7 continuous glucose monitoring system for adults with Type 2 diabetes not on insulin.
The share price tells a mixed story. DexCom trades at US$78.57 after a 1-day share price return of 0.81%. However, the 7-day and 30-day share price returns are down 8.62% and 9.29%, suggesting some recent enthusiasm has cooled, even as the year-to-date share price return of 18.08% points to longer running momentum.
Spot opportunities around DexCom's CGM momentum by scanning a hand-picked set of medical and healthcare stocks with resilient fundamentals using the list of solid balance sheet and fundamentals (24 results).DexCom now sits between strong clinical validation and a choppy share price. Recent weakness could indicate sentiment fatigue rather than a shift in fundamentals. The next step is to see what the current valuation implies.
Most Popular Narrative: 21% Undervalued
The current DexCom share price of $78.57 sits below a fair value estimate of $99.69 according to the most followed valuation narrative. That gap reflects a view that the market is not fully pricing in the firm’s growth in continuous glucose monitoring and its profitability profile.
Revenue grew 13% year-over-year to $1.308 billion on a reported basis and 12% year-over-year on an organic 1 basis.
U.S. revenue grew 11% and international revenue grew 19% on a reported basis and 16% on an organic 1 basis, all on a year-over-year basis.
See why 1 investors see DexCom as 21% undervalued.
The narrative, according to MarkoVT, frames DexCom as a growth business with expanding profitability. It highlights guidance for 2026 revenue of $5.18b to $5.25b with targeted non GAAP operating margins of about 23.5% to 24% and adjusted EBITDA margins of roughly 31.5% to 32%.
That viewpoint also notes DexCom's forward revenue growth assumption of around 15% per year and a projected net profit margin near 14.5%. Against that backdrop, a forward P/E of roughly 31.75x is treated as consistent with the growth and margin profile rather than an outlier.
On these inputs, the fair value of $99.69 is presented as a long term anchor, using a 5 year CAGR to bridge current fundamentals and future earnings power. The current share price discount to that figure, at about 21%, is what underpins the undervalued label in the narrative.
Result: Fair Value of $99.69 (UNDERVALUED)
Still, DexCom’s story can be knocked off course if CGM adoption slows, or if rivals pressure pricing and squeeze those targeted margins.
Find out about the key risks to this DexCom narrative.
Another View: DexCom Through The Earnings Lens
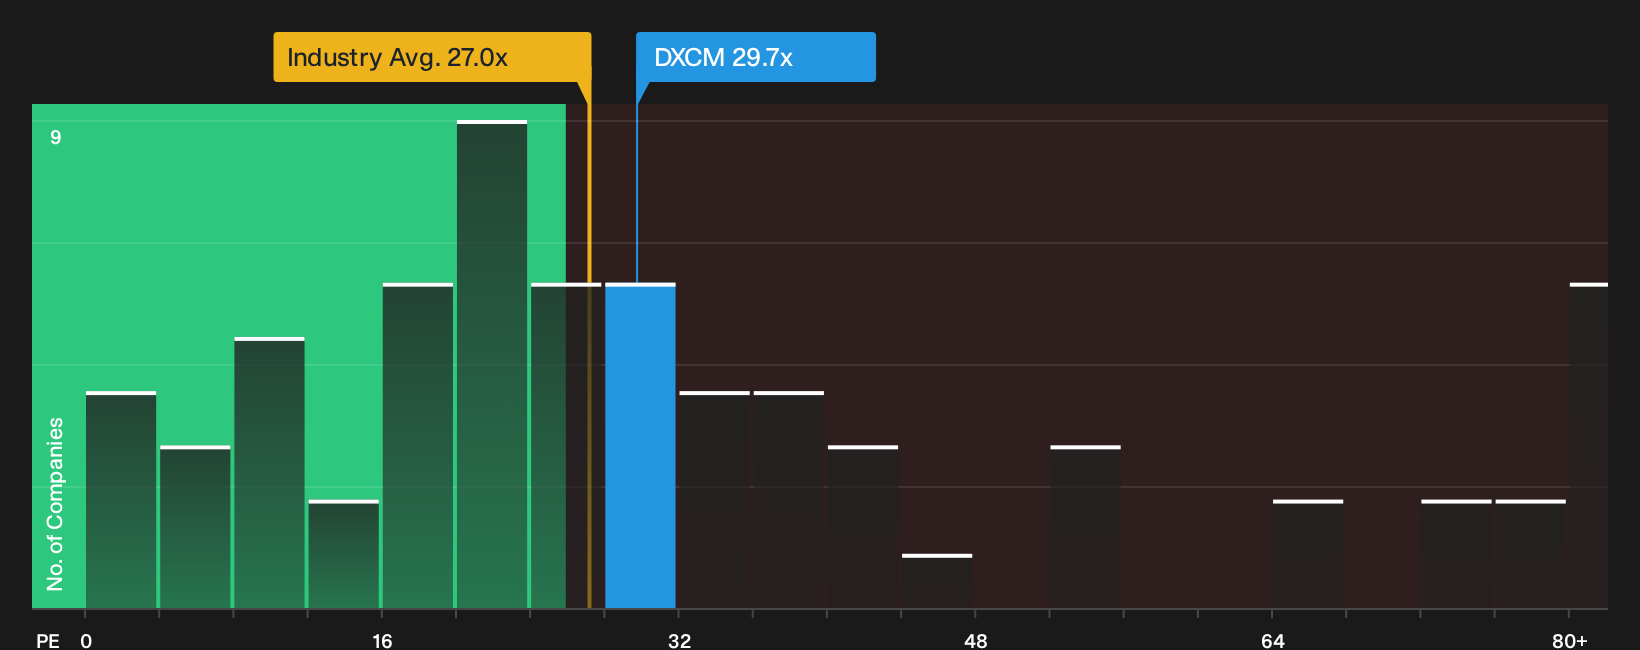
The popular community narrative argues DexCom is undervalued, yet the earnings multiple tells a tighter story. The stock trades on a P/E of 29.7x compared with a peer average of 26.8x and a US Medical Equipment industry average of 27x. Against a fair ratio of 31x, that leaves only a modest cushion. For investors, does paying above sector and industry while sitting just under the fair ratio feel like a margin of safety or a thin tightrope?
See what the numbers say about this price in our valuation breakdown with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of optimism and caution around DexCom leaves you undecided, move quickly and examine the details yourself using the 4 key rewards.
Looking for more DexCom style opportunities?
If DexCom has your attention, do not stop here. Fresh ideas across sectors can sharpen your watchlist and keep your next move intentional.
- Target higher potential upside by scanning a focused group of companies that screen as 29 high quality undervalued stocks.
- Strengthen your capital base by reviewing a 5 dividend fortresses that may help support returns through income in different market conditions.
- Dial down portfolio swings by filtering for 30 resilient stocks with low risk scores that score well on resilience and downside protection.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com