


EN
Will Presbyopia Approval Change Viatris (VTRS) Narrative
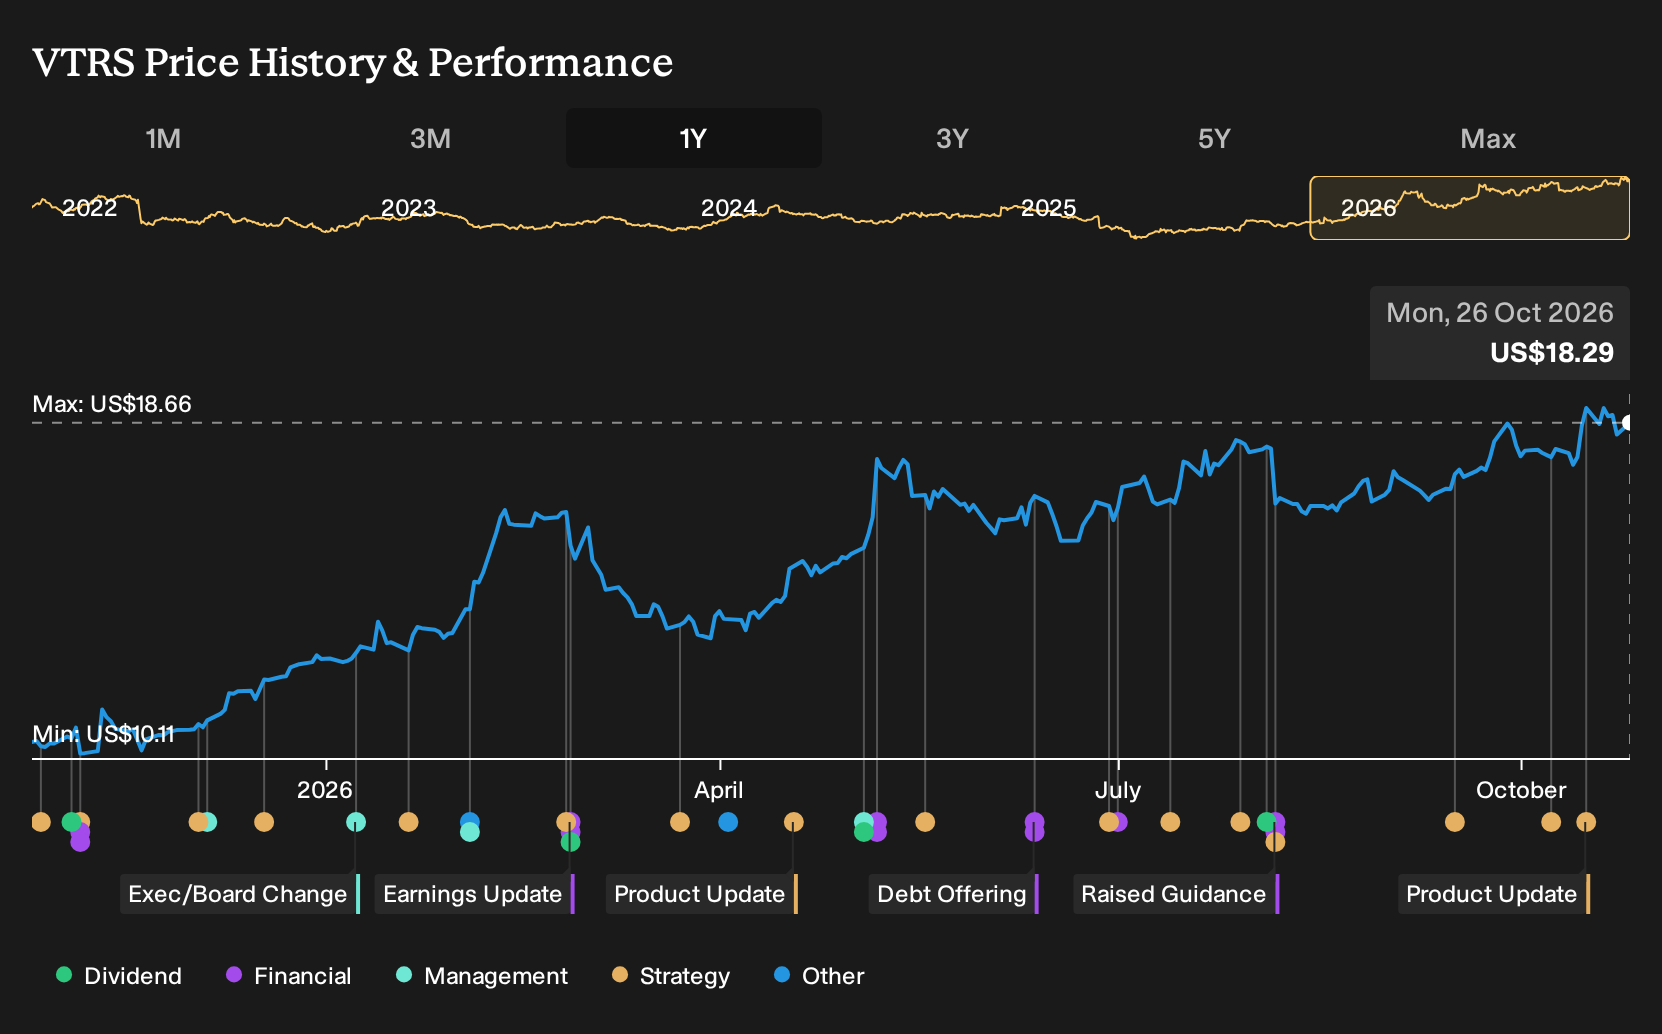
- Viatris reported that the U.S. FDA approved an expanded indication for RYZUMVI phentolamine ophthalmic solution 0.75% to treat presbyopia in adults, adding to its existing U.S. approval for pharmacologically induced mydriasis in adults and certain pediatric patients.
- This broader label addresses a nearly universal age related vision issue that affects everyday tasks. It could shift Viatris further toward higher value ophthalmology treatments with clearer clinical guidance on use and side effects.
- The focus now turns to how Viatris' investment narrative might evolve as RYZUMVI’s presbyopia label expansion reshapes its ophthalmology portfolio.
Scan beyond Viatris and line up other healthcare players exposed to aging demographics with the hand picked 34 healthcare AI stocks that are connecting treatment demand to new technology.
Viatris Investment Narrative Recap
To own Viatris, you need to believe the shift from a heavily generic driven portfolio to a mix that includes more complex, higher value therapies can offset pricing pressure and regulatory squeeze on older drugs. The RYZUMVI presbyopia approval fits that direction but looks like an incremental support to this thesis, not a near term game changer.
The key near term swing factor still sits in execution. That includes keeping integration and remediation work under control, managing leverage, and maintaining enough cash flexibility to fund product launches. The main operational risk remains ongoing price erosion in core markets that could blunt the benefit of any new approvals.
The RYZUMVI decision aligns with the broader ophthalmology and chronic disease focus already highlighted in Viatris commentary. Investors watching catalysts may view this as a proof point that late stage assets in eye care can move through regulators and into a commercial setting where margins are typically better than basic generics.
No single ophthalmology approval solves the bigger issues around mature product reliance, competition from low cost manufacturers, and regulatory pressure. It does, however, provide something tangible to track around execution quality, safety profile management, and uptake in a large, age driven condition that corresponds with Viatris exposure to global demographic trends.
Viatris' current analyst narrative points to revenue of US$15.8b and earnings of US$704.2m by 2029. This outlook assumes revenue expands by 2.4% per year and earnings rise by about US$1.1b from a loss of US$410.7m today.
Uncover how Viatris' fair value indicates a 9% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
You might see this RYZUMVI approval and think it solves everything for Viatris, yet the lowest analysts lean hard on a different angle. They worry uptake of higher margin products could disappoint and keep earnings closer to about US$555.1m on roughly US$15.5b of revenue by 2029. These pre news views may shift, so explore both perspectives before deciding what makes sense to you.
Explore 5 other Viatris fair value estimates, including one that suggests it could be worth just $19.90.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Viatris research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Viatris. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Viatris' overall financial health at a glance.
Looking For More Investment Ideas Beyond Viatris?
If the Viatris story has you thinking about where else aging demographics, solid balance sheets, or income potential might line up with your own approach, it can help to scan a broader set of companies with similar traits.
- For investors who care most about financial resilience, start with a list of solid balance sheet and fundamentals (24 results) that can help you focus on businesses with stronger financial footing.
- If income is your priority, filter for companies offering higher yields with the 5 dividend fortresses and see which payouts might align with your tolerance for risk.
- Those hunting for mispriced quality can use the 29 high quality undervalued stocks to spot opportunities that combine sound fundamentals with a discounted market tag.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com