


EN
Could Fair Value Estimates Just Shift STEF (ENXTPA:STF) Stock Narrative?
- Analysts recently highlighted that STEF's estimated intrinsic value from a Discounted Cash Flow model is materially higher than its current trading level. This brings renewed focus to how much cash the logistics group might generate in the years ahead.
- The discussion centers on whether STEF's existing operations and cash producing capacity justify this valuation gap. This puts the spotlight on the resilience of its freight network, cost discipline, and contract quality rather than market sentiment alone.
- We will now look at how this DCF driven undervaluation debate could reshape STEF's investment narrative for long term shareholders.
What Is STEF's Investment Narrative?
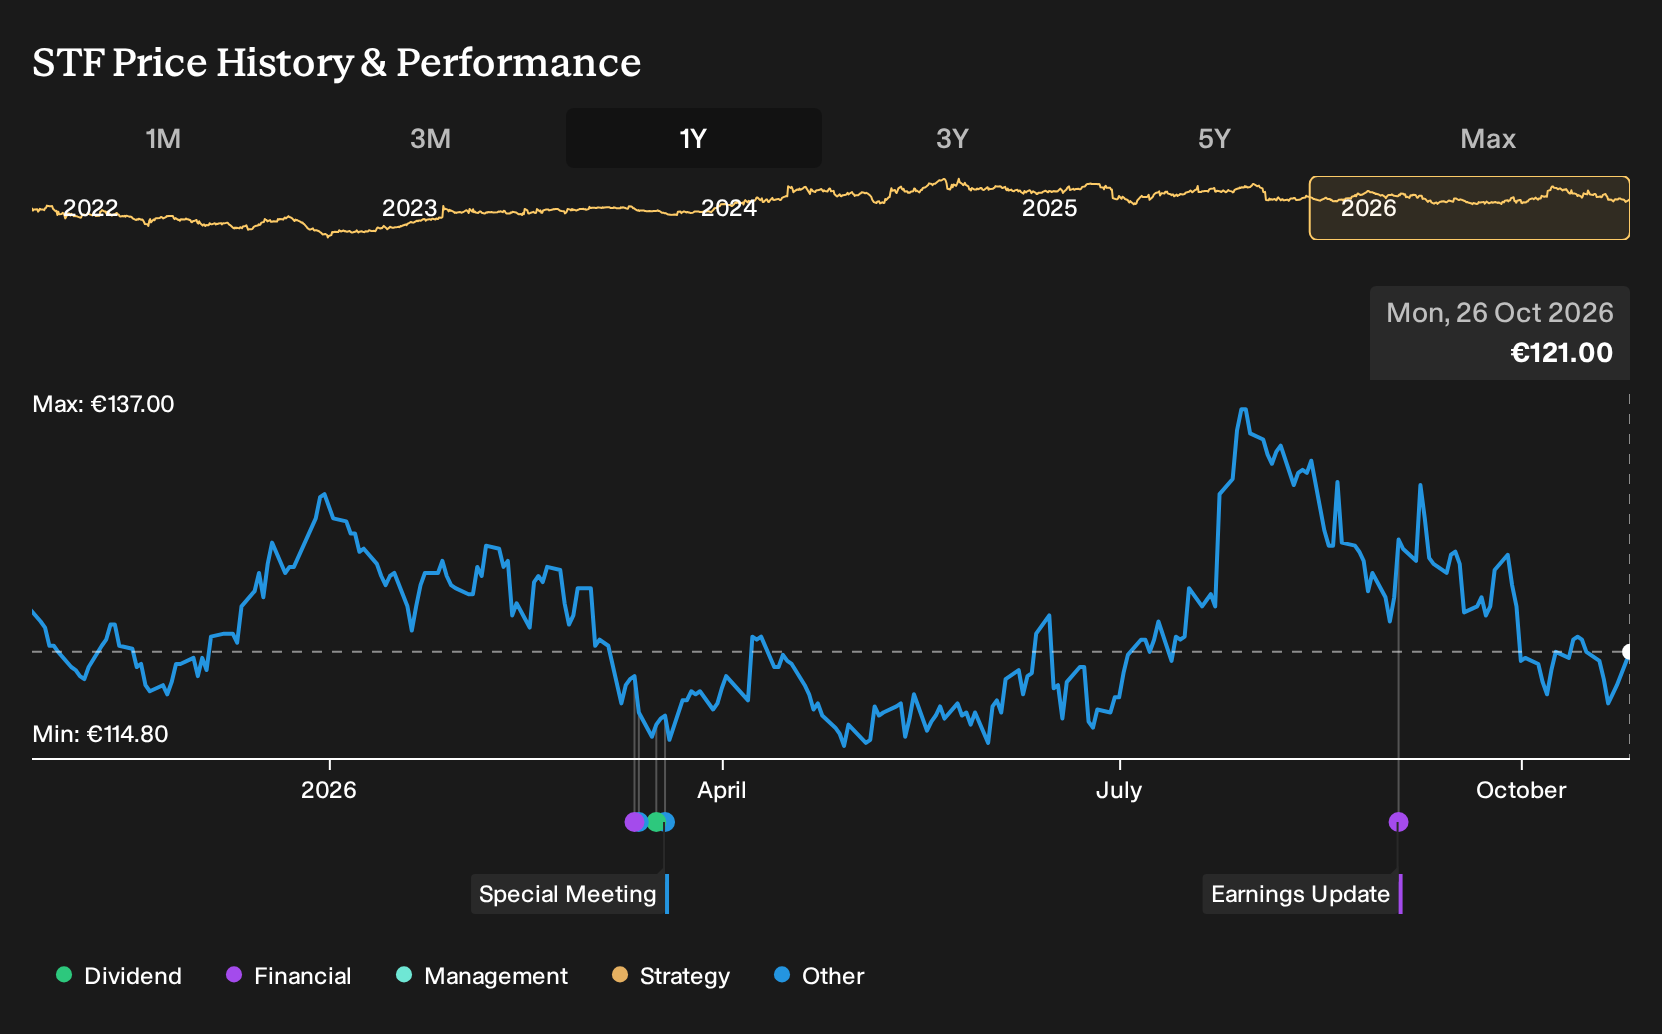
To own STEF, you really need to buy into a fairly straightforward idea. A temperature controlled logistics specialist that turns a dense European network into consistent cash generation, even if top line expansion is relatively modest. The recent focus on the DCF work leans on that premise. It suggests the current €121 share price discounts more cautious cash production than the modelled path, despite earnings growth of 28.7% over the past year and a P/E of 12.3x that sits below both peers and the European transportation average.
In the short term, the main swing factors still look operational. Contract quality, freight volumes and pricing discipline across France and international segments will matter more than any single valuation headline. Capital intensity remains real for STEF, given its asset heavy, cold chain footprint, and the high debt load flagged in the risk work keeps financing conditions relevant. The DCF driven undervaluation story adds pressure for execution to stay tight, because any wobble in margins or cash conversion could challenge the idea that this gap is purely about market perception.
That said, there is one structural weak spot in the STEF story that keeps nagging once you look closer at ...
There's only one way to know the right time to buy, sell or hold STEF. Head to Simply Wall St's company report for the latest analysis of STEF's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community currently shows 2 fair value views on STEF, spread between about €149 and roughly €213 per share, so retail opinions already span a wide band. Those assessments were made before the latest DCF focus. This gives you a reason to revisit the assumptions and weigh several contrasting viewpoints yourself.
Explore another STEF fair value estimate, including one that suggests potential upside of up to 76% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your STEF research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for STEF. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate STEF's overall financial health at a glance.
Looking For More Ideas Beyond STEF?
If the valuation debate around STEF has you thinking about what else might be mispriced, the Simply Wall St Screener can help you scan the market in a structured way rather than relying on hunches.
- For investors who care most about resilience, focus on businesses with robust finances and low risk profiles through a 223 resilient stocks with low risk scores.
- If steady income is your priority, zero in on companies that combine higher yields with balance sheet support using a 224 dividend fortresses.
- When you want to spot lesser known opportunities with solid fundamentals, sift through a 610 high quality undiscovered gems that might not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com