


EN
Why Did Oxford Nanopore Technologies (LSE:ONT) Shares Climb?
Executive appointment puts Oxford Nanopore in focus
Oxford Nanopore Technologies (LSE:ONT) moved into the spotlight after naming Sebastian Kronmueller as Chief Business Development Officer, with a mandate to shape partnerships and long term commercial direction from a US base.
Investors have already been re-rating Oxford Nanopore Technologies, with a 90-day share price return of 93.17% and a year-to-date share price gain of 67.97% at a latest share price of £2.15. The 1-year total shareholder return of 55.57% and 5-year total shareholder return decline of 61.68% show strong recent momentum set against a much weaker longer-term record that this executive hire may be intended to reshape.
Scan how Oxford Nanopore Technologies compares with other fast moving healthcare and genomics plays by reviewing the hand picked 8 healthcare AI stocks in this space.
The latest surge leaves Oxford Nanopore trading slightly above analyst targets, yet still at a material discount to some fair value estimates. Is that a bargain signal, or a warning that caution is justified?
Preferred Price-to-Sales of 8.9x for Oxford Nanopore Technologies: Is it justified?
Oxford Nanopore Technologies trades on a P/S ratio of 8.9x, which is high compared to both the European life sciences industry and its closest peers, even though the SWS DCF model suggests a fair value above the current £2.15 share price.
The P/S ratio compares the market value of the equity to annual revenue and is a common yardstick for loss making life sciences groups where earnings are not yet a clean guide. For Oxford Nanopore Technologies, this means investors are currently paying 8.9 times its £235.0m of revenue for 2023.
That multiple is well above the 3.6x industry average and far above the 2.6x peer group reference. This indicates that buyers are accepting a rich revenue valuation for this business. Against that, the estimated fair P/S ratio is 6.9x, a level the market could move towards if enthusiasm cools or growth expectations change.
Explore the SWS fair ratio for Oxford Nanopore Technologies.
Result: Price-to-Sales of 8.9x (OVERVALUED)
Still, Oxford Nanopore faces clear risks if revenue growth stalls or losses remain high, which could challenge its relatively high 8.9x P/S multiple.
Find out about the key risks to this Oxford Nanopore Technologies narrative.
Another view on Oxford Nanopore Technologies’ value
While the 8.9x P/S ratio presents Oxford Nanopore Technologies as expensive on sales, the SWS DCF model suggests a different perspective. On that basis, the shares trade at £2.15 against an estimated future cash flow value of £3.23, which frames the current quote as undervalued.
The gap between an apparently rich revenue multiple and a DCF value that is 33.5% higher raises a practical question for readers. Which risk weighs more: paying up for £235.0m of revenue today, or relying on cash flows that are not expected to turn profitable within three years?
Look into how the SWS DCF model arrives at its fair value.
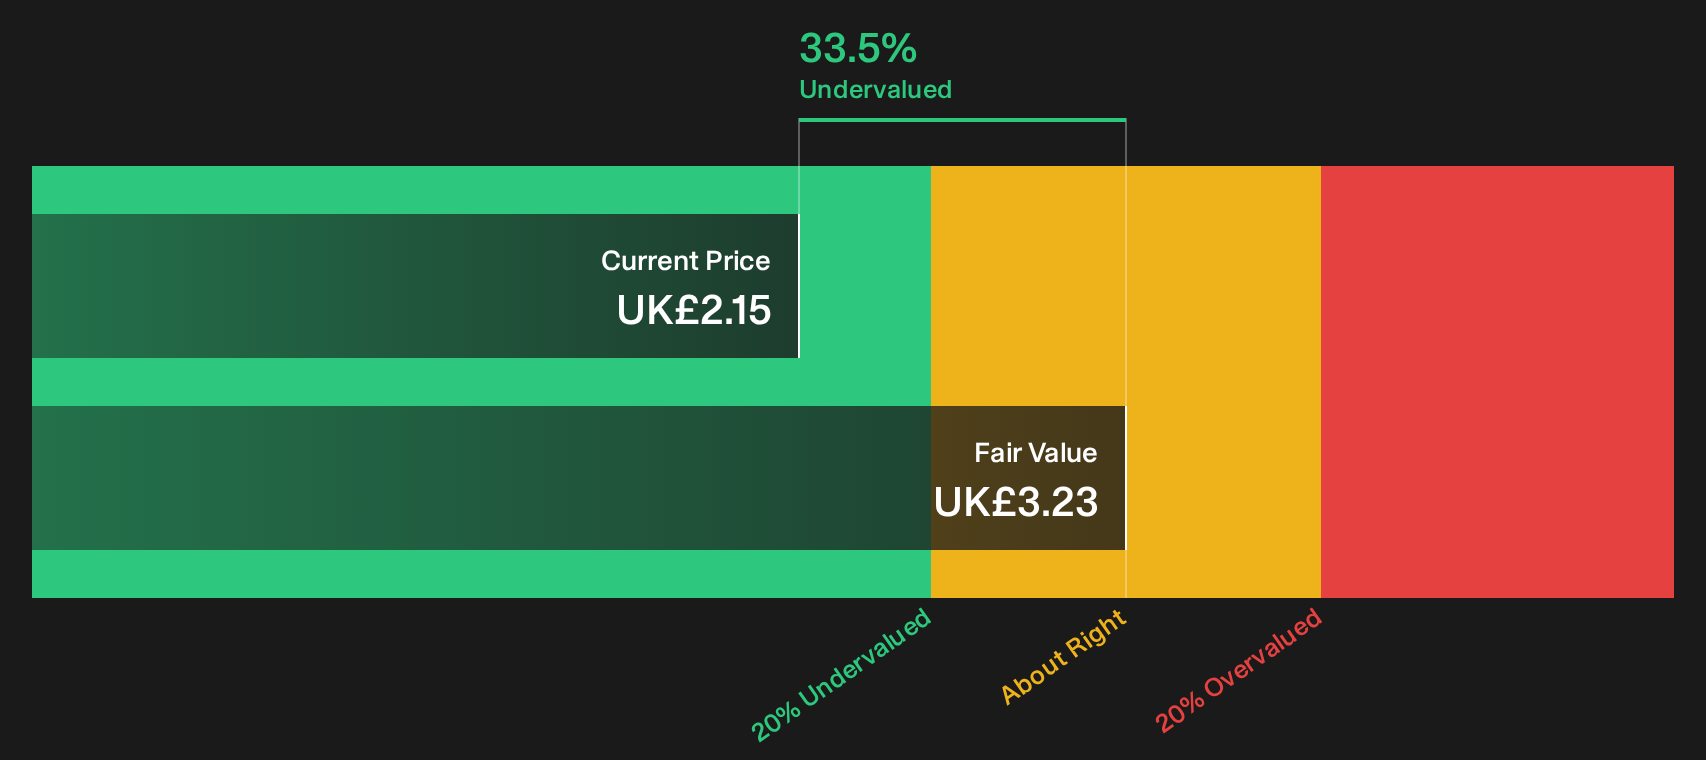
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Oxford Nanopore Technologies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 10 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty of signals around Oxford Nanopore point in different directions, so move quickly, review the data for yourself, and weigh both sides. To see the full balance of optimism and concern in one place, start with these 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Oxford Nanopore?
Do not stop with Oxford Nanopore Technologies. Broaden your watchlist with fresh ideas that match your risk, return, and income goals before the next move arrives.
- Target potential mispricings by scanning companies that screen as 10 high quality undervalued stocks based on their fundamentals and current market prices.
- Lock in income ideas by reviewing a curated pool of 5 dividend fortresses that focus on higher yielding payouts.
- Prioritise resilience by filtering for a 4 resilient stocks with low risk scores that emphasises sturdier balance sheets and steadier risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com