


EN
Has PayPal Holdings (PYPL) Fallen Far Enough To Look Undervalued?
PayPal Holdings has gone from market favorite to a stock that has fallen sharply over the past five years, which puts a spotlight on a simple question for you as an investor: Is the current share price near US$55 still in line with what its earnings can reasonably support?
- Over the past 5 years, PayPal Holdings has fallen about 76%, which puts pressure on the idea that its earnings story may need to do more work to justify where the shares trade today.
- New partnerships, such as PayPal’s tie up with LianLian Global and AI powered checkout with Glance, can influence how investors think about future transaction volumes, fee levels, and ultimately the profit base used to value the business.
- There is a second opinion on PayPal Holdings worth weighing. See what analysts think PayPal Holdings's shares could be worth.
The issue now is whether PayPal Holdings' current market price is adequately supported by the earnings it is producing today and those investors expect it to generate in the coming years.
To see how PayPal Holdings compares with other earnings-focused opportunities in this part of the market, review it alongside companies in the 29 high quality undervalued stocks
Is PayPal Holdings Still Cheap on Earnings?
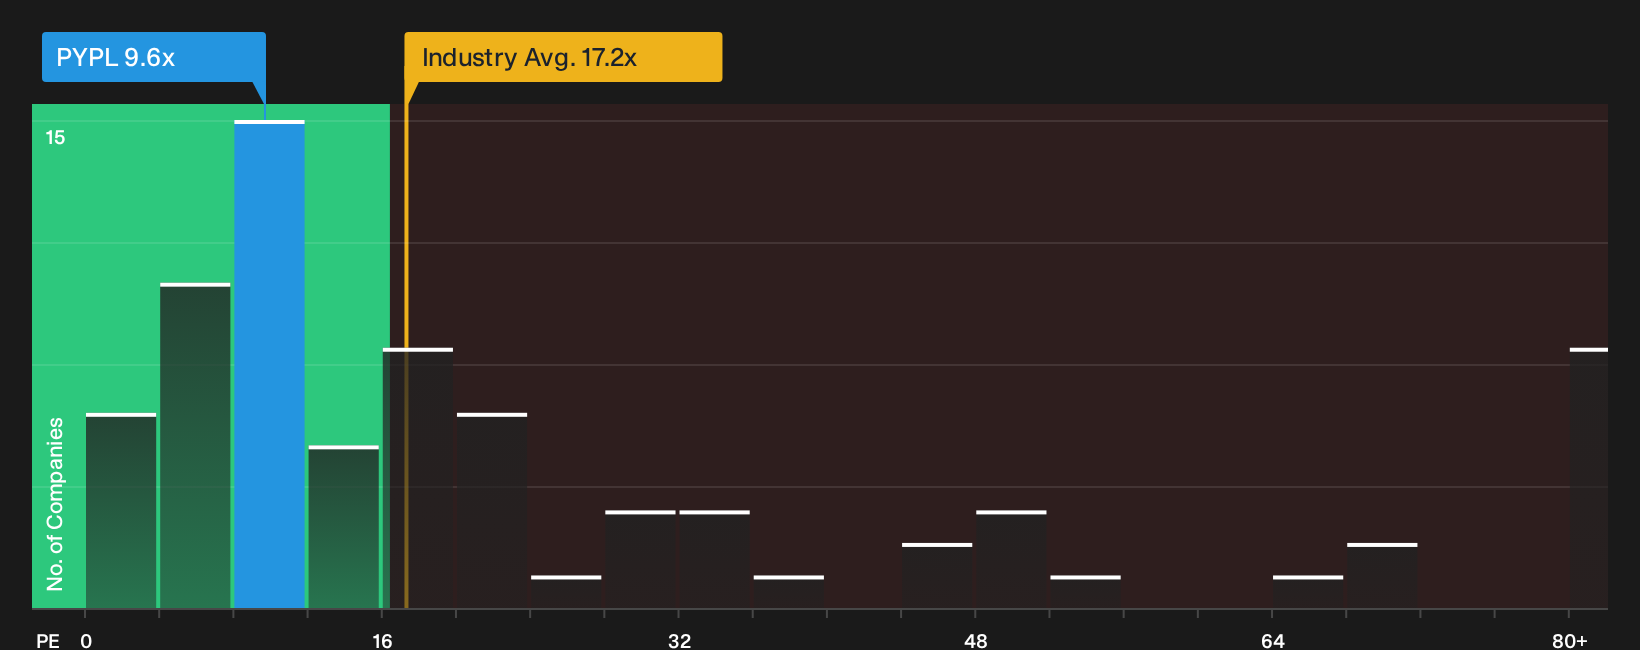
P/E suits PayPal Holdings because earnings remain the main yardstick investors use to judge mature payment platforms. At a current P/E of about 9.6x, the stock trades at a sizeable discount to the diversified financial industry average of roughly 17.2x and the peer group near 41.0x. On this framework, the valuation model suggests a tailored fair P/E that is higher than where PayPal changes hands today, which points to the shares pricing in a weaker outlook or higher risks than that model assumes.
Because the recent Glance partnership and other product pushes have not stopped analysts downgrading PayPal on growth and market share concerns, this gap in P/E multiples reflects a market that is wary even while the stock screens as undervalued on earnings compared with that fair benchmark and peers. Explore the numbers behind PayPal Holdings's P/E valuation.
The PayPal Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for PayPal Holdings sit between that P/E puzzle and the real world, by laying out which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than it is today on the screen. Rather than stopping at a single ratio or model output, these scenarios spell out the future that figure leans on so you can watch over time whether those conditions actually show up.
Community views on PayPal Holdings pull in opposite directions, with one group focused on cash generation and another on pressure in the payments engine.
Bull case: 33% undervalued
"By remaining a fintech, PayPal retains the flexibility to return that excess capital to you, the shareholder, through its aggressive buyback program..."
Discover why this Narrative puts PayPal Holdings at 33% undervalued.
Bear case: 43% overvalued
"Bearish analysts expect PayPal Holdings to keep facing pressure on transaction economics as the mix shifts toward Venmo and Braintree, with the transaction take rate at 1.61% in Q2 2026..."
Explore why this Narrative puts PayPal Holdings at 43% overvalued.
Before acting on PayPal Holdings’ valuation, one more issue deserves attention
Price tags and P/E ratios only tell part of the PayPal Holdings story, because recent checks have surfaced specific business risks that could change how you read all of those numbers. Take a closer look at 1 major warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com