


EN
Asian Growth Stocks Insiders Are Investing In
In recent weeks, Asian markets have experienced heightened volatility, influenced by global concerns over AI investments and rising oil prices. Amid this backdrop, growth companies with high insider ownership can offer unique insights into potential opportunities, as insiders often have a deep understanding of their company's prospects.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.8% |
| SEERS (KOSDAQ:A458870) | 33.6% | 37.8% |
| Meitu (SEHK:1357) | 23.1% | 26.5% |
| Meiko Electronics (TSE:6787) | 19.2% | 34% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Gold Circuit Electronics (TWSE:2368) | 29.9% | 46.1% |
| Fulin Precision (SZSE:300432) | 11.7% | 66.5% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
Below we spotlight a couple of our favorites from our exclusive screener.
Meitu (SEHK:1357)
Simply Wall St Growth Rating: ★★★★★★
Overview: Meitu, Inc. is an investment holding company that develops and provides AI-powered products for photo, video, and design production in Mainland China and internationally, with a market cap of approximately HK$17.67 billion.
Operations: The company generates revenue from its Internet Business segment, amounting to CN¥4.26 billion.
Insider Ownership: 23.1%
Meitu, Inc. demonstrates growth potential with high insider ownership and recent substantial insider buying. The company's revenue is forecast to grow over 20% annually, outpacing the Hong Kong market's 8.7%. Recent product innovations like Wink's HD Video Converter and MVLAND's Studio Mode enhance its competitive edge in AI-driven content creation. Meitu reported a net income of CNY 619.46 million for H1 2026, reflecting strong financial performance amid strategic expansions and executive board changes involving Alibaba Subscriber’s nomination of Mr. Jin Qin as a non-executive director.
- Click here and access our complete growth analysis report to understand the dynamics of Meitu.
- In light of our recent valuation report, it seems possible that Meitu is trading behind its estimated value.
Yonghui Superstores (SHSE:601933)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Yonghui Superstores Co., Ltd. operates and owns various supermarkets in China with a market cap of CN¥26.24 billion.
Operations: Revenue Segments (in millions of CN¥): Retail contributed CN¥89,560 and Wholesale added CN¥1.76 billion.
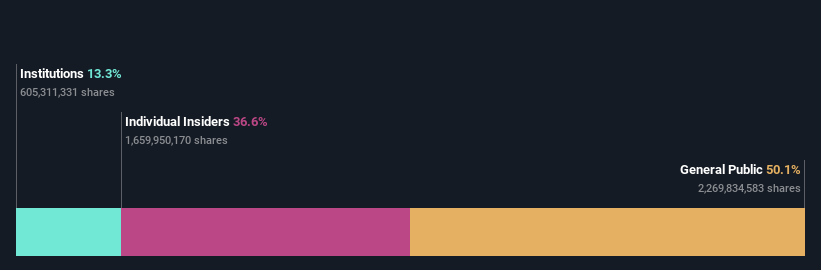
Insider Ownership: 16%
Yonghui Superstores exhibits potential with high insider ownership, despite mixed financial results. For H1 2026, the company reported CNY 23.79 billion in sales and a net income of CNY 253.16 million, recovering from a previous loss. Trading at a large discount to its estimated fair value, Yonghui is forecast to achieve profitability within three years with above-average profit growth expectations. However, its revenue growth is projected to lag behind the broader Chinese market's pace.
- Click here to discover the nuances of Yonghui Superstores with our detailed analytical future growth report.
- Our valuation report unveils the possibility Yonghui Superstores' shares may be trading at a discount.
3Peak (SHSE:688536)
Simply Wall St Growth Rating: ★★★★★☆
Overview: 3Peak Incorporated focuses on the research, development, testing, and sale of integrated circuits, application systems, and software both in China and internationally with a market cap of CN¥37.15 billion.
Operations: The company's revenue primarily comes from the Integrated Circuit Industry, generating CN¥2.80 billion.
Insider Ownership: 13.4%
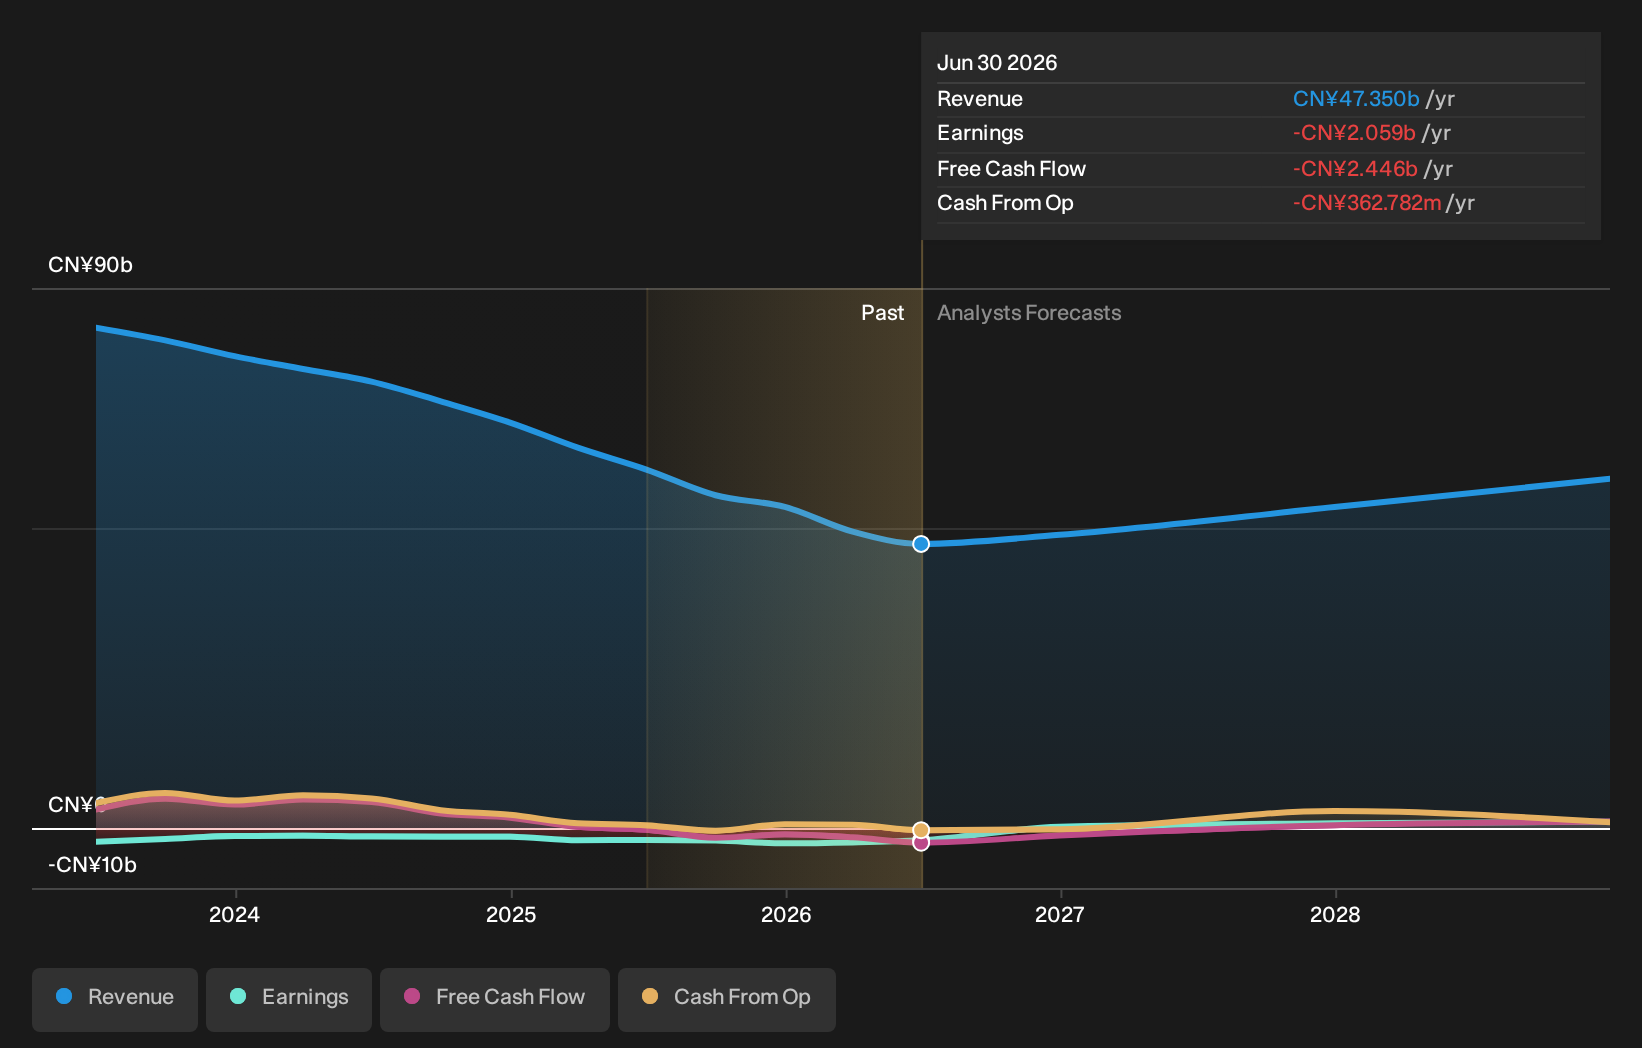
3Peak shows strong insider ownership and impressive financial growth, with H1 2026 revenue reaching CNY 1.61 billion, up from CNY 949.15 million a year ago. Net income surged to CNY 307.76 million from CNY 65.69 million, reflecting robust profit expansion as it became profitable this year. Despite recent share price volatility, analysts forecast significant annual earnings growth of over 43%, outpacing the broader Chinese market's expected profit increase of 26.7%.
- Get an in-depth perspective on 3Peak's performance by reading our analyst estimates report here.
- According our valuation report, there's an indication that 3Peak's share price might be on the expensive side.

Seize The Opportunity
- Delve into our full catalog of 512 Fast Growing Asian Companies With High Insider Ownership here.
- Ready For A Different Approach? AI is about to change healthcare. These 123 stocks are working on everything from early diagnostics to drug discovery. The best part - they are all under $10b in market cap - there's still time to get in early.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com