


EN
Unveiling Three Undiscovered Gems in Asia with Strong Potential
As global markets experience volatility driven by AI investment concerns and rising oil prices, small-cap stocks have notably outperformed, with the Russell 2000 Index advancing 2.00% amid a rotation in market leadership. In this dynamic environment, identifying promising small-cap stocks in Asia requires a keen focus on companies with robust fundamentals and the ability to navigate economic shifts effectively.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Eurocharm Holdings | 2.66% | 3.48% | 7.39% | ★★★★★★ |
| AMPAK Technology | 34.99% | -10.73% | -19.52% | ★★★★★☆ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Silvery Dragon Group Tianjin | 25.01% | 2.55% | 25.62% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Primo Global Holdings | 64.63% | 9.93% | 28.27% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
| Ta Tun Electric Wire & Cable | 70.16% | 6.67% | 33.41% | ★★★☆☆☆ |
We're going to check out a few of the best picks from our screener tool.
Befar Group (SHSE:601678)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Befar Group Co., Ltd is involved in the manufacturing and sale of chemicals, with a market capitalization of CN¥10.81 billion.
Operations: Befar Group generates revenue primarily from its chemical industry segment, amounting to CN¥15.74 billion.
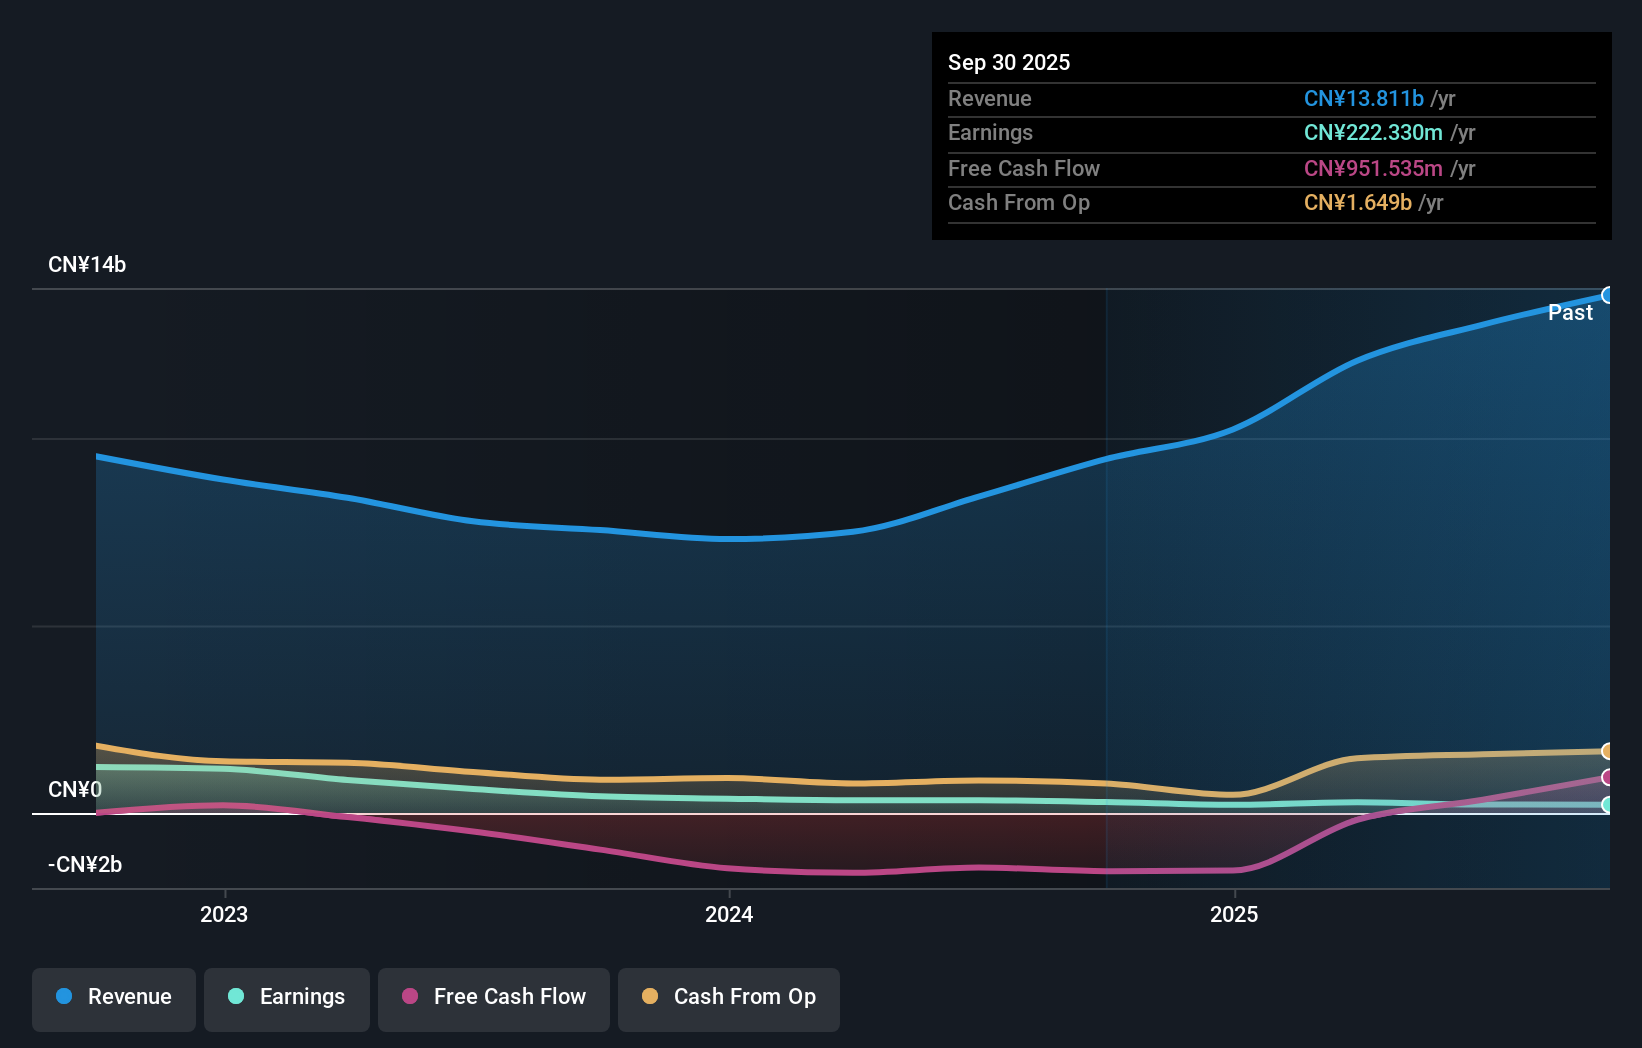
Befar Group, a small player in the chemicals industry, has shown impressive financial performance with earnings growth of 102.8% over the past year, significantly outpacing the industry's 2.9%. Its debt to equity ratio rose from 47.4% to 69.2% over five years, indicating increased leverage but still maintaining interest coverage at 3.4 times EBIT. Trading at nearly 90% below its estimated fair value suggests potential for future gains despite high net debt to equity of 54.2%. Recent results show sales climbing to CNY12.68 billion and net income reaching CNY358 million for nine months ended September, reflecting robust operational progress.
- Dive into the specifics of Befar Group here with our thorough health report.
Review our historical performance report to gain insights into Befar Group's's past performance.
Xinxing Ductile Iron Pipes (SZSE:000778)
Simply Wall St Value Rating: ★★★★★★
Overview: Xinxing Ductile Iron Pipes Co., Ltd. operates in the production and distribution of cast iron pipes and steel both within China and internationally, with a market capitalization of approximately CN¥13.79 billion.
Operations: The company generates revenue primarily from the Metal Products Industry, amounting to CN¥41.59 billion.
Xinxing Ductile Iron Pipes, a smaller player in the industry, has shown resilience with its earnings growing by 80.5% over the past year, outpacing the sector's 23.6%. The company's net debt to equity ratio stands at a satisfactory 13.6%, having improved from 51.1% five years ago. Despite reporting lower net income of CNY 444 million for nine months ending September 2026, compared to CNY 699 million last year, sales increased to CNY 31.75 billion from CNY 27.18 billion previously. With interest payments well-covered by EBIT at a robust multiple of 16x and trading significantly below fair value estimates, Xinxing appears undervalued relative to peers and industry standards.

Ardentec (TPEX:3264)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Ardentec Corporation provides semiconductor testing solutions for memory, logic, and mixed-signal ICs to various clients worldwide, with a market cap of NT$116.82 billion.
Operations: The primary revenue streams for Ardentec Corporation come from providing semiconductor testing solutions to integrated device manufacturers, wafer foundry companies, and fabless design companies across multiple regions. The company's gross profit margin has shown variability over recent periods.
Ardentec, a dynamic player in the semiconductor industry, showcases impressive growth with earnings surging 80.8% over the past year, outpacing the industry average of 44.3%. The company's net debt to equity ratio stands at a satisfactory 36.5%, although it has risen from 54% to 67.2% over five years. Recent earnings results highlight robust performance; for Q3, sales reached TWD 5.34 billion compared to TWD 3.59 billion last year, while net income jumped to TWD 1.47 billion from TWD 827 million previously. Despite high volatility in share price recently, Ardentec's EBIT covers interest payments comfortably at a multiple of 25 times.

Taking Advantage
- Investigate our full lineup of 133 Asian Undiscovered Gems With Strong Fundamentals right here.
- Hold shares in these firms? Setup your portfolio in Simply Wall St to seamlessly track your investments and receive personalized updates on your portfolio's performance.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com