


EN
How Investors Are Reacting To Takara Holdings (TSE:2531) Activist Push For Changes
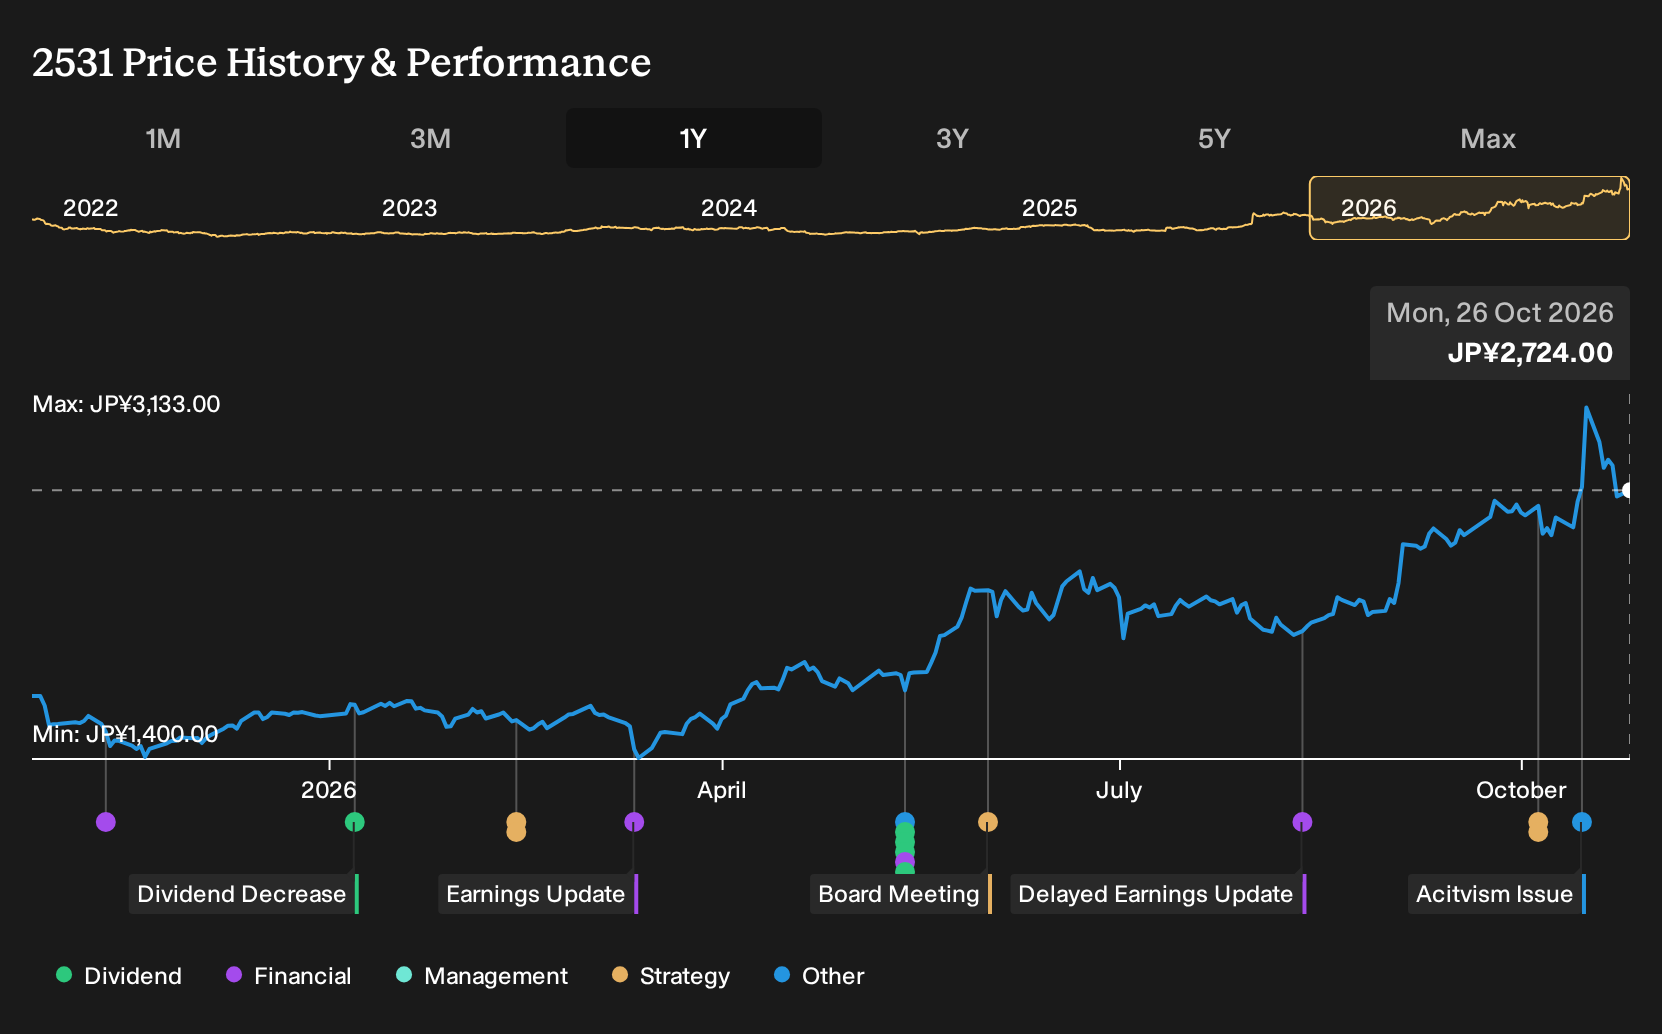
- Oasis Management disclosed in mid October 2026 that it had built a 5.09% stake in Takara Holdings and is pushing for changes to capital allocation, including potential divestiture of certain operations, after a quarter where revenue growth coincided with weaker net income and earnings per share.
- The activist’s focus on portfolio simplification and governance comes at a time when Takara Holdings trades on a relatively high trailing P/E versus peers. This has sharpened investor attention on earnings quality rather than just top line momentum.
- The next section will examine how Takara Holdings' investment narrative could shift as Oasis presses for divestitures and capital allocation discipline.
Compare how activists and valuation pressure are playing out at Takara Holdings with other companies that currently screen as 16 high quality undervalued stocks on Simply Wall St.
What Is Takara Holdings' Investment Narrative?
To own Takara Holdings, you need to believe the combination of a long established alcohol and seasoning operation, a niche but complex biotech arm, and ancillary logistics and services can earn its relatively high P/E multiple through better execution, not just revenue growth. Recent results showed higher sales alongside weaker net income and thinner profit margins. This puts the spotlight on pricing power, cost control, and how capital is deployed across these diverse segments.
That is where Oasis Management’s 5.09% stake and push for divestitures comes in. Pressure to rethink capital allocation, including potentially trimming or transferring parts of the portfolio, could change short term catalysts from pure earnings prints toward decisions on asset mix, debt, and cash use. The biggest operational risk right now is that earnings have declined over the past 5 years while the share price has been strong. Any shift in the business mix or governance that fails to improve profitability would likely be felt quickly.
Yet one unresolved issue still hangs over Takara Holdings, and it sits squarely in the same frame as Oasis’s campaign...
There's only one way to know the right time to buy, sell or hold Takara Holdings. Head to Simply Wall St's company report for the latest analysis of Takara Holdings's Fair Value.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Takara Holdings research is our analysis highlighting 3 important warning signs that could impact your investment decision.
- See our latest analysis for Takara Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Takara Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Takara Holdings?
If the Takara Holdings story has you thinking about portfolio balance, use this as a prompt to widen your search across other businesses with different risk and return profiles using the Simply Wall St Screener.
- For investors who want a focus on financial resilience, start with a list of solid balance sheet and fundamentals (23 results) that can help you filter for companies where debt and liquidity look more robust.
- If income is a priority, scan for potential yield opportunities across a curated set of 29 dividend fortresses that might suit a dividend-focused approach.
- When you want potential mispricing ideas, broaden your watchlist by reviewing a 72 high quality undiscovered gems that highlights lesser known businesses with strong fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com